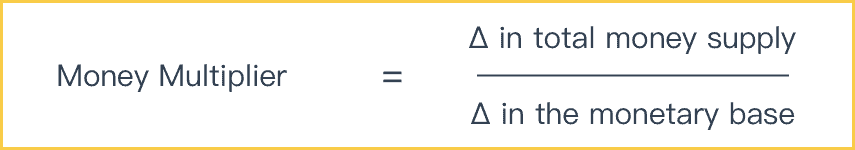How The Money Multiplier Actually Works When You Try To Use It
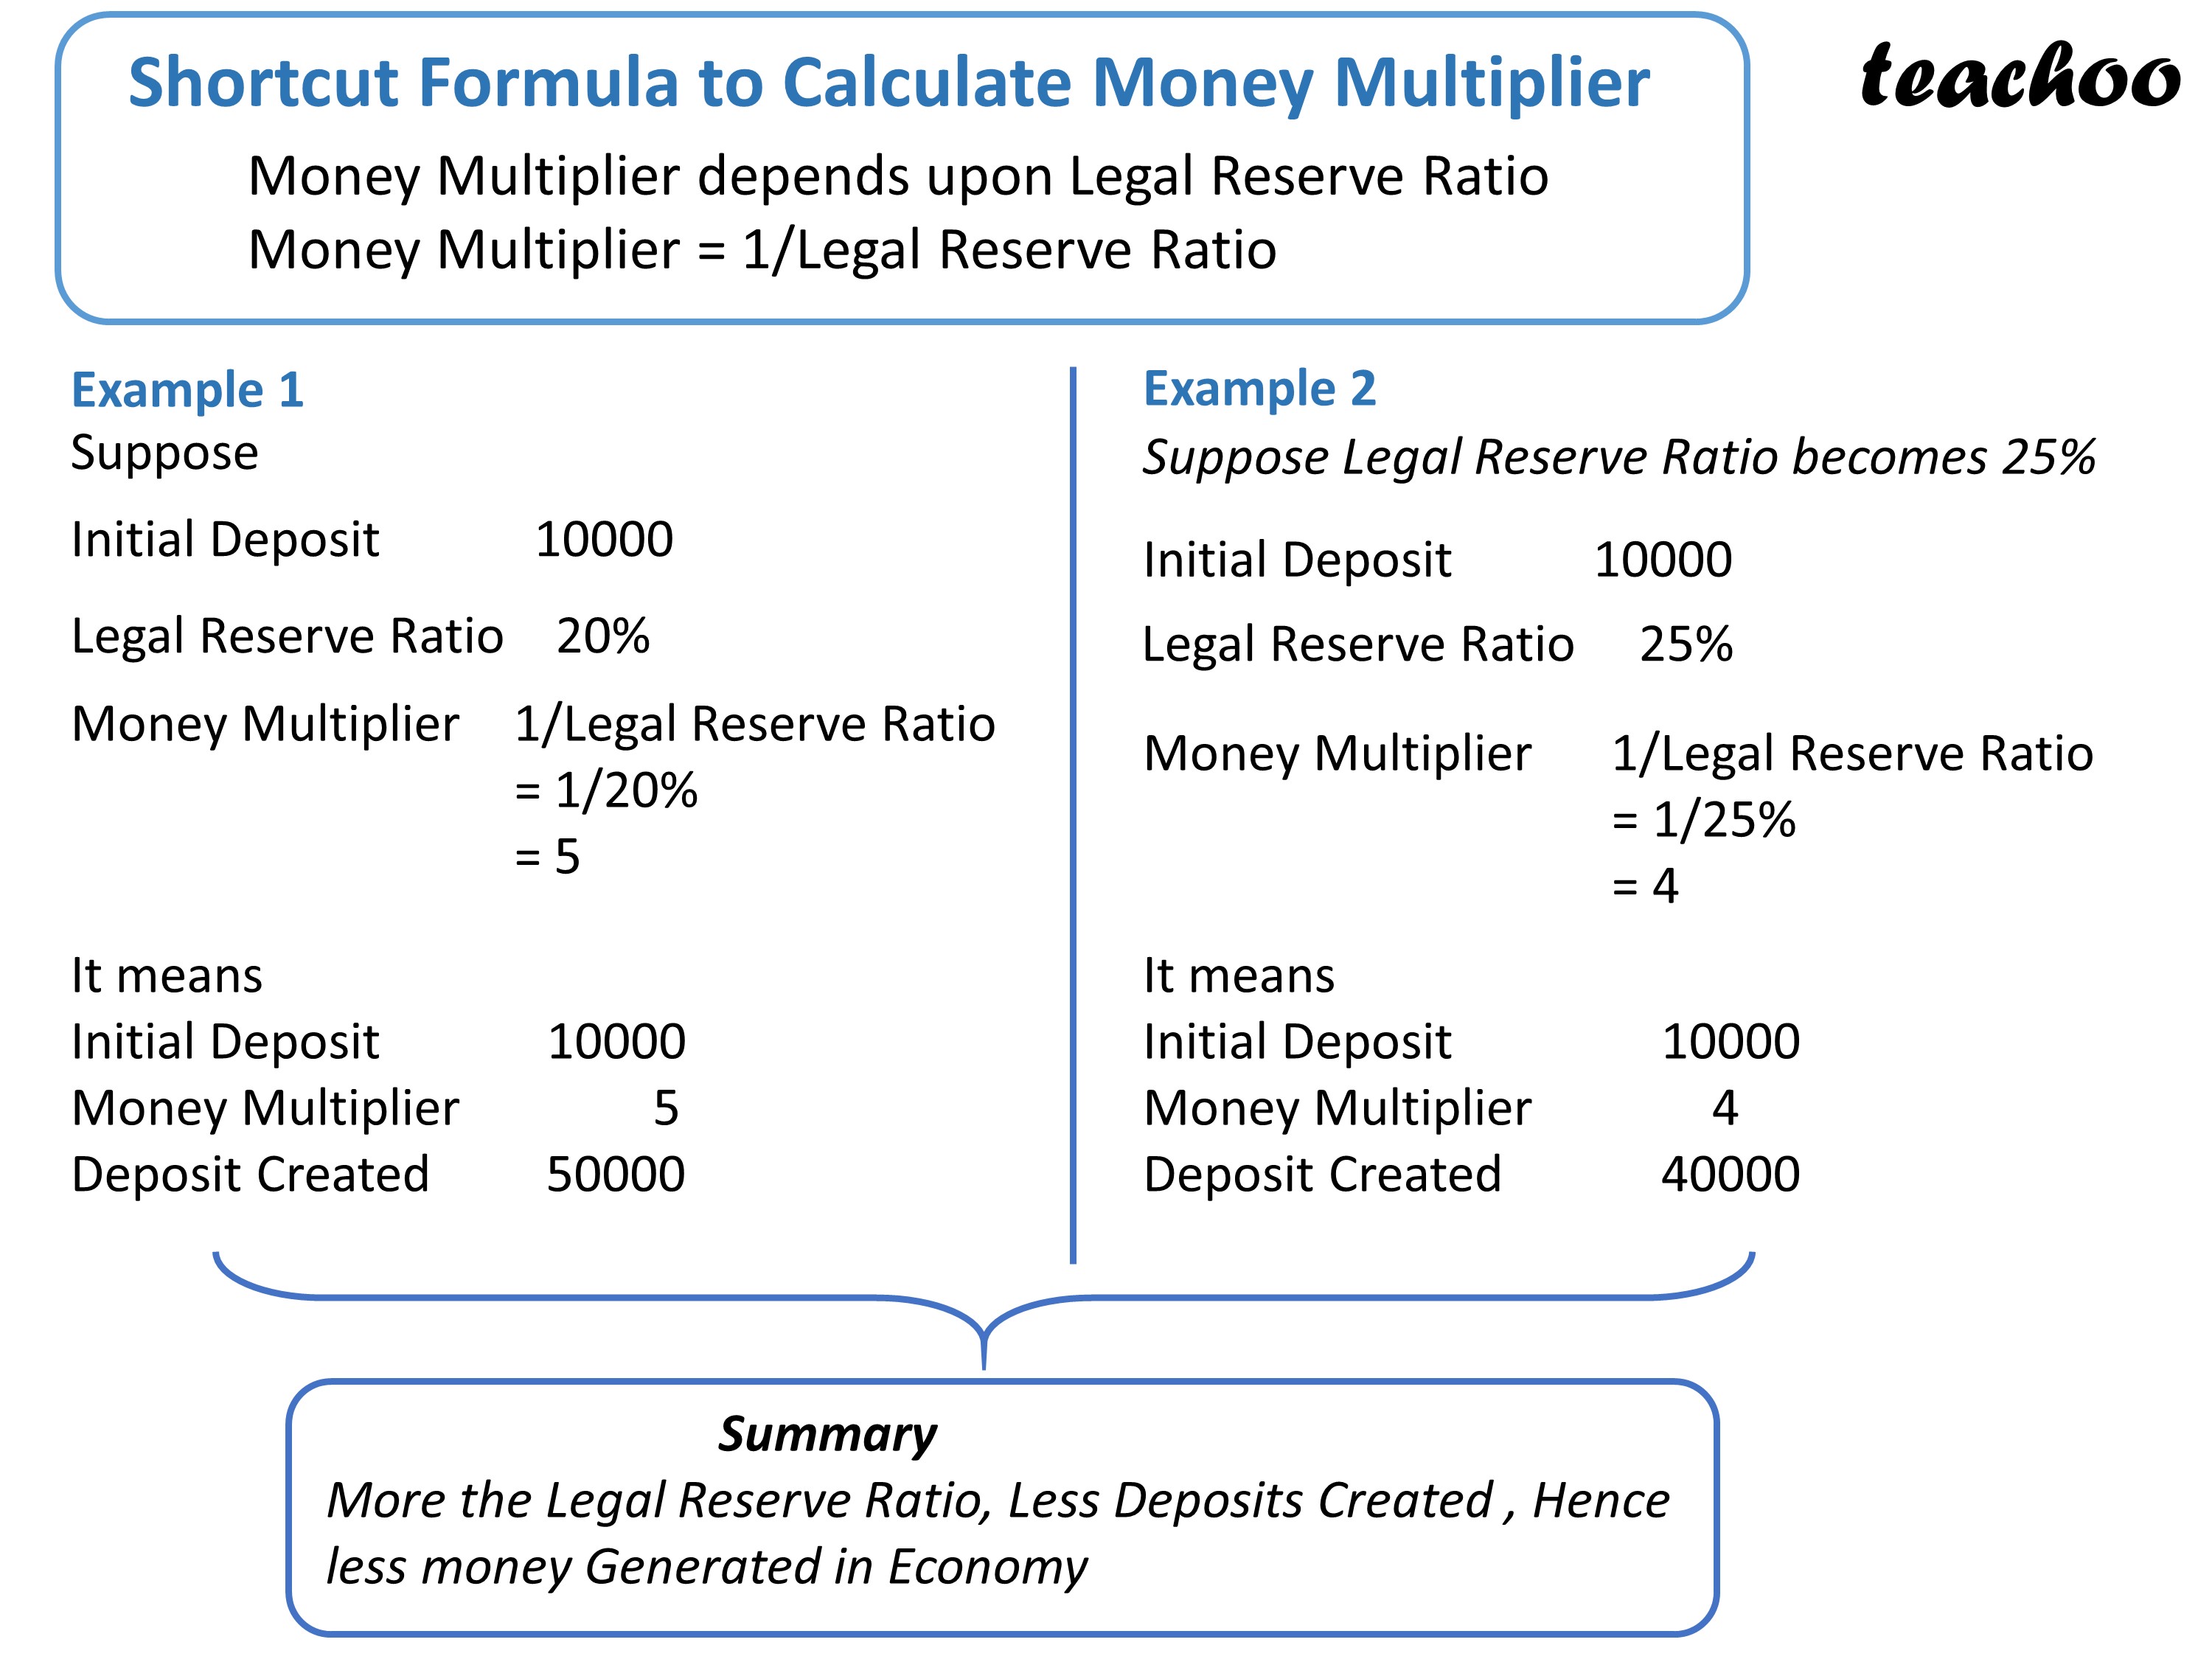
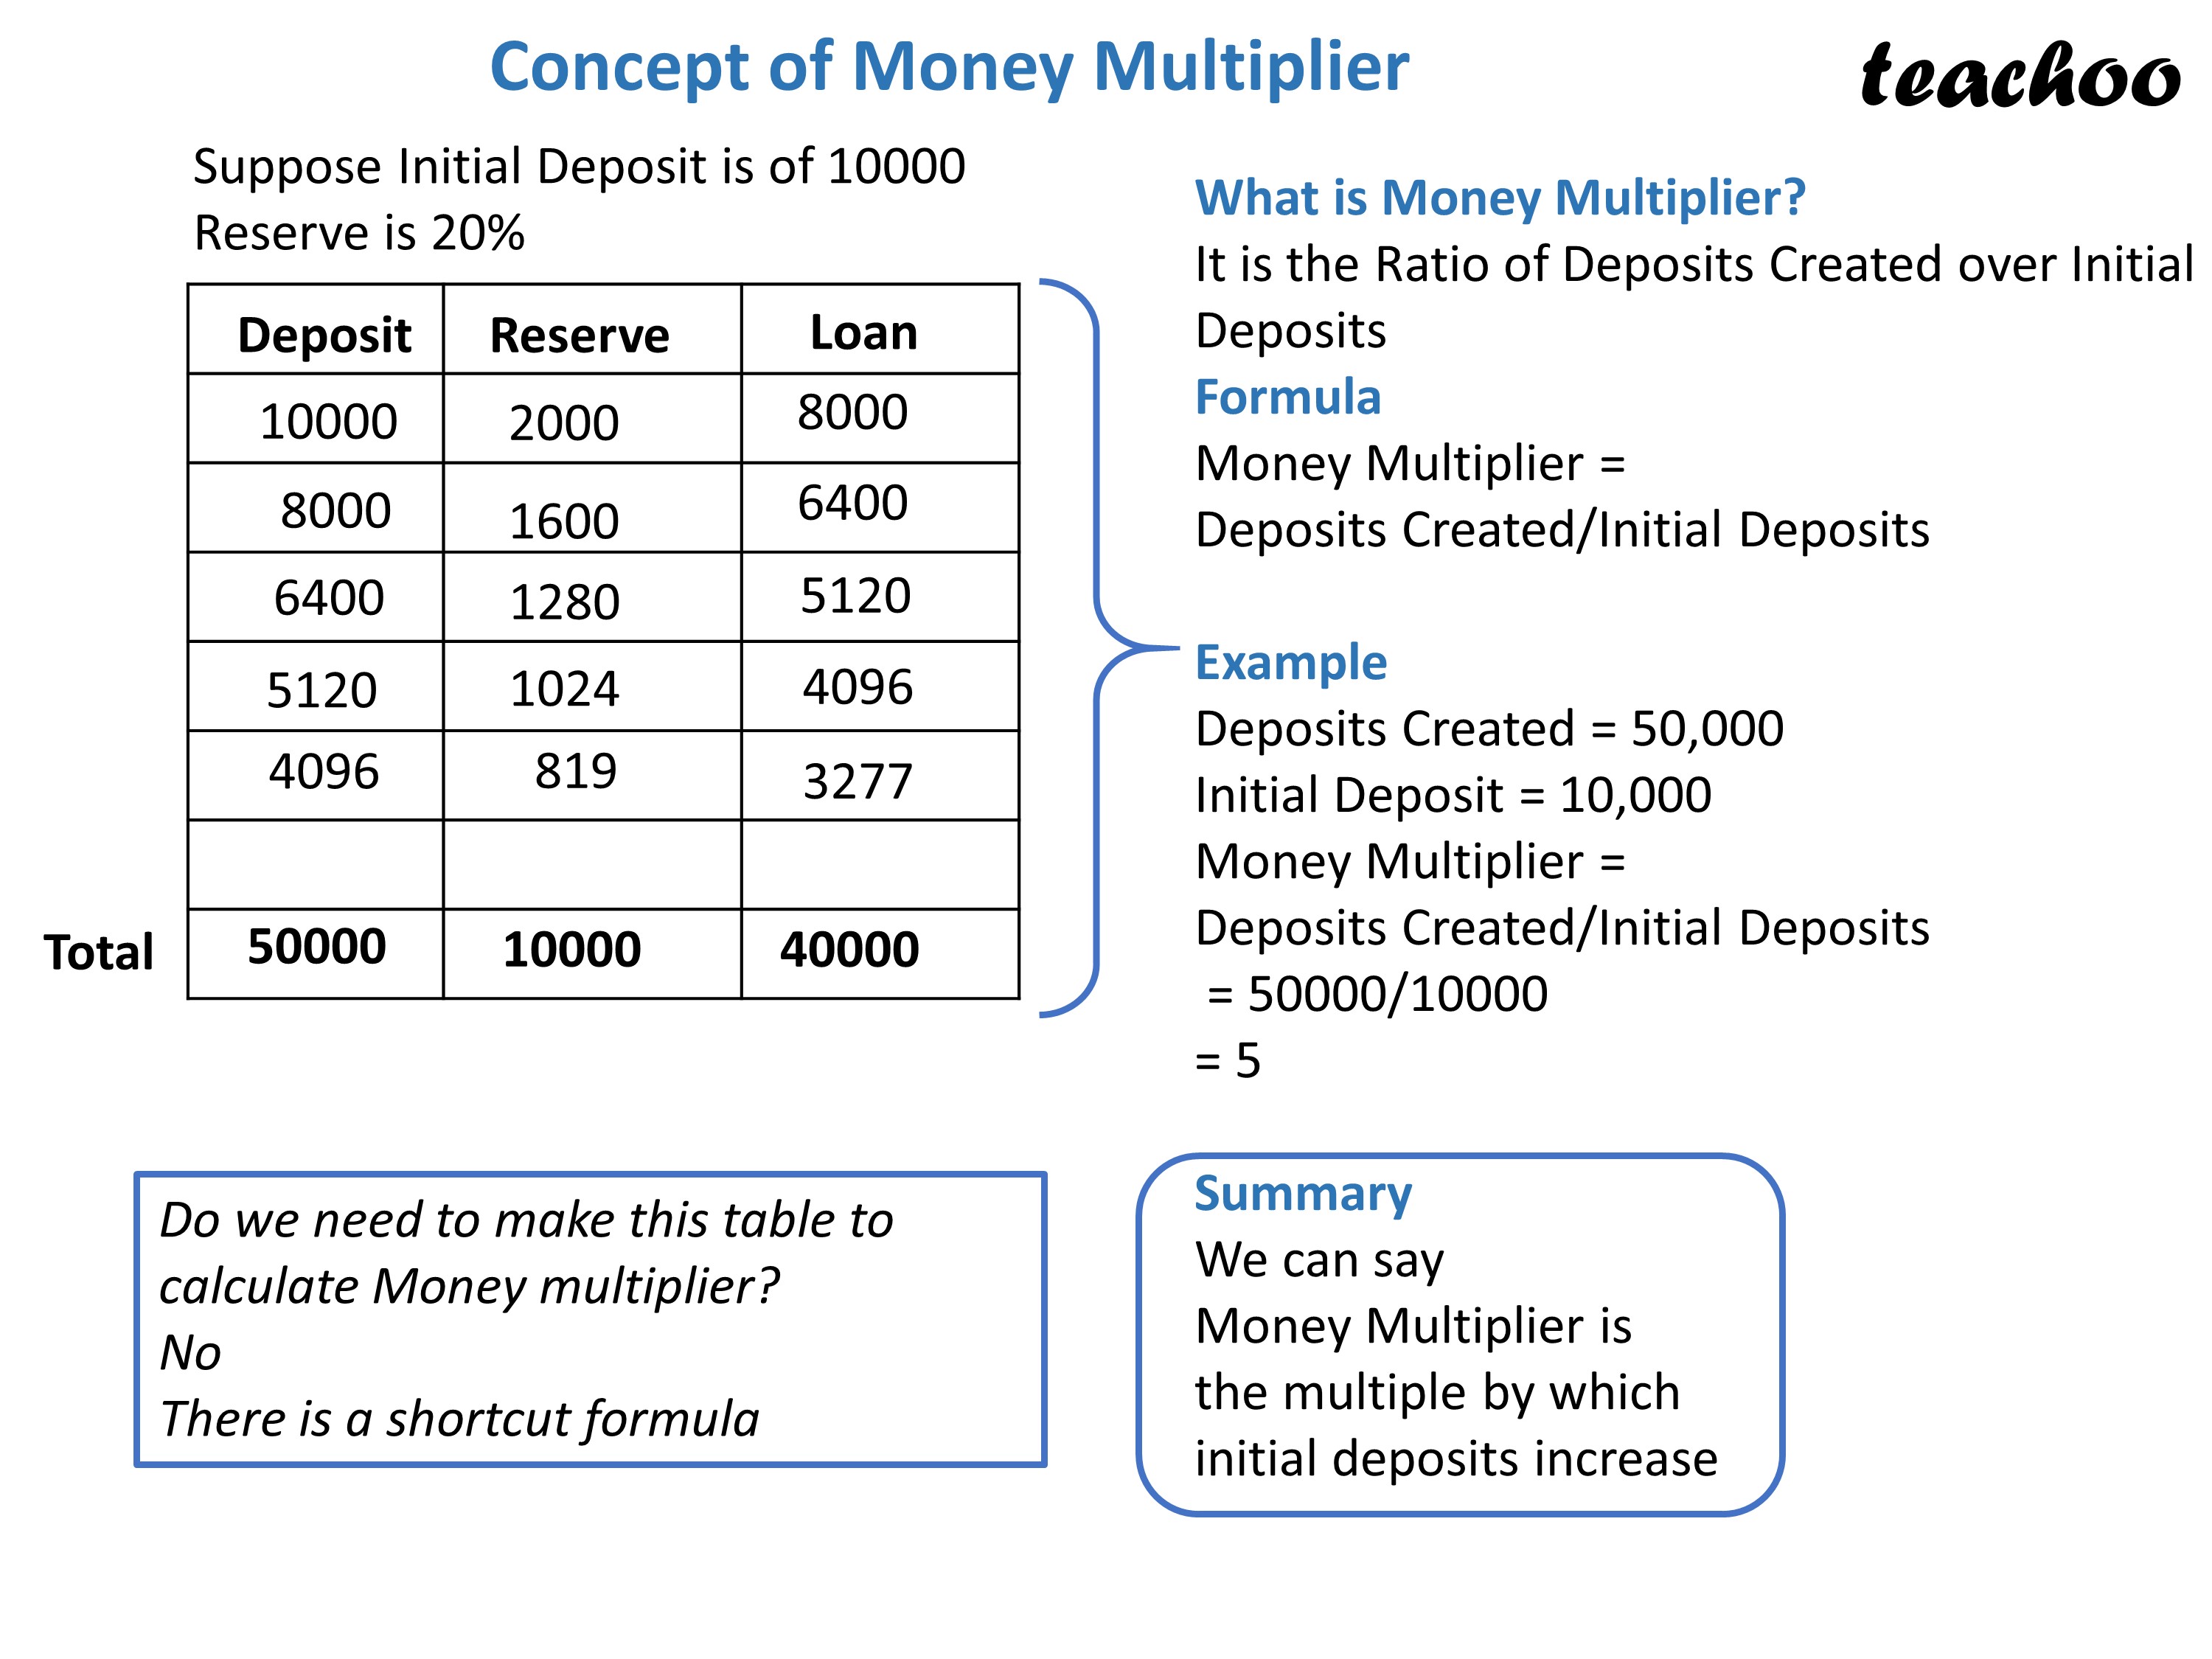
The money multiplier is just the reciprocal of the reserve requirement ratio. That is all there is to the basic definition. If the Fed sets a 10 percent requirement, the theoretical maximum multiplier is 10. If the requirement drops to 5 percent, it becomes 20. You divide 1 by the reserve ratio and that is your number. The problem is that nobody uses the simple version anymore, and anyone who presents it without caveats is either teaching an outdated course or trying to sound smarter than they are. Here is the straightforward calculation first, before I explain why it does not work the way textbooks say it should. Take the required reserve ratio and compute 1 divided by that ratio. So with a 0.10 reserve requirement, 1 / 0.10 = 10. That means for every dollar of reserves, the banking system can theoretically create up to ten dollars in checkable deposits. The formula you need to remember is M = 1 / rr, where M is the multiplier and rr is the reserve ratio expressed as a decimal. But then I ran into a situation in 2021 where a client was trying to model deposit expansion after the Fed slashed reserve requirements to zero in March of that year. The formula broke completely because you cannot divide by zero. The theoretical multiplier became infinite, which is obviously nonsense in the real world. I had to switch to using the actual monetary base and broad money supply data from the St. Louis Fed FRED database instead. I pulled series MBASE for the monetary base and M2SL for M2 money stock, then calculated the effective multiplier as M2 divided by the monetary base. That gave us a working number around 12 for early 2021, which reflected reality far better than any textbook formula could.
The reason the simple formula fails has to do with leakages. Banks do not lend out every dollar they receive beyond reserves. They hold excess reserves. They lend to people who cannot qualify. Borrowers spend some of that money and the rest sits in accounts that do not get re-lent at full speed. The Federal Reserve started paying interest on excess reserves in 2008, which fundamentally changed the dynamics. Banks decided they would rather earn risk-free interest from the Fed than chase marginally higher returns from lending. This means the actual multiplier in the U.S. has been drifting well below the theoretical maximum for a long time. Common mistake number one is confusing the required reserve ratio with the actual reserve ratio. The required ratio is what regulators mandate. The actual ratio includes whatever reserves banks voluntarily choose to hold on top. The true money creation process depends on the actual ratio, not the required one. I have seen people plug the 10 percent required ratio into the formula and claim the banking system can create ten dollars for every reserve dollar. That ignores excess reserves entirely and produces a number that has nothing to do with what is happening in the economy. Common mistake number two is assuming the multiplier works symmetrically. When someone deposits cash into a bank, reserves increase and the system can expand credit. But when someone pays down a loan, deposits shrink and money gets destroyed. The contraction side of the multiplier operates under the same mechanics but most people only think about the expansion side. This asymmetry matters during credit crunches. In 2008 and again in 2020, depositors pulled money out and banks tightened lending standards so aggressively that the multiplier collapsed faster than most economists predicted.
Here is the practical approach I use when I need a real number instead of a textbook fantasy. Grab the most recent weekly data for the monetary base from the Federal Reserve. Then grab the monthly M1 or M2 data from FRED. Divide the money supply figure by the monetary base figure. That gives you the actual money multiplier currently in effect. For M1 in mid-2024, the monetary base was roughly 3.4 trillion and M1 was around 18 trillion, putting the actual multiplier near 5.3. That is less than half of what the simple formula would predict if you used the effective required reserve ratio. If you want to calculate this yourself and track it over time, the simplest method is downloading the data from FRED as a CSV file and putting it into a spreadsheet. You do not need any special software. Column A for the monetary base series, column B for M1 or M2, column C for the formula =B/A. Drag it down and you get a time series of the actual multiplier. It takes about five minutes to set up once and then you can update it whenever you need current data. There are scenarios where the multiplier framework breaks down entirely. During quantitative easing programs, the Fed buys securities and credits bank reserves directly. The monetary base balloons while the money supply does not expand proportionally. The multiplier drops sharply not because banks are refusing to lend, but because the Fed is creating reserves outside the normal lending channel. Interpreting that drop as a sign that banks have lost confidence in borrowers is a category error. The reserves are being created for a different purpose than the multiplier model assumes.
Get the Full Details

Another limitation worth noting is that the simple multiplier assumes a constant reserve requirement and uniform lending behavior across all banks. In practice, large banks and small banks face different capital constraints, different deposit competition, and different regulatory scrutiny. Community banks with strong deposit relationships may lend at higher ratios than large nationwide banks under heightened compliance pressure. Aggregating everything into a single multiplier number smooths over these differences and can mislead you about where credit is actually expanding or contracting. If you are studying for an economics exam, memorize the basic formula and understand the derivation from the fractional reserve system. If you are trying to understand what is actually happening with money supply in the real economy, use the monetary base to broad money ratio instead. The textbook version is useful for building intuition about how banks create money through lending. The actual version is useful for anything involving policy analysis, forecasting, or making decisions based on monetary conditions. Knowing which one to use and when is the part that separates people who understand this from people who just memorized a formula.