Understanding VAT And GST Registration Numbers In Practice
VAT and GST registration numbers look like random strings of letters and digits, but they carry real weight. Every time a business files a tax return, issues an invoice, or passes through customs, that number is checked against government databases. Get it wrong and you face delayed payments, rejected claims, or worse, compliance audits. I have spent years dealing with cross-border invoicing across EU and Asian markets, and the number one thing that causes headaches is misunderstanding how these identifiers work from one jurisdiction to the next. A VAT registration number is a unique identifier issued by a country's tax authority to a business registered for Value Added Tax. A GST registration number serves essentially the same purpose under the Goods and Services Tax regime. Different countries use different naming conventions, different digit lengths, and different validation algorithms. Some nations use them strictly for domestic supply chains. Others require them for every international transaction above a certain threshold. The system is not unified, and assuming it works the same way everywhere will cost you time and money.
Unlock The Power Of Vat And Gst Registration Numbers Your Ultimate Guide
This guide covers what those numbers actually mean, how to validate them properly, and the practical steps you need to take before you put one on an invoice or pass it to a payment processor. It is not a legal document. Tax law changes every year and differs by jurisdiction. But the mechanics of verification and the common failure points are largely the same everywhere, and knowing them will save you from the obvious mistakes. I ran into a specific problem last year while reconciling invoices for a client operating in Belgium and Brazil. The Belgian VAT number format looked correct by standard European validation rules, but the Brazilian CNPJ attached to the same transaction was malformed. I had assumed the Belgian number was sufficient proof of registration because both countries are OECD members. It was not. The Belgian VAT number passed EU VIES validation, but the Brazilian tax authority rejected the cross-border credit claim because the CNPJ did not match the declared company name on file. The workaround was straightforward but tedious: I pulled the official registration certificate directly from the Belgian tax portal and the Brazilian Receita Federal database, compared the legal entity names character by character, and submitted a corrected invoice with the properly verified numbers. That took three days and two rounds of correspondence with the client's finance team. Getting it right the first time would have saved all of that.
How Registration Numbers Are Structured
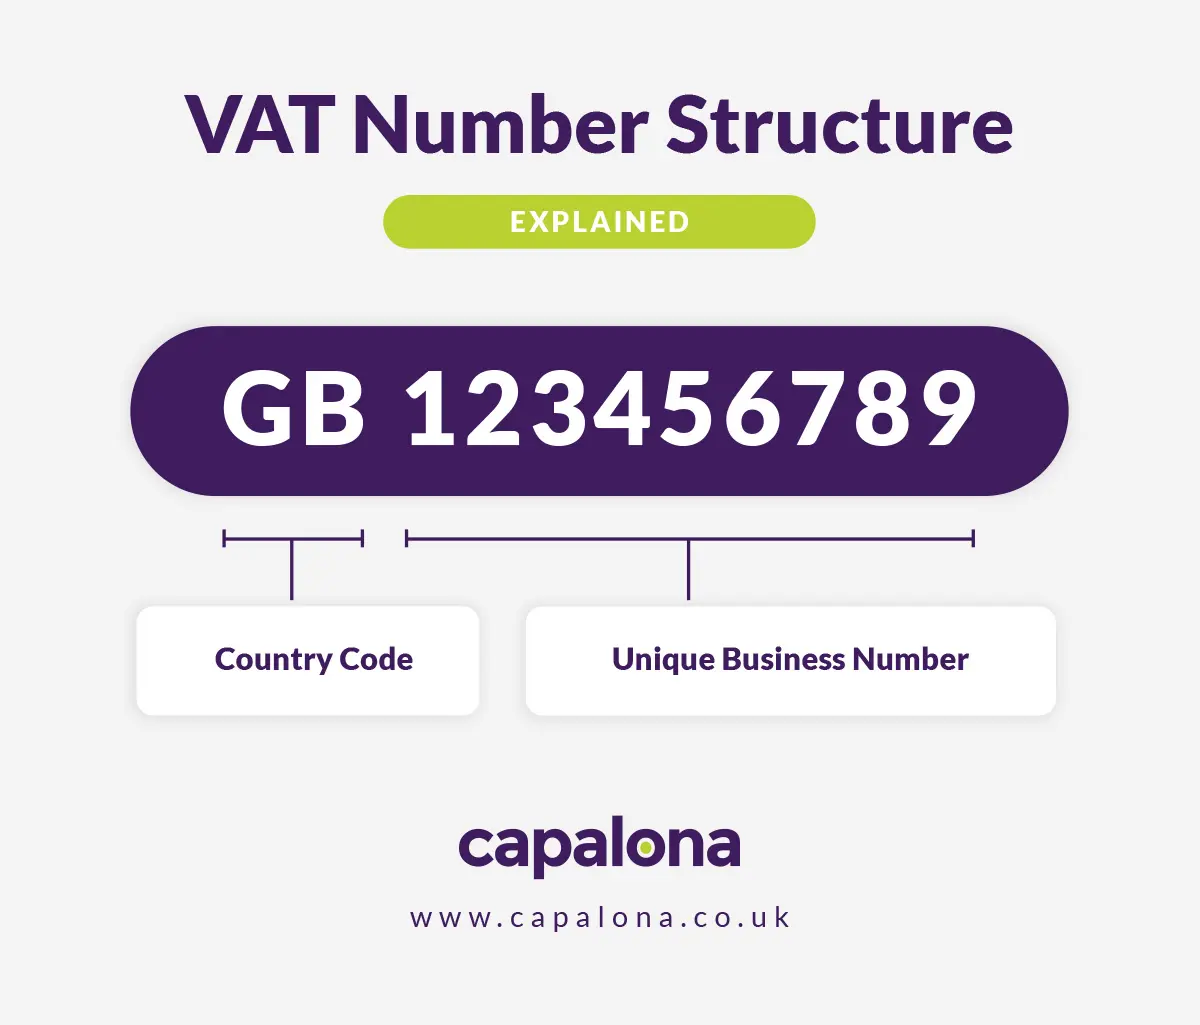
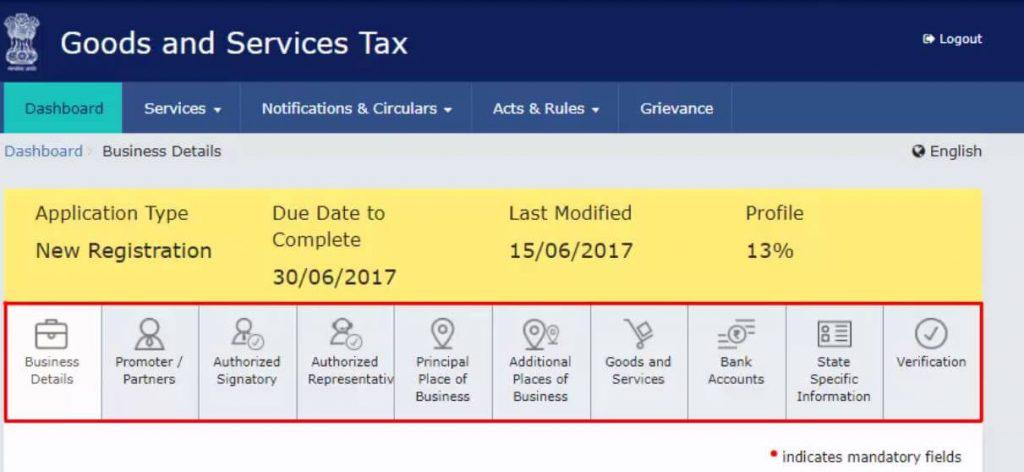
Most VAT and GST numbers follow a predictable pattern, but the pattern is not universal. The European Union uses the format XX followed by digits, where XX is the country code. Germany is DE plus nine digits. France is FR plus two check digits then nine digits. Italy is IT plus eleven characters that mix letters and numbers in a specific algorithm. The UK uses GB plus nine digits. These country codes matter because validation tools rely on them to route requests to the correct national system. Countries outside the EU do not always follow this convention. India uses a fifteen-digit GSTIN that encodes the state code, the PAN number of the entity, an registration sequence number, a Z character, and a check digit. Australia uses an eleven-digit ABN prefixed with the letters AUD in some international contexts. Canada uses a nine-digit CRA business number with a rational account suffix. Singapore uses a ten-digit UEN. New Zealand uses an eleven-digit IRD number. Each of these has its own validation checksum or requires an API lookup against a government database. Treating them all as interchangeable is a mistake that leads to rejected filings. One thing most beginners miss is that a registration number is not always the same as a tax identification number. In some jurisdictions, a business may hold a general TIN for income tax purposes and a separate VAT/GST number for consumption tax purposes. In others, they are the same identifier. In the US, there is no federal VAT or GST system, but businesses may register for state-level sales tax, and those registration numbers vary by state with no centralized validation portal. If you are dealing with US vendors, you often have to accept their self-reported number and verify it through the state's revenue department website individually.
Get the Full Details

Why Validation Matters More Than You Think
Writing a VAT number on an invoice without verifying it sounds like a minor administrative step. It is not. The consequences scale with the size of your transactions. If you are claiming input tax credits on purchases from a supplier whose VAT number is inactive or belongs to a different legal entity, the tax authority can disallow the entire credit and apply penalties. I have seen cases where a company deducted ten percent of its purchase value in input credits only to have it reversed three years later during an audit because the supplier's VAT registration had been suspended mid-year and nobody noticed. Validation is also critical for reverse charge mechanisms. In the EU, when a business in one member state purchases services from a business in another member state, the recipient accounts for VAT under the reverse charge procedure. This only applies if both parties hold valid VAT numbers. If you accept an invalid or expired number and apply reverse charge, you are effectively treating a domestic supply as an intra-community supply, which is a compliance violation. The burden of proof sits with the recipient, not the supplier. You need to know this before you process the payment, not after the tax office sends you a notice. There is a useful technical detail that people often overlook. The EU VIES system, which validates VAT numbers across member states, does not return real-time data for every country with perfect accuracy. It is generally reliable for large member states like Germany, France, and the Netherlands. For smaller jurisdictions or for numbers that have been recently issued or cancelled, VIES may return a result that does not reflect the current status. I learned this the hard way when a Polish VAT number validated successfully on VIES but the invoice was later rejected by our German tax advisor because the number had been deregistered the previous month and the cache had not refreshed. The fix was to cross-reference with the Polish tax authority's own online validation tool, which showed the deregistration date immediately.
How To Validate A Registration Number Step By Step
The first step is always to identify the country code embedded in the number or provided separately on the invoice. Do not guess. If a supplier gives you a number without a country prefix and says they are German, ask for the full registered number with the DE prefix. Many validation errors come from mismatched or missing country codes. Next, use the appropriate validation channel. For EU VAT numbers, the VIES portal at ec.europa.eu/taxation_customs/vies is the standard tool. It is free, requires no account, and returns one of three responses: valid, invalid, or error. The error response means the system could not reach the national database at that moment, usually due to a temporary outage or a request limit. Do not treat an error response as confirmation. If you get an error, wait and retry, or fall back to the national authority's own portal. For non-EU jurisdictions, there is no single centralized system. India has the GST portal at gst.gov.in with a search function. Australia has the ABN lookup at abn.business.gov.au. Canada has the CRA business number lookup tool. Each of these has different usability standards. Some require CAPTCHA or slow response times. Some only show whether a number exists without confirming the associated legal name. Plan for that gap when you are doing vendor onboarding.
When validating at scale, manual lookup is impractical. Businesses that process hundreds of invoices per month should implement automated validation through an API. There are several commercial providers that aggregate government validation endpoints and return structured responses. The cost is usually a few cents per validation call. The time savings are significant. One of my clients moved from manual VIES checks to an API integration and cut their invoice processing time from about forty-five minutes per batch to roughly eight minutes. The API also provided historical status tracking, which caught three suppliers whose VAT numbers had been cancelled in the previous quarter before they paid out any invoices.
Common Pitfalls And What They Look Like In Real Life
The most common mistake is assuming a valid format equals a valid registration. A number can match the structural pattern for a country and still be unregistered or deregistered. Format validation is a first filter, not a final check. Always run a live validation against the official source. Another frequent issue is the mismatch between the registered entity name and the invoicing entity name. This happens often with group structures where one VAT number covers multiple trading names or subsidiaries share a parent registration. A number might be valid but attached to a company called Alpha Holdings Ltd while the invoice comes from Beta Services Ltd. The VAT numbers could belong to the same group, but the tax authority will not automatically accept that connection. You need documentary proof, usually a group VAT registration certificate, to support the link. There is also the problem of temporary registration numbers. Some jurisdictions issue provisional VAT numbers during the application process. These are valid for a limited period and may not appear in public validation systems until full registration is complete. If you receive a provisional number, ask for the expected full registration date and set a reminder to revalidate before your next filing deadline. I once accepted a provisional Italian P.IVA number for a supplier and processed a €40,000 invoice with reverse charge. Six weeks later the provisional status was converted to a full registration with a different number sequence. The original invoice needed correction and resubmission, which triggered a delay in our input tax recovery for that quarter.
Orphaned numbers are another edge case worth noting. When a business closes or transfers operations, the VAT number may remain in the system for a grace period before being fully deactivated. During that window, validation may still return a valid result even though the number is no longer active for new transactions. This is rare but it happens, and the only reliable defense is to combine number validation with a broader supplier due diligence check that includes recent filing history and operational status.
What To Do When A Number Fails Validation
If a VAT or GST number fails validation, do not assume the supplier is fraudulent. It is more often a data entry error, a recently issued number that has not propagated to validation systems, or a temporary technical issue. Contact the supplier and ask them to confirm the exact number as it appears on their registration certificate. Request a copy of the certificate if needed. In many cases the issue resolves within twenty-four hours once the correct number is identified. If the supplier cannot provide a valid number and insists they are registered, you need to decide whether to proceed based on risk tolerance. For small transactions, waiting a few days for revalidation may be acceptable. For large invoices or ongoing supplier relationships, consider requesting that the supplier self-declare the VAT amount on the invoice rather than relying on a partner's number, and consult your tax advisor on the implications. This is not a permanent solution, but it allows business to continue while the underlying issue is resolved. In the case of cross-border transactions where validation fails for reasons beyond your control, document everything. Save screenshots of the validation result, record the date and time of each attempt, and keep copies of all correspondence with the supplier. If a tax authority later questions the transaction, that documentation shows you exercised reasonable care, which matters significantly for penalty mitigation.
The Limits Of What These Numbers Can Tell You
A valid VAT or GST registration number confirms one thing: the entity is registered for consumption tax in the issuing jurisdiction at the time of validation. It does not confirm solvency, good standing on other tax obligations, or the accuracy of the information the entity has provided on other documents. A company can hold a valid VAT number while owing significant income tax arrears. In some jurisdictions, VAT registration and overall tax compliance are tracked in separate systems. This separation is a feature of how many tax administrations operate, not a bug, but it means your validation checks need to be layered if you want a complete picture. For high-risk suppliers or large transactions, consider supplementing number validation with a credit check or a review of public enforcement records. This takes additional time and usually involves a third-party service, but the cost is modest relative to the exposure. One supplier I worked with had a perfectly valid German VAT number and clean invoices for eighteen months. Then their credit rating deteriorated and they ceased trading. We had already issued several large payments before noticing the red flags because we were only checking the number, not the broader financial health of the entity. The lesson was expensive but clear. There is also the question of digital services and platform intermediaries. The EU's digital services tax rules and the UK's VAT digital services rules mean that platforms facilitating supplies between businesses and consumers sometimes bear the VAT liability rather than the individual supplier. In those cases, the VAT number on the invoice may belong to the platform, not the actual service provider. Understanding who the liable party is and ensuring the number matches that party is essential. I have seen situations where a freelancer providing design services through a marketplace had the marketplace's VAT number on their invoice instead of their own, leading to incorrect reverse charge treatment and a subsequent correction request from the tax authority.
Keeping Your Own Number Correct
If you are the one issuing invoices, your own VAT or GST number needs to be accurate and current on every document you send out. This sounds obvious but it is surprisingly easy to miss when a company restructures, merges, or obtains a new registration number after a name change. I had a client who changed its legal name and received a new VAT number but continued using the old number on invoices for four months. Several customers flagged the discrepancy, and two of them refused payment until a corrected invoice was issued. The time spent reconciling those errors far exceeded the time it would have taken to update the number in their billing system immediately. Set a calendar reminder to review your registration status at least twice a year. Check VIES or the relevant national portal and confirm the number is still listed as active. If you operate in multiple jurisdictions, maintain a register of all your registration numbers with issue dates, expiry dates if applicable, and the associated legal entity names. Update that register whenever anything changes. A simple spreadsheet with columns for jurisdiction, number, legal entity, registration date, and last validation date is enough. It takes about fifteen minutes to maintain and prevents a lot of downstream confusion.
Practical Templates And Checklists
When onboarding a new supplier or customer, use a standardized data collection form that captures the registration number, country, legal entity name, and registration date. Run validation immediately upon receipt and record the result with a timestamp. If validation fails, flag the record and do not proceed with the transaction until it is resolved. This simple workflow catches the majority of errors before they become problems. For invoice review, add a field that verifies the VAT number against the validation result before the invoice is approved for payment. If your accounting software supports custom fields or API integration, automate this step. If it does not, build a manual check into your approval process. The extra minute per invoice is negligible compared to the cost of a corrected invoice or a tax adjustment later. When preparing for a tax audit, have your validation records ready. Auditors commonly request evidence that you verified the supplier's VAT number at the time of purchase. Screenshots of validation results, API logs, or dated notes showing when and how you checked the number are all acceptable forms of evidence. Keep them for the required retention period, which varies by jurisdiction but is typically six to ten years.
When To Seek Professional Help
Most day-to-day validation work can be handled in-house with the tools available. But certain situations benefit from professional guidance. Cross-border transactions involving multiple jurisdictions, complex group structures with shared VAT registrations, transactions in jurisdictions with limited online validation resources, and cases where a valid number is paired with unusual payment terms or counterparty risk are all scenarios where a tax advisor or compliance specialist can add value. The cost of professional advice is usually small compared to the potential exposure from incorrect VAT treatment on significant transactions. I would recommend engaging a professional if you are dealing with transactions above a certain threshold, if your industry has specific VAT rules like construction or telecommunications, or if you are entering a new market where you are not familiar with the local registration system. Having someone review your processes and validate your approach early saves time and reduces the chance of costly corrections later. VAT and GST registration numbers are not just administrative details. They are the backbone of consumption tax compliance across jurisdictions. Understanding how they work, how to validate them properly, and where the system can fail will make your invoicing, payment processing, and tax filing smoother and more defensible. The effort required to get this right is modest. The cost of getting it wrong is not.

