Understanding Turnover Ratio Without the Fluff
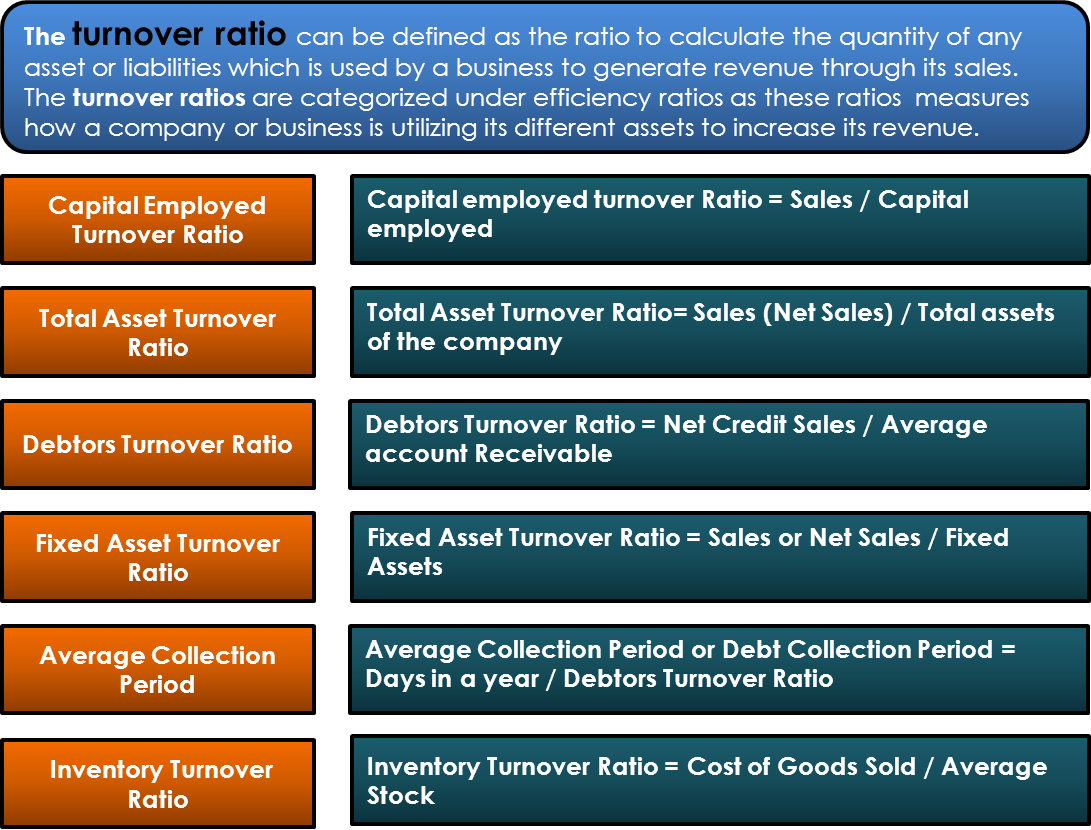
Turnover ratio measures how efficiently a company uses its assets to generate revenue. It is not a mystical concept. It is simply a division problem with financial data you can pull from a balance sheet and income statement. The most common versions are inventory turnover, accounts receivable turnover, and total asset turnover. Each tells you something different about the business. The calculation for inventory turnover is straightforward: divide cost of goods sold by average inventory. Average inventory means you take the beginning and ending inventory balances for the period, add them together, and divide by two. If your COGS is $500,000 and your average inventory is $100,000, the inventory turnover ratio is 5. That means the company sold and replaced its inventory five times during the period. For accounts receivable turnover, divide net credit sales by average accounts receivable. Total asset turnover divides net sales by average total assets. Simple arithmetic, but the interpretation is where people get tripped up. I used to work with a manufacturing client whose inventory turnover looked terrible on paper. The ratio was sitting at 1.8, which under normal circumstances would signal a serious problem. But when I dug into the data, I found they were holding specialized raw materials with a six-month lead time that couldn't be reordered quickly. The low turnover wasn't mismanagement. It was strategic buffer stock for items with long procurement cycles. The workaround was to segment the inventory into fast-moving and slow-moving categories and calculate separate turnover ratios for each. The fast-moving inventory was turning at 12x per year. The whole picture changed when I stopped looking at the aggregate number.
There are nuances that textbooks rarely cover. A higher turnover ratio is not always better. If a company's inventory turnover is extremely high, it could mean they are constantly running out of stock and missing sales opportunities. Conversely, a lower turnover might indicate overstocking, obsolescence risk, or poor demand forecasting. The same logic applies to accounts receivable turnover. A very high AR turnover means you are collecting quickly, which is generally good for cash flow. But if it is too high, you might be being overly aggressive with credit terms and losing customers to competitors who offer more flexible payment options. Total asset turnover is the broadest measure and the one I rely on most when doing quick screening comparisons across companies in the same industry. A retail business typically has a higher total asset turnover than a utility company because retail generates more revenue relative to its asset base. Comparing turnover ratios across industries is meaningless. A ratio of 2.0 is excellent for a capital-intensive manufacturer and terrible for a software company. One practical tip that saves time: when you calculate average inventory or average receivables, use monthly balances instead of just beginning and ending figures if the data is available. Seasonal businesses in particular can have wildly different figures at the start and end of a period. Using only two data points can distort the ratio significantly. I once saw a seasonal retailer's turnover ratio swing from 4.2 to 7.8 purely because I used the wrong periods for the average. Switching to quarterly averages brought it down to a realistic 5.4.
The biggest limitation of turnover ratios is that they do not account for the quality of assets. A company could report high inventory turnover while holding heavily depreciated or obsolete stock that barely moves. The number looks good but the reality is different. Always cross-reference with other metrics like gross margin percentage, days sales outstanding, and working capital trends. Turnover ratio alone will not give you a complete picture of operational efficiency. It is one data point among many, and treating it as a standalone decision tool is how bad acquisitions happen. If you want to dig deeper, the methodology is consistent regardless of the software you use. Export the relevant line items from your financial statements, plug them into the formula, and compare the result against historical periods and peer companies. The hard part is never the calculation. It is knowing what the number actually means in context.
Get the Full Details