How Sports Media Actually Works Right Now
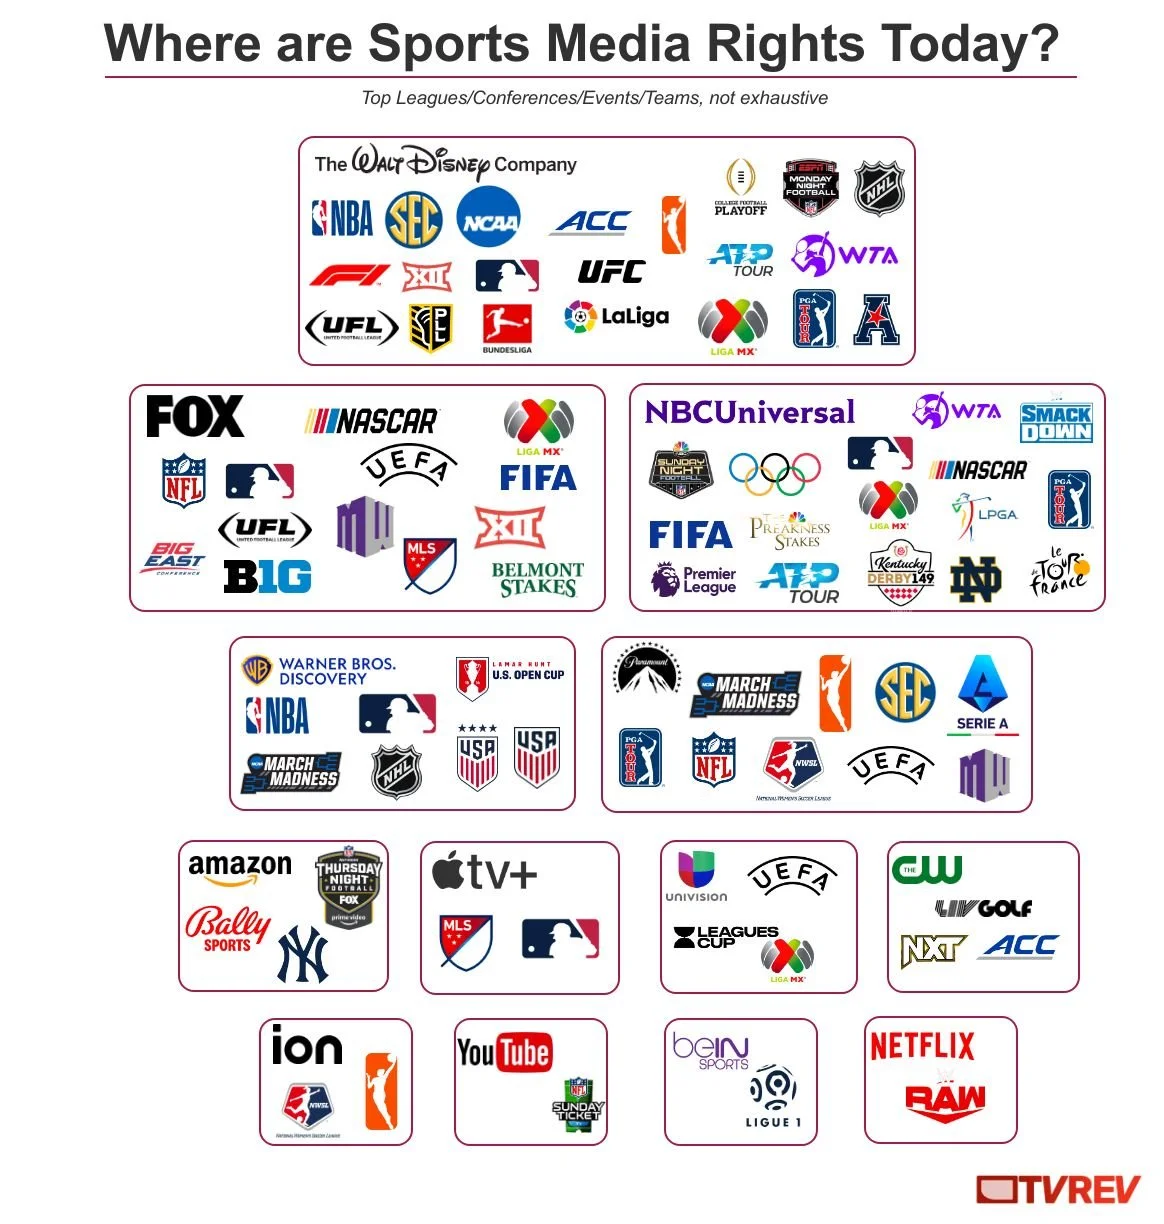
Most people watching sports media from the outside think it is about big broadcasts and famous commentators. It is not. It is about rights, distribution deals, and who controls the window between a game happening and you seeing it on a screen. If you are trying to get into this space or just understand who moves the money, the landscape has shifted enough in the last five years that old playbooks are mostly useless. The companies that matter fall into three buckets: owners of content rights, platforms that deliver that content to viewers, and data/tech companies that sit underneath both and make everything searchable, measurable, and monetizable. The lines between these categories blur constantly because the same few organizations sit in two or all three at once. Walt Disney Company is one of the biggest content owners in the game right now through ESPN and its broader portfolio. They hold rights to the NCAA tournament through a long-term deal, major league packages, and the SEC conference rights. Their leverage comes from bundling linear ESPN with Disney+ and Hulu. That bundle is what makes their rights payments defensible when sports advertising softens.
Comcast through NBCUniversal runs a similar playbook on the cable side with Peacock and the NBC Sports networks. They hold Premier League rights in the United States, Olympic Games through 2032, and major NFL packages. What people miss about Comcast is how aggressively they have moved toward direct-to-consumer options while still protecting their cable infrastructure. The Peacock deal for Sunday Night Football is the clearest example of that strategy in action. Amazon changed the pricing model for live sports streaming when they took Thursday Night Football to Prime Video. Their approach is different from Disney and Comcast because they do not need advertising revenue from sports to make the numbers work. They use sports as a retention tool for Prime subscriptions. That means they can pay more per right than a traditional broadcaster would justify on ad revenue alone. This distorts the market in ways most people do not track. Warner Bros. Discovery owns TNT, TBS, and the new B/R Sport integration. Their WarnerMedia assets gave them NBA, MLB, and Champions League rights. The merger created some awkward overlap and rights fragmentation, which is why you have seen them shuffle packages around. They are still a top player because linear sports channels generate cash flow that funds their streaming bet with Max.
Uber and Coca-Cola are not sports media companies in the traditional sense, but they have inserted themselves into sports media rights through sponsorship and partnership structures that blur the line between marketing and content distribution. That is worth noting because the revenue stream is different.
Get the Full Details

The Distribution Layer You Actually Need to Understand
Rightsholders do not just sell to networks anymore. They sell to aggregators, MVPD distributors, and direct-to-consumer platforms simultaneously. The tricky part is that these channels conflict. A rightsholder might sell regional sports to a cable provider while also launching a streaming version. The streaming version then cannibalizes the cable base, which hurts the very deal that made the rights payment possible. I learned this the hard way when a mid-market rightsholder I consulted with tried to launch a standalone streaming app for their conference. They priced it at seven dollars a month, assuming volume would make up for the low price. It did not. They had not accounted for the fact that their regional sports network already carried the games for most fans inside the territory. The streaming app competed with their own linear partner instead of finding new viewers. I recommended they pause the standalone app and instead license the content exclusively to one existing platform with better discoverability. That cut their development and marketing spend by roughly sixty percent and kept them in their linear partner's good grubs. Losing that partner would have killed their next rights renewal.
Data and Measurement Companies
Sportradar, Stats Perform, and Genius Sports operate in the data layer. They collect play-by-play data, biometric information, and betting-related metrics. They sell that data to broadcasters, sportsbooks, and fantasy platforms. This is not optional infrastructure. Without Sportradar feeding odds and live data to sportsbooks, the entire regulated sports betting market in the United States would stall within hours of a game starting. Dolby Laboratories and Dolby Atmos have become relevant here too because broadcast quality matters more as viewers upgrade to high-end home theater systems. It is a small niche but it affects how premium rights holders position their presentation packages.
The Streaming Disruption Is Real
The shift from cable to streaming has not flattened out. It is still happening. YouTube TV, Fubo, DIRECTV STREAM, and Sling remain important MVPD alternatives that rightsholders bundle into their carriage deals. But the bigger story is what Amazon and Apple have done. Apple bought Thursday Night Baseball and is building a sports ecosystem around Prime Video with original programming, not just live games. That is a different model than traditional sports media and it pressures every other player to justify their subscription cost beyond just live events. Audacy used to be Enterprise Audio and still runs a major sports radio network. It is a reminder that radio is not dead in sports. It is smaller and more regional, but it still reaches millions of listeners who consume sports audio during commutes and work. The economics are completely different from television, though. Local affiliate stations drive most of the revenue rather than national advertising.
Common Mistakes People Make Entering This Space
The biggest mistake I see is assuming that having content is the same as having a business. Rights are expensive. The average mid-tier sports property pays twenty to forty million dollars annually for a single regional package. If you do not have a distribution channel that reaches enough eyeballs to justify that spend, you are funding a luxury, not a business. Another mistake is ignoring the secondary market. Highlights, short-form clips, and social distribution drive more awareness than full games for younger audiences. TikTok, Instagram Reels, and YouTube Shorts have become de facto sports media platforms for demographics that will never subscribe to a traditional sports network. If your rights deal does not account for short-form distribution, you are leaving money on the table and ceding influence to platforms that do not pay you anything. There is also the issue of blackout restrictions. These are still a thing. MLB, NFL, and NHL blackouts prevent local games from airing on national streams inside the home market. This frustrates cord-cutters and creates a weird two-tier viewing experience. Some rightsholders have started experimenting with relaxed blackout policies during pandemic-era testing. The trend is slowly moving toward fewer restrictions, but the league office still holds the lever and they are cautious about upsetting cable partners.
What Is Likely to Change Next
ESPN+ continues to be the most aggressive direct-to-consumer sports play from a legacy network. They bundle it with Disney and Hulu at a price point that undercuts most standalone streaming services. Their strategy is to make the bundle the default and let ESPN+ carry the sports-heavy users into the Disney ecosystem. It is working well enough that other networks are copying the bundle model. WWE on Netflix is the newest major move. It shows how non-traditional sports properties can now command Netflix-level distribution deals. This opens the door for WWE, UFC, and similar properties to negotiate from a position of strength rather than being dependent on traditional sports media companies. Betting integration will keep pushing sports media toward real-time data delivery. TheScore, FanDuel, and DraftKings have all built media arms that compete with traditional broadcasters for attention during games. They are not carrying full games, but their in-game graphics, odds feeds, and highlight recaps capture the attention of a segment that cable sports desks are struggling to reach.
If you are entering this space, pick a lane. Rights ownership, distribution technology, data services, or audience platform. Trying to be all four at once is how you run out of capital before you build anything real. The companies that are winning today are either massive diversified media conglomerates or highly specialized tech platforms that solve one problem extremely well.