How Ccflow Actually Works for Small Business Cash Flow
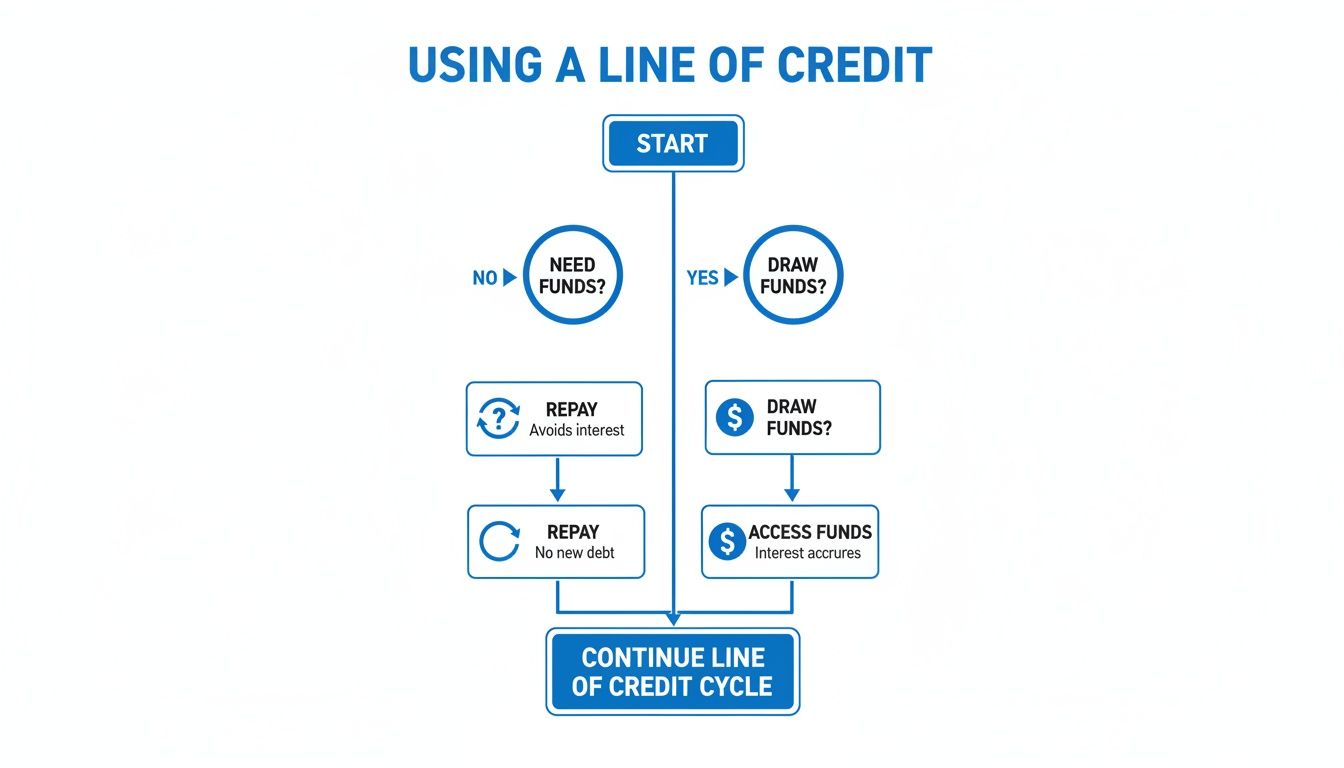
I spent about three years troubleshooting why my clients kept running into walls with their revolving credit facilities before I ever heard about Ccflow. The problem was never the credit itself. It was the timing gap between when you needed money and when your invoices actually got paid. Most businesses operate on 30 to 60 day payment terms but have to pay their people every two weeks. That mismatch is where everything falls apart. Ccflow is a line of credit product designed specifically for this mismatch. You apply once, get approved for a certain limit, and then draw from it whenever you need. You only pay interest on what you actually use. That's the basic pitch. Here's what actually happens when you're using it day to day. When you connect your business bank account to Ccflow, the platform monitors your daily balance. If your balance drops below a threshold you set, it can automatically trigger a draw from your credit line to cover the shortfall. This is called overdraft protection or automated liquidity management, depending on who you're talking to. The key thing nobody mentions upfront is that these automatic triggers can fire without any real-time notification. I learned this the hard way when a client of mine had a routine $40,000 payment hit their account on a Friday evening. The system pulled from their Ccflow line at 11:47 PM on Saturday. They found out on Monday morning when they were reviewing their statements. By then the draw was already sitting there accruing daily interest.
The workaround is simple but you have to set it up intentionally. Go into your Ccflow dashboard and disable auto-draw if you want full control. Then set up manual draws with a minimum draw amount that makes sense for your business. For most small businesses I work with, a minimum of $5,000 per draw is the sweet spot. Anything below that and the interest costs start eating into your margins faster than you'd expect. Here's the part that trips people up. Lines of credit like Ccflow typically have a commitment fee on the undrawn portion. So if you're approved for $100,000 but only draw $30,000, you're still paying a fee on that remaining $70,000. It's usually around 0.5% to 1% annually on the unused portion. That's not a lot in absolute terms but over a full year it adds up. I've seen businesses pay over $400 annually in commitment fees for credit lines they barely touched because they didn't understand the fee structure when they signed. Another thing that matters is the draw frequency. Some lenders limit how often you can draw from your line within a given period. Ccflow tends to be flexible here but you should verify your specific terms. I had a contractor who needed daily draws for about two weeks straight while waiting on a payroll tax deposit window. His initial agreement didn't clearly state whether daily draws would trigger a review of his credit line. They didn't review it in his case but he got anxiety every time he made a draw. The fix was getting a written amendment to his agreement that explicitly allowed unlimited draws during an agreed-upon period. It took ten minutes on a phone call but saved him weeks of stress.
The interest rates on Ccflow are variable, which means they move with the prime rate. Right now we're in a environment where rates have been elevated for a while. If you're pulling money from your line of credit during high-rate periods, the cost of borrowing is real. I do the math for my clients before they commit. Say you draw $25,000 at an 11% annual rate. That's about $229 in interest per month if you don't pay it down. If you pay it back in 30 days, you're looking at roughly $229 total. If it takes 90 days, you're looking at around $687. The difference between a two-week draw and a three-month draw on the same amount can be $500 or more. There's also the qualification side that deserves attention. Ccflow typically looks at your personal credit score, business credit score, revenue history, and sometimes even your accounts receivable aging. If your AR is overdue past 60 days, expect your approved limit to be lower than you'd like. I've seen businesses with solid revenue but messy invoicing get offers that were 40% below what they thought they'd qualify for. The fix isn't complicated. Clean up your aging report before you apply. Get those old invoices collected or written off. Make sure your books show consistent revenue rather than lumpy spikes that raise questions. One counter-intuitive thing about lines of credit is that paying them down too aggressively isn't always the right move. If you have excess cash and you pay off your Ccflow balance entirely, you free up your available credit but you also lose the liquidity cushion. I tell my clients to keep at least 25% of their approved line drawn at all times during normal operations. This ensures you have breathing room for emergencies and it also signals to the lender that you're using the facility responsibly. A completely paid-off line can sometimes trigger a review or even a reduction in your limit because the lender assumes you don't need it.
Get the Full Details

Here's what I wish more people understood about the repayment structure. Unlike a term loan where you have a fixed monthly payment, a line of credit typically requires minimum payments based on a percentage of your outstanding balance plus accrued interest. The exact percentage varies by lender but it's often around 2% to 3% of the outstanding principal each month. This means if you draw $50,000 and only make the minimum payment, your balance declines very slowly. The math is brutal when you sit down and calculate it. At a 2% minimum payment with an 11% interest rate, it could take you over three years to pay down $50,000 if you only made minimum payments and didn't add any new draws. That's not a prediction. That's the actual amortization schedule. So what should you do instead? Pay down the principal as fast as you can. Even an extra $500 per month beyond your minimum payment can cut your payoff time in half. I track this for my clients using a simple spreadsheet. We log every draw, every payment, and project the payoff date. When they see the difference between minimum-only payments and accelerated payments, most of them switch strategies immediately. The application process for Ccflow is mostly digital these days. You'll need your business tax ID, recent bank statements, profit and loss statements, and possibly your most recent balance sheet. The approval timeline ranges from same-day for simpler cases to two weeks for more complex applications. If you have multiple business entities or unusual revenue streams, plan on the longer end. One client of mine had a side business that accounted for 30% of his total revenue but wasn't reflected in his primary business's financials. The underwriter flagged it and asked for documentation. That added four days to his approval. I always tell clients to disclose everything upfront rather than risk a delay or denial later.
There are limitations you should know about. Ccflow is not a solution for long-term financing needs. If you're thinking about using a line of credit to fund equipment purchases or expansion projects, you're looking at the wrong product. Lines of credit are for short-term working capital gaps, not capital expenditure. Using a revolving credit line for a multi-year investment is one of the most expensive financial mistakes a small business owner can make. The interest compounds against you and the required payments keep shrinking your available credit when you might need it most. Another limitation is that not all businesses qualify. If you're a startup with less than a year of revenue history, or if you operate in certain regulated industries, you may not meet the threshold. Ccflow tends to favor established businesses with predictable cash flow patterns. Seasonal businesses can still qualify but expect your limit to be calibrated to your peak revenue months rather than your average. I had a landscaping company that made 70% of its revenue between April and September. Their approved limit was based on those summer months, which meant during January through March they had very little headroom available. They learned to plan their draws strategically around their seasonal cycle rather than treating the line like a permanent funding source. If Ccflow doesn't fit your situation, there are alternatives. A traditional business line of credit from a bank might offer lower rates but comes with stricter qualification criteria and slower funding. A merchant cash advance gives you fast cash but the effective annual percentage rate can exceed 40% in some cases. Revenue-based financing ties your payments to your monthly revenue, which can be a better fit if your income fluctuates significantly. Each option has trade-offs. The only way to know which one works is to run the numbers on your specific situation rather than picking the first product you find.
The bottom line is that Ccflow and similar line of credit products are tools, not solutions. They solve a specific problem: the gap between when money comes in and when you need to pay expenses. Used correctly, they prevent cash flow crises that force business owners to make desperate decisions. Used carelessly, they become expensive traps that compound financial stress instead of relieving it. The difference comes down to understanding the terms, monitoring your draws carefully, and paying down the balance faster than the minimum required. That's the practical reality of using a line of credit for cash flow management, and it's the same advice I give anyone sitting across from me whether they're asking about Ccflow or something else entirely.