Sam's Club Credit Card Realities
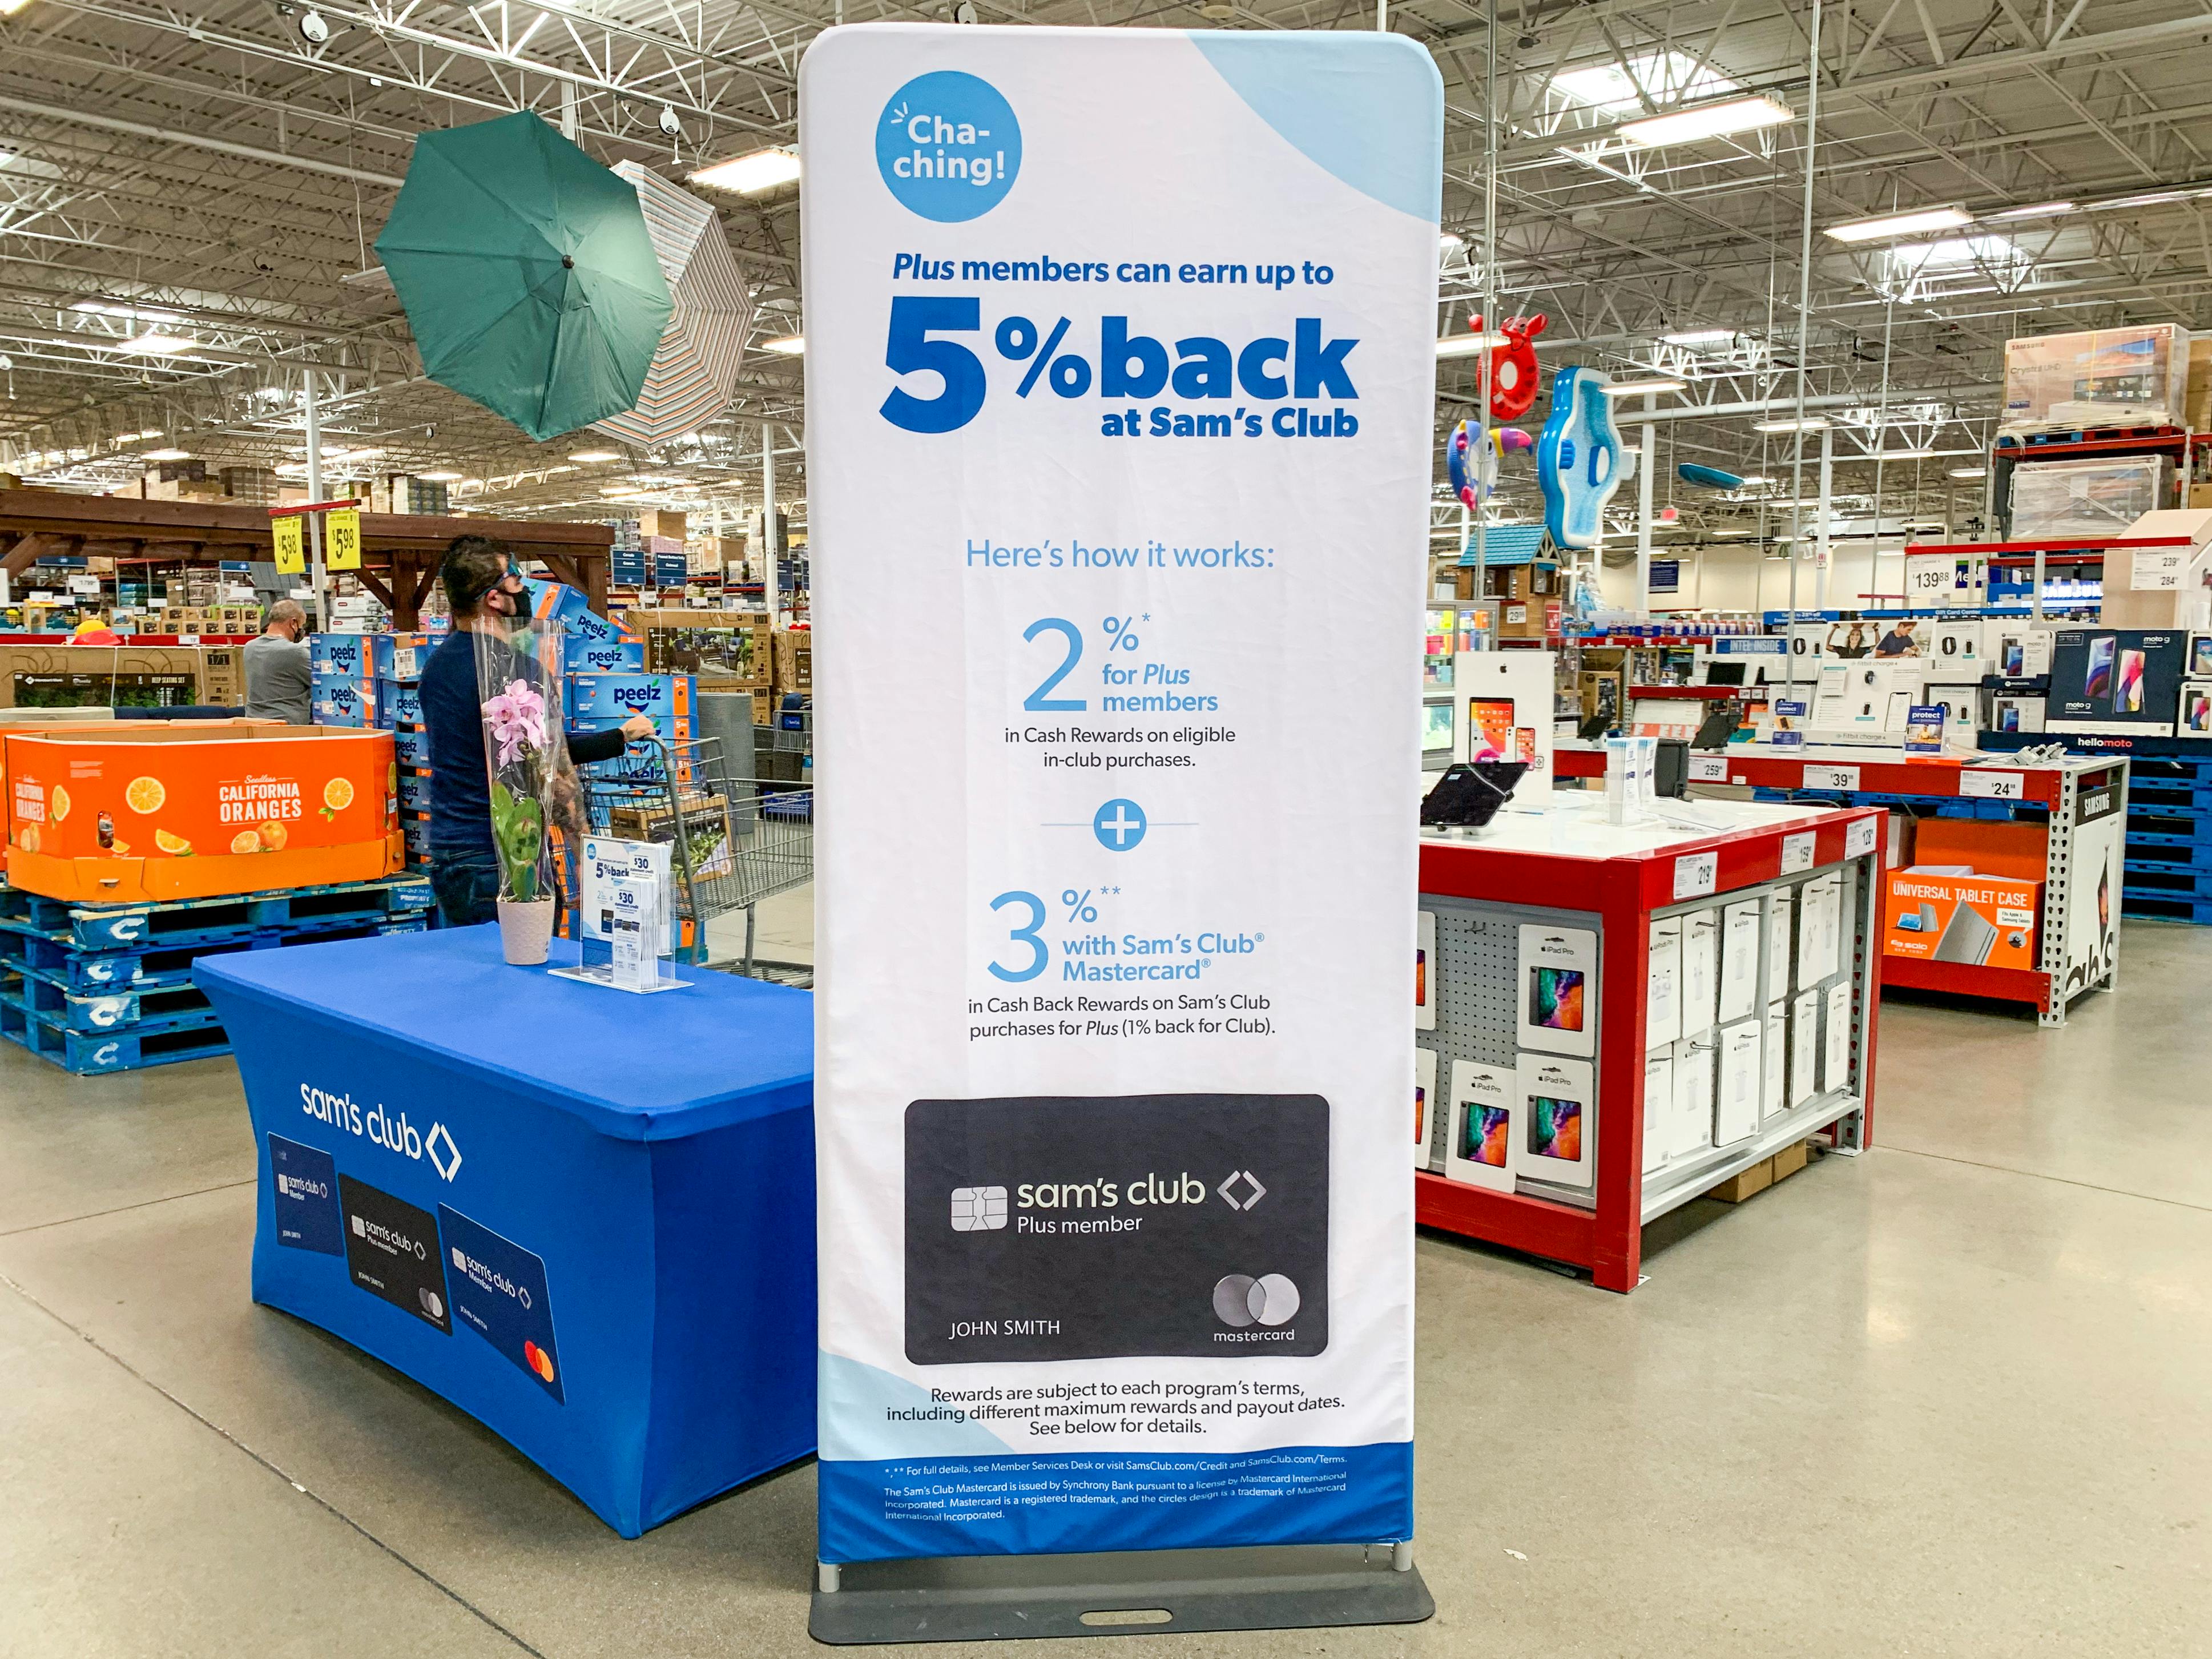
The Sam's Club Credit Card sits in the closed-loop rewards category, meaning it works differently than most travel or general cashback cards on the market. I learned this the hard way after assuming the earning structure worked like a standard Visa or Mastercard. It does not. This card is issued by Synchrony Bank and tied exclusively to Sam's Club purchases. You earn 5 percent cash back on eligible Sam's Club spending, 3 percent at gas stations, and 1 percent on everything else. The 5 percent rate is significantly higher than most store-branded cards offer for their primary category. It applies to in-club purchases, online orders at samsclub.com, and participating merchants through the payment network. The annual fee is zero dollars. That alone makes it worth having in your wallet if you shop at Sam's Club regularly. But the card has real structural limitations that most people overlook.
The biggest catch is that the 5 percent reward only goes toward a future Sam's Club purchase or a gift card. You cannot withdraw it to a bank account. I discovered this when I had about $200 in rewards sitting there and needed cash instead of merchandise. The portal only lets you apply the reward toward checkout or convert it to a physical gift card, which then carries the same restriction.
Who This Card Actually Makes Sense For
If you spend at least $1,500 per month at Sam's Club, the card pays for itself immediately. That is $75 in rewards monthly or roughly $900 annually at the top tier. For someone buying bulk groceries, baby supplies, or seasonal goods at Sam's Club, this card functions like a legitimate high-yield savings account for groceries instead. I ran into a specific edge case once that almost cost me. I had loaded my rewards balance during one checkout cycle and tried to use it alongside a same-day ad promotion at the register. The system applied the rewards to my cart, but the point-of-sale terminal rejected the transaction because the ad discount and the reward balance triggered a duplicate promo code conflict in Synchrony's backend. I walked away that day without the rewards applied. The fix was simple but unintuitive: pay with the card using rewards first, then come back later and re-enroll in any open promotional offers separately. Do not attempt to stack them in the same transaction.
Get the Full Details

Common Misunderstandings About This Card
Many people assume the 5 percent reward rate applies to all Sam's Club purchases equally. It does not. Certain categories are capped or excluded entirely. Prescription purchases do not earn rewards. Certain third-party services sold through Sam's Club, like travel bookings or photo services, fall under the 1 percent bucket instead of the 5 percent bucket. Tire installation and certain automotive services also earn at the lower rate. Another thing nobody mentions often enough: the rewards statement does not update in real time. There is typically a three to five business day lag between when you make a purchase and when the reward shows up. If you are trying to hit a specific reward threshold to unlock a purchase, plan for that delay or you will walk around with more spending power on paper than you actually have.
Interest Rates And Rewards Protection
The card carries a variable APR that runs well above average. Right now it sits in the low to mid twenties depending on your credit profile. If you carry a balance from month to month, the interest charges will almost certainly exceed whatever rewards you generate. A $500 monthly Sam's Club spend at 5 percent gives you $25 back. Carrying that $500 balance at 22 percent APR costs you roughly $9 per month in interest. You are losing money every month you do not pay the statement in full. I learned this the hard way in 2023. I was carrying a small balance from a timing issue where my paycheck came three days late. I thought the rewards wereing the interest. They were not. The math is straightforward but easy to ignore when you are focused on the 5 percent headline number.
Practical Steps To Maximize The Card
Pay the statement balance in full every month without exception. Set up autopay for the minimum amount at minimum, but aim to clear the full balance before the due date. Link the card to your Sam's Club online account so purchases at samsclub.com are tracked automatically and the rewards post correctly. Do not let the rewards sit idle for months at a time. Cash them out as gift cards and use them before any potential policy changes Synchrony might implement. If you do not shop at Sam's Club at least twice a month, consider whether this card is worth the clutter in your wallet. There are other options. The Walmart Rewards Card, for instance, operates on the same closed-loop model but gives you slightly different category breakdowns. If you shop at both retailers, you could theoretically run both, but managing two closed-loop cards with separate reward balances is usually more headache than it is worth unless you are pushing very high spend volumes.

When This Card Fails Completely
The card becomes a net negative if you shop at Sam's Club irregularly and tend to forget to pay the statement on time. Late payments trigger penalty APRs that can jump to 29.99 percent. They also reduce your available credit instantly and can damage your credit score enough to disqualify you from better products later. If you have a history of carrying balances, get a different card or skip this one entirely. A standard no-annual-fee cashback card like the Citi Double Cash or the Wells Fargo Active Cash actually earns you more usable rewards because you can put that money toward rent, bills, or savings. The Sam's Club card is a narrow tool for a specific shopping habit. It is not a general-purpose credit card replacement. Know what it is before you apply.