Getting Your Loan Sorted Without Losing Your Mind
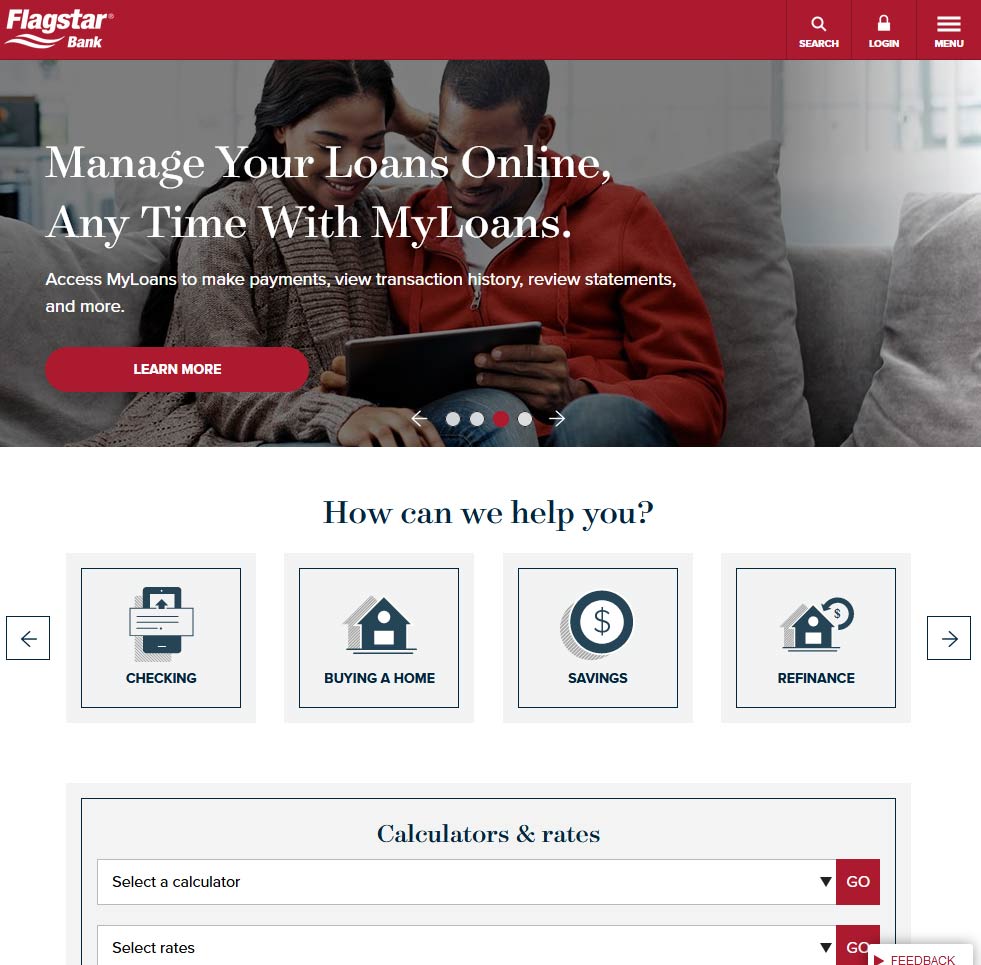
Flagstar MyLoans is their digital portal for managing mortgages and home equity products. I've been working in mortgage operations for over a decade, and honestly, most lender portals are garbage. Some are better than others, and Flagstar's isn't the worst thing I've dealt with, but it still has its quirks that will frustrate you if you don't know what you're doing. The core idea is that you can apply for loans, check your rate, pull documents, and manage your existing loan all from one place. That sounds normal, but in practice, things like document uploads and payment setup will trip you up if you haven't walked through the workflow before.
Unlock The Power Of Personalized Lending With Www Flagstar Myloans
Here's how the actual process goes when you're applying for something through their site. You start by creating an account. They'll ask for basic personal info, employment details, income, and the property information if this is a purchase or refinance. Fairly standard stuff. What catches people off guard is that Flagstar doesn't always make it obvious whether you're looking at their consumer-facing application or the broker interface. If you're working through a mortgage broker, you might not even need a MyLoans account at all. Your broker handles the submission on their end. For direct applicants, once you're in, you can run a credit check. They do a soft pull first for rate shopping, then a hard pull when you're ready to go. I'd recommend checking your credit score on your own first before you commit to anything. There's no penalty for shopping around, but once that hard inquiry hits your report, it's there for 2 years regardless of whether you close the loan.
Document uploads are where things get messy. They accept PDFs, images, and sometimes you can fax directly through the portal. The system will reject files that are blurry or improperly named. I once had a borrower upload a pay stub scan that was sideways and labeled "image001.jpg." It got rejected three times before they figured out the naming convention. Take screenshots of your confirmation pages after every upload. The portal doesn't always send receipts immediately, and if you have a processing issue weeks later, you need proof you submitted that document on time. Rate lock management is another part of MyLoans that people use without fully understanding what they're locking into. When you lock a rate, you're agreeing to a specific interest rate and points for a set number of days. Standard locks are 30, 45, or 60 days. If your closing gets delayed and you're past your lock expiration, you'll face a float-down or extension fee. These can range from a fraction of a point to a full point depending on market conditions. I always tell my clients to build in a 10-day buffer between their rate lock expiration and their expected closing date. It costs nothing extra and saves a lot of headache. The payment center only works if your loan has already funded. Don't bother looking for it during the application phase. Once you've closed, you can set up autopay, make one-time payments, and view your payoff statement. Autopay typically gets you a 0.25% rate reduction, which is actually meaningful money over the life of a 30-year loan.
Get the Full Details

There's a specific edge case that trips people up regularly. If you're doing a cash-out refinance and you need to pay off an existing second mortgage or HELOC, Flagstar will require a payoff statement from that lender. They'll send the request automatically, but payoff statements expire after 30 days. If you're dealing with multiple lenders and one of them is slow to respond, your entire package can stall because an expired payoff is sitting in your file. I learned this the hard way when a borrower's HELOC lender took 18 days to respond, and by the time it arrived, the original payoff from their primary lien holder had already expired. The workaround is simple: call both payoff vendors directly and confirm the expiration dates before you submit everything. If one is expiring soon, request a re-issue immediately, even if your file isn't ready. Another thing the portal doesn't advertise well is that you can download your Closing Disclosure and final settlement statement directly from MyLoans after funding. Most people think they need to email their processor or wait for mail. That's unnecessary. It's in your documents tab once the loan funds.
Where Flagstar MyLoans Falls Short
I should mention the things that don't work well, because the marketing copy won't tell you. The mobile experience is poor. The site works on a phone browser, but uploading documents and filling out multi-page forms is painful on a small screen. Use a desktop computer whenever possible. I've watched people struggle with captcha verification on mobile and give up entirely, which delays their application by days. Customer support through the portal is another weak point. You can submit a help ticket, but response times vary from a few hours to 48 hours depending on where you are in the process. During peak volume periods in late fall and early winter, you can expect slower turnaround. If you're in escrow and time-sensitive, call the direct line instead of waiting for a portal reply. The phone queue is long, but at least you're talking to a human.
The rate quote tool on the homepage gives you an estimate, not a committed rate. A lot of people screenshot those numbers and bring them to their processor expecting that exact rate. Market rates move throughout the day. That homepage rate could be off by 0.125% or more by the time you actually apply. Get a real quote once you're logged in and past the initial screening questions. If you're doing a conventional loan with less than 20% down, Flagstar will require private mortgage insurance. The MyLoans portal will show you the PMI cost estimate, but some borrowers don't realize that PMI can be cancelled once you reach 20% equity through payments and appreciation. You have to request the cancellation yourself. It doesn't happen automatically.

Practical Workflow Tips
Here's what actually helps when you're working through this system. Do all your document gathering before you start the application. You'll need W-2s from the past two years, pay stubs from the last 30 days, bank statements for all accounts, tax returns if you're self-employed, and identification. Having everything ready upfront cuts your application time significantly. Most applications that drag on for weeks are stuck because someone went back to gather missing documents instead of moving the file forward. Use the saved data feature. Flagstar lets you save a draft application and come back to it. This is useful if you need to step away and look up a number or find a document. Don't start a fresh application every time you log in. It creates duplicate entries in their system and confuses the processors.
Check your email settings. Flagstar sends important updates through the portal and via email, but a lot of borrowers have aggressive spam filters that catch lender communications. I've seen applications delay because a borrower never saw an email requesting additional documentation. Whitelist flagstar.com and flagstarmyloans.com addresses in your email client. Set up autopay before closing if you can. You'll need your account number, which comes after funding, but you can prepare the authorization in advance. Your bank or credit union will want to verify the account, and having everything ready speeds up the transition from processing to servicing. Keep a folder of your login credentials. Yes, password managers exist, but I've seen borrowers lose access to their MyLoans accounts because they used a unique password they couldn't remember and couldn't reset quickly. The password reset process requires email verification, and if you've changed email addresses since you opened the account, you're locked out until you work through support. Write your username and password down and store it somewhere safe, or use a reputable password manager and share the credentials with your spouse or partner if this is a joint loan.
There's no mobile app to download. Some borrowers search the app stores looking for a Flagstar MyLoans app. It doesn't exist. The entire platform is web-based. Don't waste time looking for something that isn't there. If you're working with a broker, confirm with them whether they handle everything through their own system or if they want you on MyLoans. Some brokers don't use the portal at all and prefer to collect documents directly. Using both systems simultaneously can cause conflicts and duplicate requests. Stick to whichever platform your loan officer or broker designates as primary. The disclosure review period is three business days before closing. This is required by federal regulation, and the MyLoans portal will indicate when you've met that requirement. Don't try to waive it unless you have a genuine emergency. Waiving the disclosure period is legal but risky. You're giving up the chance to review the final numbers, and mistakes do happen in closings. I've seen interest rates change between the initial quote and the Closing Disclosure, and borrowers who waived their review period didn't catch it until after they signed.
Funding timelines vary by loan type and market conditions. A standard purchase refinance through Flagstar typically takes 30 to 45 days from application to closing, but this can extend if your property appraisal is problematic or if there are title issues. The MyLoans portal will show you the current status of your loan at each stage. If the status hasn't moved in more than five business days, follow up. Silence isn't normal in active processing.
Alternatives to Consider
Flagstar isn't the only option out there. If you're shopping around, compare their rates and terms with at least two other lenders. I've seen borrowers save thousands by not defaulting to their first choice. The process of comparing is straightforward. Get Loan Estimates from each lender, compare the interest rate, annual percentage rate, closing costs, and total projected payments over the life of the loan. The APR is the most useful number for comparison because it includes the interest rate plus most fees. If Flagstar's rates aren't competitive for your situation, credit unions often offer better terms on conventional loans, especially for members who have been with the institution for a while. Community banks are another option that sometimes underwrites more flexibly than the large national lenders. The MyLoans portal itself is fine for what it does, but it's not a substitute for good communication with your loan officer. The system tracks your file, but it doesn't answer questions or explain why something is delayed. You need a human on the other end who's actually paying attention to your deal.
If your loan falls into a non-standard category, like jumbo loans, construction-to-permanent financing, or loans with significant assets to document, Flagstar may not be the most flexible option. Their automated underwriting system has hard limits, and loans that require manual underwriting often move faster at regional lenders who specialize in complex files. One last practical note. If you're applying for a loan and you have recent large deposits in your bank accounts, document them before you submit your application. Large, unexplained deposits are the single most common reason for loan delays after the application is filed. A $10,000 deposit from a tax refund is fine. A $10,000 deposit with no paper trail is a red flag that will require a letter of explanation and sometimes additional verification. Taking five minutes to write that letter upfront saves weeks of back-and-forth later. The Flagstar MyLoans portal handles the administrative side of mortgage lending adequately. It's not the most polished system I've used, and it's not the worst. The key is knowing how it works before you dive in, having your documents organized, and maintaining direct contact with your loan processor throughout the process. The system does what it's supposed to do. It's up to you to use it correctly.


