Getting Into Your Marcus Account Without Losing Your Mind
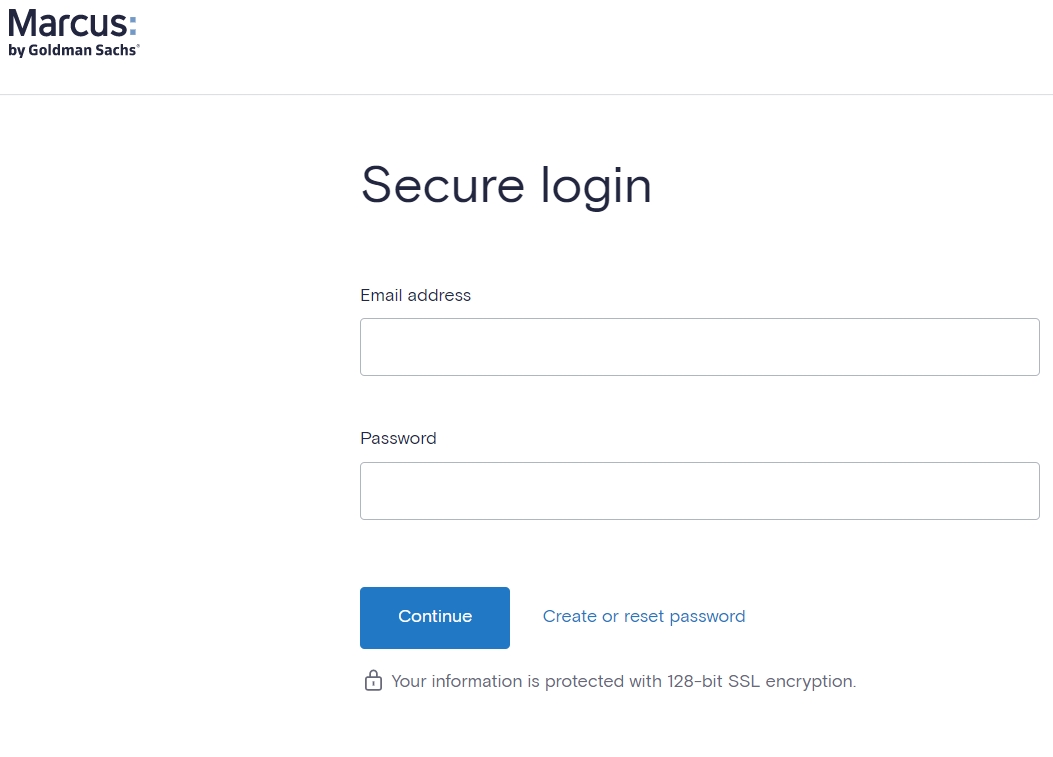
Logging into your Marcus credit card account is straightforward, but the perks section is where things get weirdly designed. I spent about forty-five minutes last month trying to figure out why my signup bonus hadn't reflected in my rewards dashboard even though my purchase had cleared. Turns out there's a 72-hour lag between transaction posting and reward crediting that Marcus never makes obvious anywhere in the interface. Once you know that, you stop checking every six hours. Here is how the process actually works when you sit down to log in. Go to marcus.com and click the sign-in button. You'll need your username and password. If you set up two-factor authentication, which you should, you will also get a code sent to your phone or authenticator app. Enter everything correctly and you are in. The dashboard layout is simple because Goldman Sachs designed it that way intentionally — they strip away most of the clutter that other issuers pile into your face. The rewards and perks section lives under a tab labeled something like "Rewards" or "Offers." Click it. You will see available cash back categories, promotional rates on purchases, and sometimes limited-time bonus offers. Marcus does not do points. They do cash back only. That simplicity is both their biggest selling point and their biggest limitation depending on how you spend.
I hit a wall recently when I tried to activate a bonus offer through the mobile app and it kept throwing a timeout error. The workaround was surprisingly simple: log in through a desktop browser instead. The mobile web version of Marcus's portal has known stability issues with the offers module. It is not a one-off problem either. I reported it through their chat support and got a ticket number back, but no real resolution timeline. The desktop browser approach works consistently every time since. One thing most people miss about Marcus's reward structure is that the cash back rate you see advertised is not always the rate you actually earn on every purchase. There are category restrictions, monthly caps on certain bonus rates, and purchase exclusions that apply to things like balance transfers and cash equivalents. These exclusions are buried in the terms and conditions link at the bottom of the rewards page. I learned this the hard way when I charged a large rent payment expecting the full bonus rate and then watched it get downgraded to the standard 1% because rent falls under cash-equivalent transactions. Goldman Sachs flags these at point of sale on most other cards. Marcus does not. Another counter-intuitive detail is that Marcus does not allow you to redeem rewards as a statement credit for arbitrary amounts. You can only redeem in increments of twenty-five dollars, and the minimum is one hundred dollars. So if you have earned eighty dollars in cash back, it sits there until you hit the threshold. Some people find this annoying. Others use it as a forced savings mechanism and appreciate the friction. It is worth knowing upfront.
The login process itself can trip people up because Marcus uses a fairly standard Goldman Sachs authentication backend. If you forget your password, the reset flow sends a link to your registered email. The link expires in fifteen minutes. I have lost count of how many times I opened the reset email, got distracted, and then had to start over. It sounds trivial but it adds unnecessary friction, especially if you are trying to check a balance or make a payment while on the go. Security-wise, Marcus is solid. They use encryption standard for the industry and their fraud monitoring is reasonably aggressive without being annoying. I had one transaction flagged while traveling and the hold was released within four hours after I confirmed it through their automated system. Not instant, but acceptable. If you live somewhere with higher fraud rates or travel frequently, just call them proactively before you go. Leaving it to the automated system to catch you mid-transaction means declined cards at checkout, which is worse than a quick pre-travel call. There are real limitations to the Marcus credit card experience that nobody really highlights. The customer service hours are limited compared to larger issuers. If you call outside their window, you are dealing with a voicemail system that does not return calls the same business day. Online chat exists but response times vary wildly depending on volume. During peak periods I have waited twenty minutes just to get a human on the line. This is not unusual for a digital-first bank, but it is worth factoring into your expectation.
Get the Full Details

The app itself is functional but sparse. You will not find budgeting tools, spending breakdowns by category beyond the basics, or integration with third-party financial apps the way you might with some newer neobanks. If you need granular spending analytics, Marcus is not your card. It is a straightforward cash back card disguised as a banking product, and that distinction matters when you are comparing it against alternatives. If you decide to log in and explore the perks, start by checking your current cash back balance and the minimum redemption threshold. Then scroll through available offers and activate any that align with your normal spending before you make the purchases. Offers that are not activated before the transaction will not retroactively apply. This is standard industry practice but Marcus does not send you a reminder about it. One final practical note: if you have a Marcus savings account alongside the credit card, logging into one automatically grants you access to the other through the same session. This is convenient but it also means your credit card activity and savings balance are visible on the same dashboard. Some people prefer that separation. A few I know keep their Marcus accounts open but access them through different browsers just to mentally compartmentalize spending from saving.
The login URL is straightforward and does not change. Bookmark it so you are not searching for it later. The whole platform is designed to be low-maintenance, which is either its greatest strength or its greatest weakness depending on whether you want a card that disappears into the background or one that actively helps you manage your money.