Letters of Credit Aren't Dead, They Just Got Faster
Most people still think letters of credit are slow, paper-heavy instruments that take weeks to process. They're right, mostly. But platforms like Ipost have quietly changed the mechanics of how these instruments are created, managed, and settled. I've been dealing with LC documentation for over a decade, and the difference between the old way and the ipost route isn't just speed. It's the entire workflow architecture. Ipost operates primarily within the Italian and broader EU trade finance ecosystem. It's a digital platform developed by Poste Italiane that connects banks, corporates, and trade finance intermediaries on a shared network. The core idea is straightforward: digitize the letter of credit lifecycle from issuance through amendment to settlement. What that means in practice is you're not emailing PDFs between your bank's trade desk and the beneficiary's bank anymore. You're working in a structured digital environment where document discrepancies get flagged in real time instead of during a weekend review. The setup is where most people stall out. You need to register through a participating bank or directly via Poste Italiane depending on your entity type. Individual traders can't just sign up and start issuing LCs. You need a corporate account and your bank needs to be integrated on the network. I spent three weeks trying to get my company set up because I assumed it would be plug-and-play. It's not. Call your relationship manager before you start the registration process and ask specifically whether their institution is live on the Ipost network. Several mid-tier banks in Italy are still rolling out full integration, and if yours isn't ready, you're stuck waiting.
Once you're on the platform, the actual LC issuance process takes roughly 15 to 30 minutes for a standard transaction. Compare that to the traditional route which usually involves filling out bank-specific paper forms, getting them physically signed, scanned, and emailed through correspondent banking channels. With Ipost, you fill in the SWIFT MT700 fields directly in the interface. The system validates mandatory fields before submission. I learned this the hard way after submitting my first LC with an incomplete shipment description and watching it bounce back before it ever reached the advising bank. The amendment workflow is where the platform really shows its value. Let's say your buyer needs to extend the shipment date by 14 days due to a supplier delay. In the old system, you'd draft an amendment request, send it to your bank, they'd confirm with the issuing bank, and you'd wait. On Ipost, you submit the amendment through the same interface, the issuing bank reviews it digitally, and once approved it propagates to the beneficiary's bank automatically. No phone calls, no faxes, no chasing. The beneficiary sees the amendment in their portal and can acknowledge it directly. There's a critical detail that trips up almost everyone new to this system. The discrepancy management feature. When documents are presented against an LC on Ipost, the advising or nominating bank reviews them against the LC terms within the platform. Discrepancies are logged digitally and communicated to the presenter immediately. This replaces the traditional process where a bank might sit on a discrepancy list for two or three business days before notifying anyone. The catch is that your documents still need to meet UCP 600 standards. The platform flags issues faster, but it doesn't forgive bad documentation. I had a situation where a bill of lading showed a partial shipment notation that triggered a discrepancy even though the commercial invoice was clean. The platform caught it in minutes instead of days. Fixing it took another hour because the carrier had to issue a corrected document.
Cost structure matters here too. Ipost transactions typically run cheaper than traditional paper-based LC processing because the manual handling component is reduced. Banks pass some of that savings along, but not all of it. Expect to pay a slightly lower issuance fee compared to your bank's standard LC rate, but the real savings come from reduced operational overhead on amendments, document examination, and correspondence. For a typical SME doing monthly trade volumes, this usually translates to meaningful cost reduction over a year. There are legitimate scenarios where Ipost won't help you. If your counterparty's bank isn't on the platform, you're back to traditional LC routing regardless of which side initiates the transaction. I've encountered deals where the exporter was on Ipost but their bank's correspondent in the destination country wasn't, which meant the LC still had to travel through conventional channels at the final leg. This is especially common when trading with countries in Africa, parts of Southeast Asia, or regions where digital trade finance adoption is low. Before committing to this approach, verify that your entire counterparty chain has access to the network or at least to a compatible digital trade finance platform. Another limitation worth noting is that Ipost currently focuses primarily on European trade finance workflows. The platform supports standard LC formats under UCP 600 and URDG 758, but if you're dealing with more complex instruments like standby LCs with unusual jurisdictional requirements or LCs governed by non-standard legal frameworks, the platform's templates might not accommodate them fully. I had a situation involving a standby LC for a construction contract in the Middle East where the governing law required specific Arabic-language clause formatting. The platform couldn't handle that, and we ended up issuing the LC through traditional channels despite having access to Ipost for the domestic portion of the transaction.
Get the Full Details
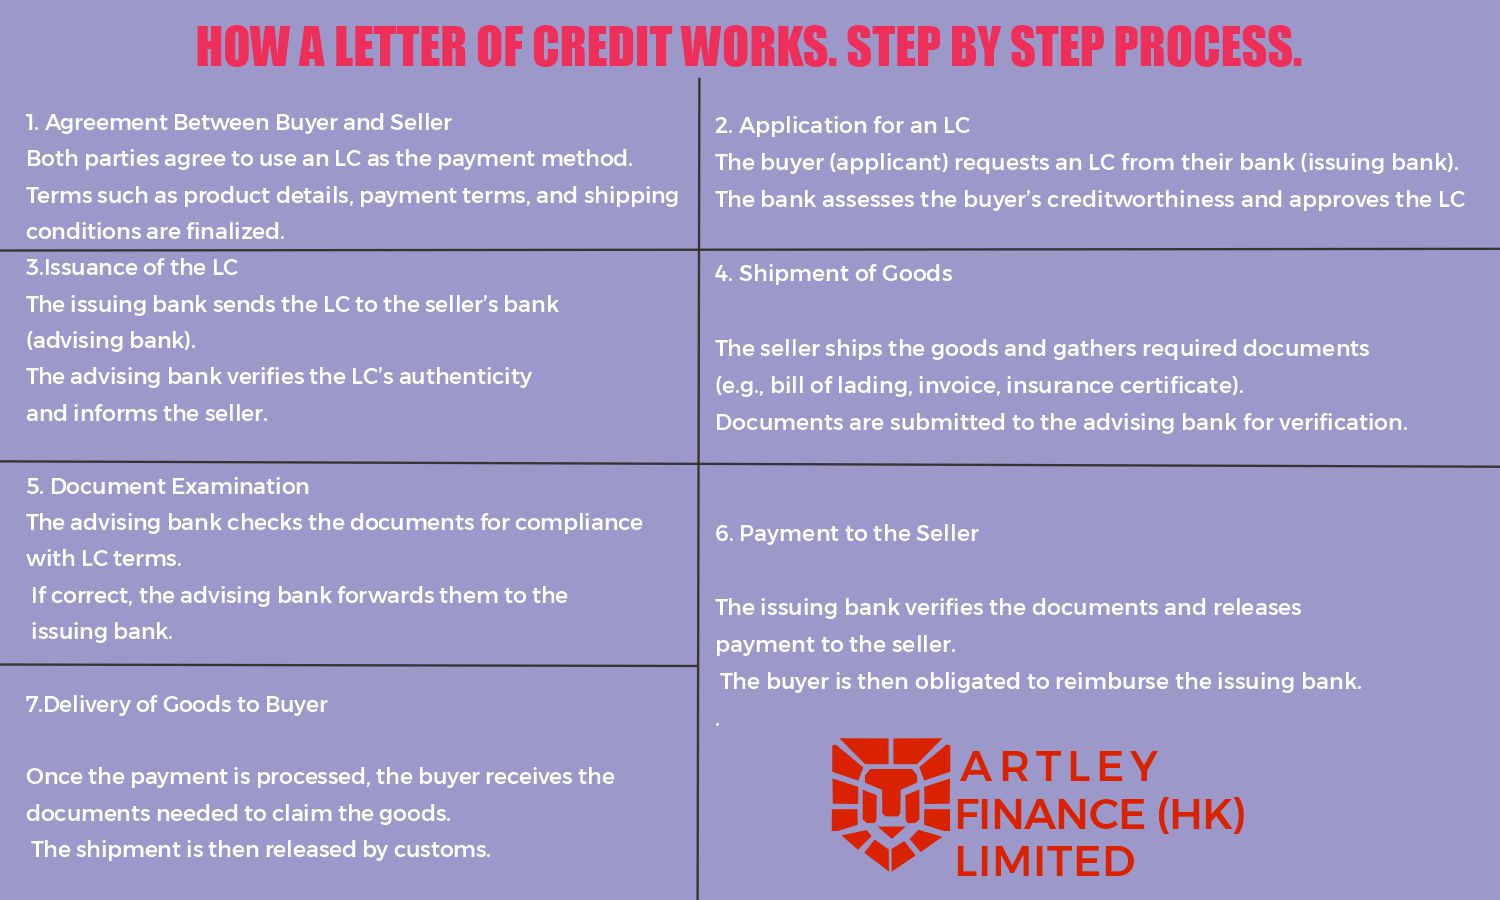
The training aspect is often overlooked. Your team needs to understand both the platform interface and the underlying LC rules. Ipost will teach you how to click through the screens, but it won't teach you why a discrepancy on a certificate of origin matters or how to properly phrase an amendment request. That still requires knowledge of Incoterms, UCP 600, and the specific documentary requirements for your commodity or service. I recommend pairing the platform implementation with a compliance review of your existing LC procedures. You'll likely find gaps that the digital format exposes but doesn't fix automatically. If you're already using traditional LCs and looking to reduce processing time and operational costs, Ipost is worth evaluating. If you're doing most of your trade in jurisdictions where digital infrastructure is limited, or if your LC structures are unusually complex, the hybrid approach of using Ipost for standard transactions and conventional methods for the edge cases is probably your most practical path forward.