What Hon Hai Precision Actually Is
Hon Hai Precision Industry Co., Ltd. is better known to most people as Foxconn. It's the Taiwanese multinational conglomerate that manufactures just about every consumer electronics device on the planet. They assemble iPhones, iPads, MacBooks, gaming consoles, server hardware, automotive components, and a long list of other products you probably use daily without thinking about it. The company went public on the Taiwan Stock Exchange under the ticker 2317, and shares also trade on the London Stock Exchange and through depositary receipts in the US market. Getting into Hon Hai isn't particularly complicated, but there are details most people skip and then get confused later. If you're based in the US or Europe and want to buy shares, your options depend entirely on where your brokerage account is domiciled. Some platforms like Interactive Brokers let you trade directly on the Taiwan Stock Exchange with your foreign account. Others may only offer the American depositary receipts traded on the LSE or OTC markets. You need to check what your broker supports before you even think about placing an order. Trying to buy TWSE-listed shares on a platform that only handles domestic markets will just result in a rejected order and some frustration. The stock trades in New Taiwan Dollars. That's the first thing to factor in because currency fluctuations can quietly eat into your returns or inflate them depending on the TWD/USD or TWD/EUR exchange rate movement. I've seen people celebrate a 5% gain on the stock only to lose most of it when the dollar strengthened against the New Taiwan Dollar in the same period. It's a mechanical thing, not a trick. The currency risk is real and it compounds over time.
What Moves This Stock
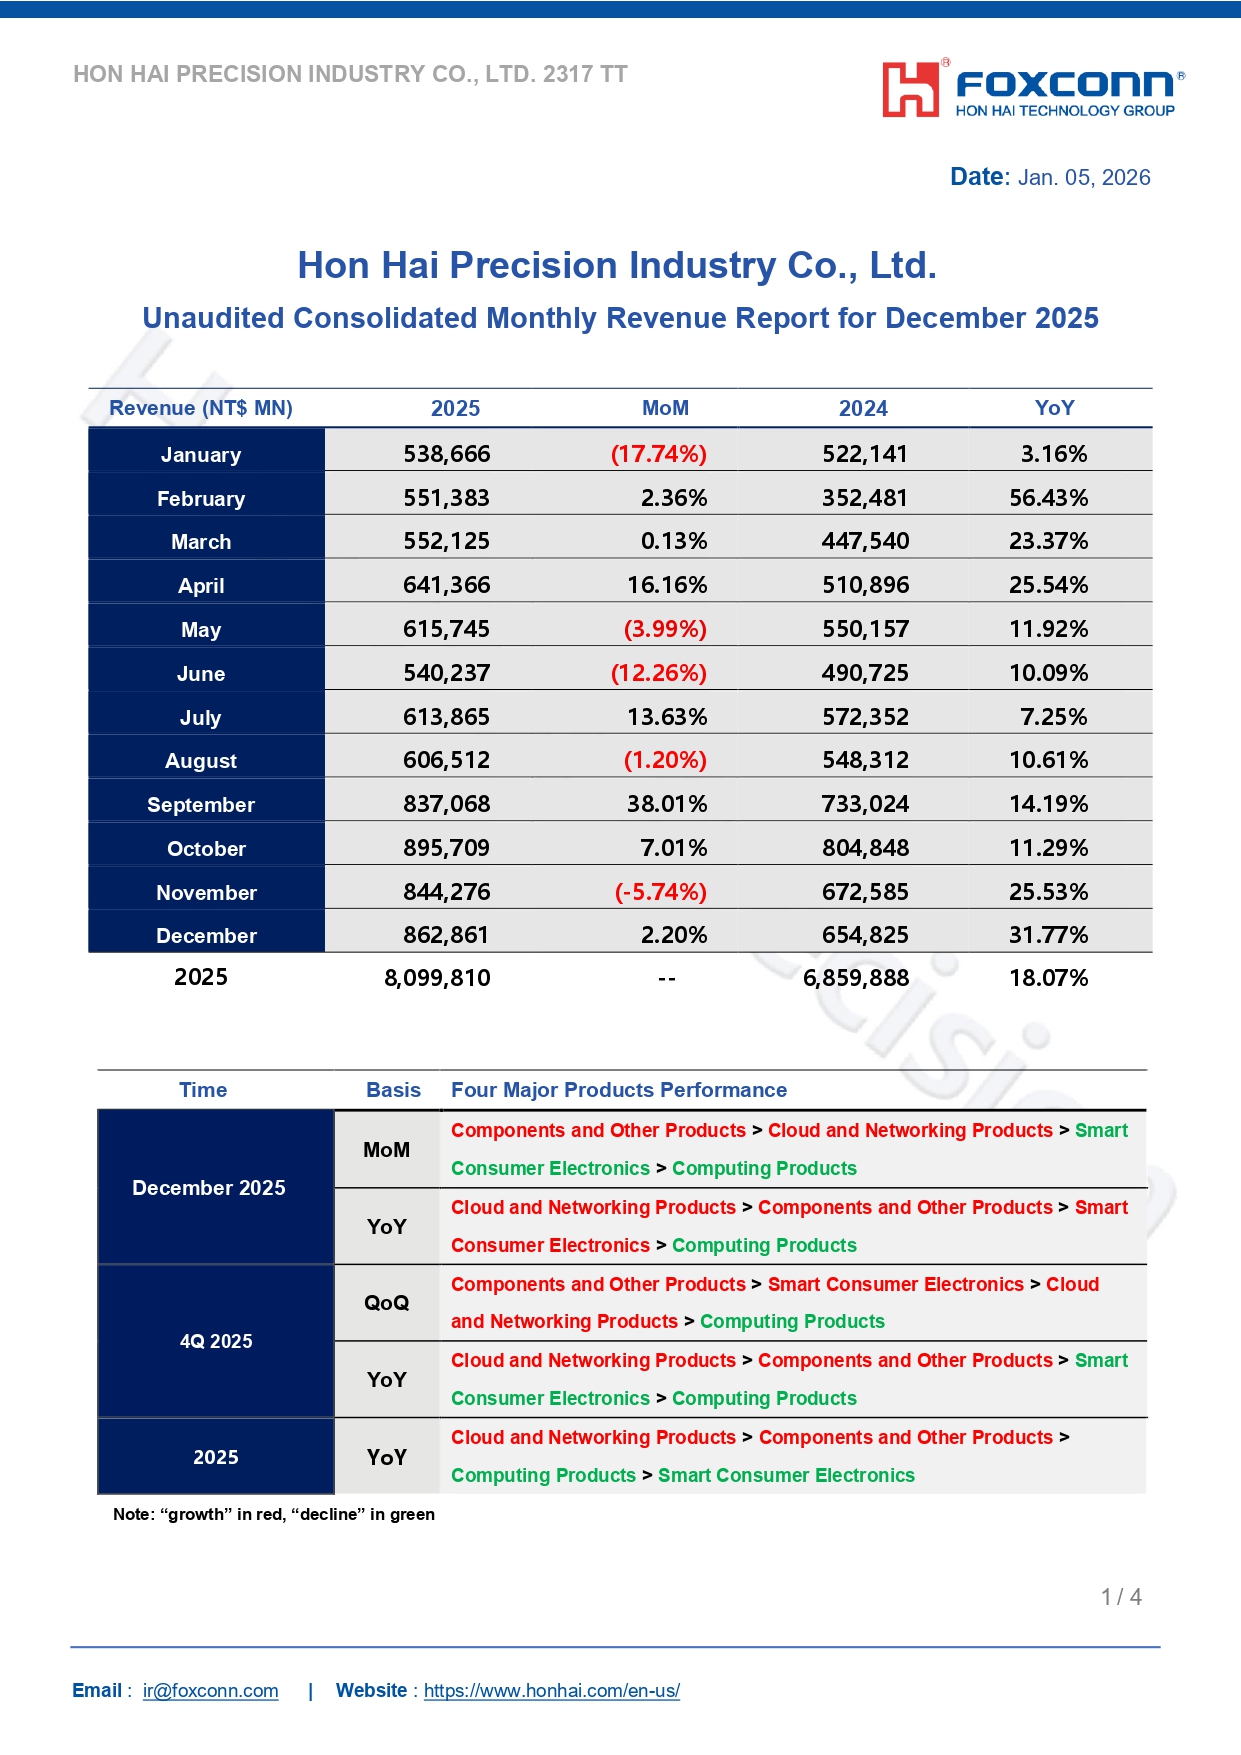
Hon Hai's revenue is overwhelmingly tied to Apple. Apple products account for somewhere around 40 to 45 percent of total revenue depending on the quarter and product cycle. When Apple announces a new iPhone, or when supply chain reports indicate production ramp ups at Hon Hai's facilities, the stock tends to react. That's not news that surprises anyone in the industry, but it does matter for timing. Earnings seasons are also critical windows. Hon Hai reports quarterly results and the market usually prices in guidance carefully. Missing revenue targets by even a small margin can trigger a sharp sell off because the margin structure here is thin and investors know it. But there's a less obvious driver that most casual investors overlook. Hon Hai has been pushing hard into automotive and AI infrastructure. They acquired a stake in Foxtran, their automotive electronics JV, and they're building out data center manufacturing capacity for NVIDIA GPUs and other AI hardware. The market sometimes rewards this pivot with a multiple expansion, and sometimes it doesn't. The stock has traded at a persistent discount compared to pure-play semiconductor names, which reflects the fact that assembly manufacturing carries lower margins than chip design. That gap occasionally narrows when AI demand creates genuine earnings upside, and it occasionally widens again when those expectations fail to materialize.
Practical Entry Considerations
Don't just buy because the stock price looks low in absolute terms. A share trading at 60 TWD isn't necessarily cheaper than one at 120 TWD. Look at the price to earnings ratio, the dividend yield, and the book value per share. Hon Hai typically pays a modest dividend, usually in the range of 2 to 3 percent depending on the year and board decisions. The dividend isn't the main reason anyone holds this stock long term, but it does provide a small cushion during volatile periods. Position sizing matters more here than in many other large cap names. Hon Hai can gap down significantly on a single bad supply chain report or a comment from Tim Cook about production shifts. I remember sitting through a quarter in 2022 where the stock dropped nearly 8 percent in a single session after Apple quietly shifted some MacBook Air production to India. The market had priced in continued concentration in Chinese manufacturing, and the rerating was swift. Anyone who had gone heavy without hedging took a real hit before the position could recover.
Get the Full Details

Risks That Aren't Talked About Enough
The geopolitical risk is the most cited, but it's worth being specific about what it actually means. Hon Hai operates manufacturing facilities in mainland China, Vietnam, India, and Mexico. Tariff changes, export control revisions, or diplomatic tensions between Taiwan and China can all create sudden operational disruptions. The company has been diversifying its footprint precisely because of this, but the transition takes years and capital. During the US-China trade war around 2019, Hon Hai's margins compressed because they had to absorb retooling costs that couldn't be passed through to customers immediately. That kind of event is repeatable. Another issue is the company's diversification strategy. They claim to be moving beyond consumer electronics into electric vehicles, smart home devices, and industrial automation. In practice, these segments remain small relative to their core business. The financial results don't yet justify treating Hon Hai as a multi-sector growth story. Analysts who model the company purely as an AI infrastructure play are often overstating near term contribution. The stock can run on narrative, but the earnings will eventually catch up to reality or they won't.
A Few Technical Details That Help
The Taiwan Stock Exchange has circuit breakers that can halt trading if a stock moves too far too fast. Hon Hai isn't immune to these, though they're more common among smaller caps. If you're placing market orders during high volatility events, consider using limit orders instead. A market order during a flash drop can fill you at a price significantly worse than the last quoted trade. I learned that the hard way during a routine earnings response trade a couple years back. The fill came in about 3 percent below where I expected it, which materially changed my average cost on a position I'd already sized carefully. Transaction costs also differ depending on how you access the stock. Trading on the TWSE directly through a broker like Interactive Brokers usually involves a commission plus a settlement fee and a trading levy that adds up to roughly 0.3 to 0.5 percent per side. Buying through an OTCADR or LSE listed vehicle may have different fee structures. If you plan to hold long term, these costs are manageable. If you're trading frequently, they add up quickly and eat into returns that are already thin on a percentage basis.
What to Watch Going Forward
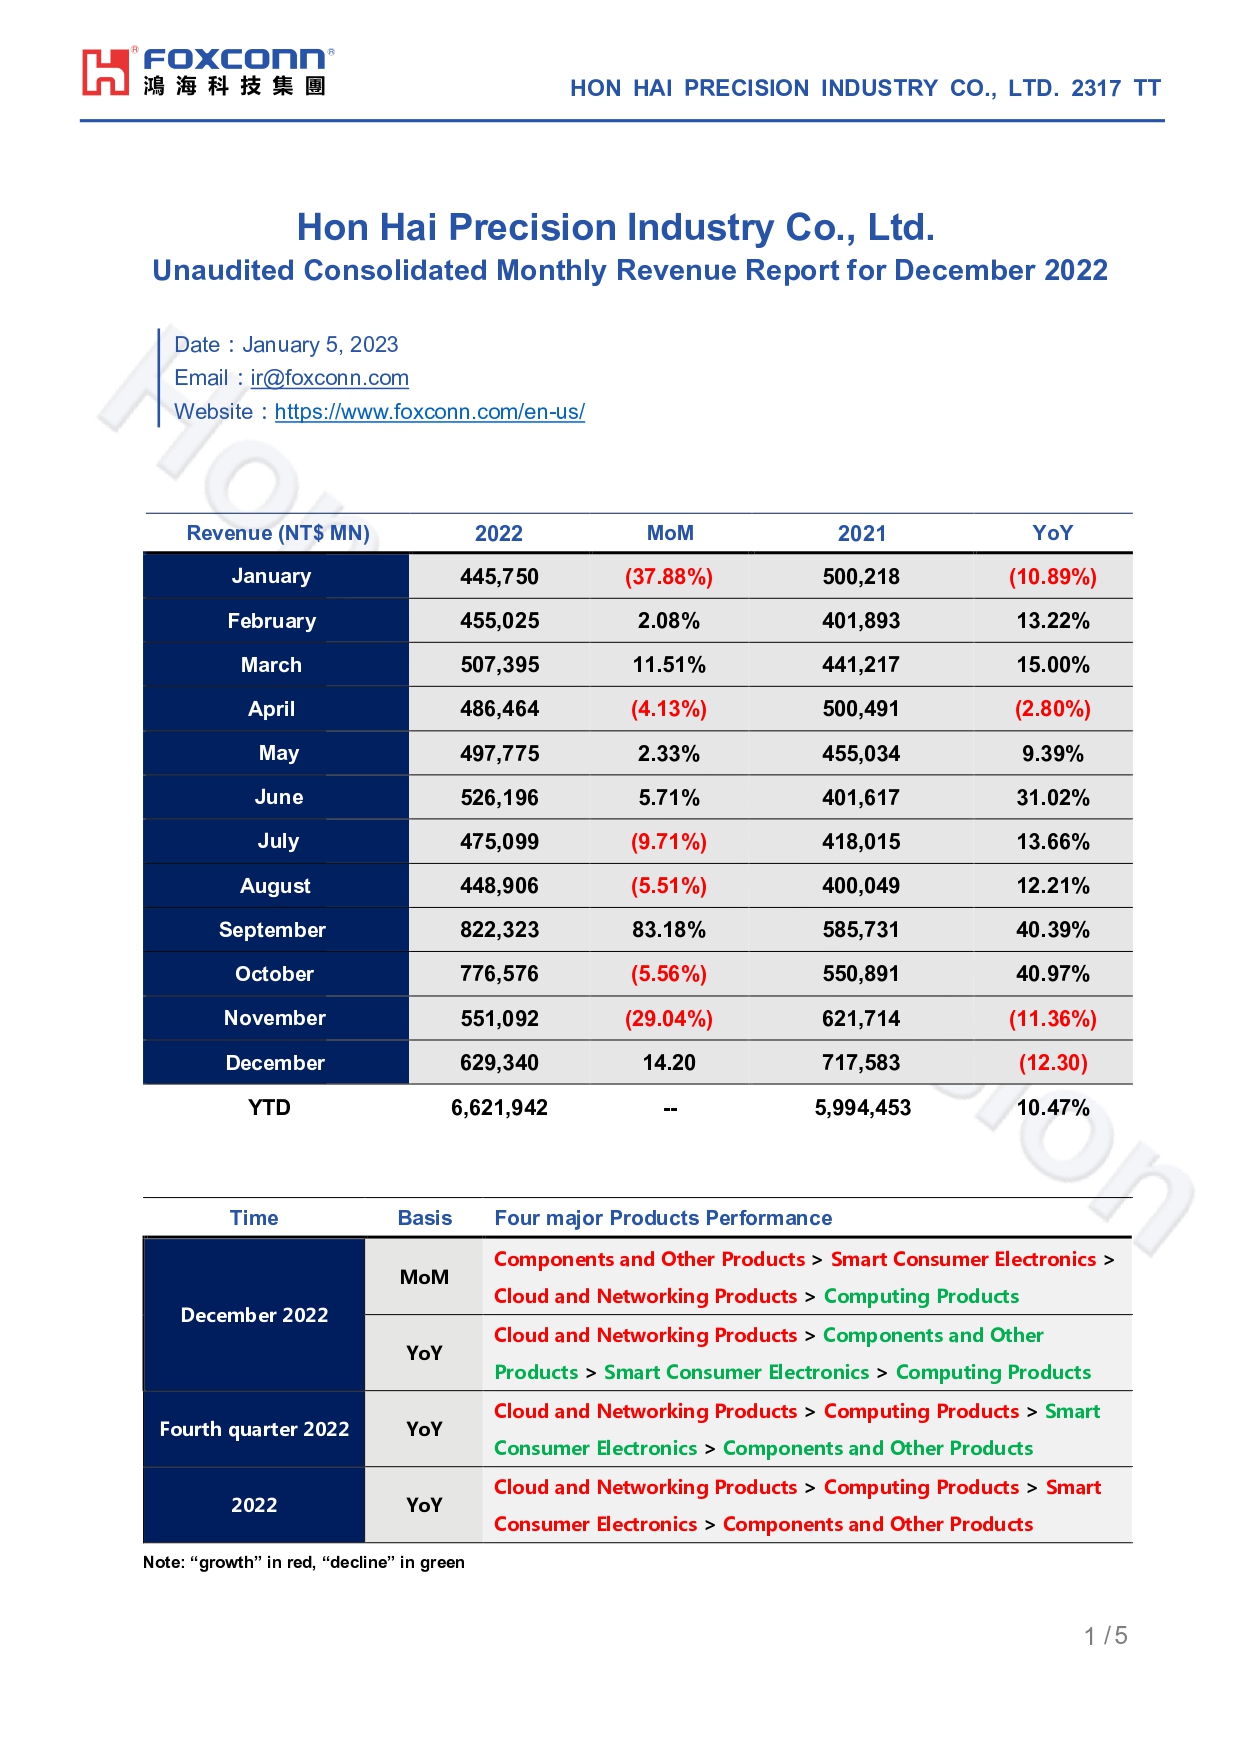
Keep an eye on Apple's product cycle announcements, Hon Hai's quarterly revenue breakdown by segment, and any comments about automotive business progress. The company's annual reports break down revenue by customer and product category, and that disclosure is genuinely useful. You'll see trends like iPhone contribution declining relative to server and networking equipment, which signals whether the AI pivot is actually generating material revenue or staying in the demo phase. Also monitor the TWD exchange rate. A strengthening dollar against the New Taiwan Dollar creates a headwind for USD-denominated returns even if the stock price itself moves higher. This isn't a stock that's going to double overnight on hype. It's a large cap manufacturer with thin margins, significant customer concentration, and real operational complexity. The upside comes from steady earnings growth, gradual diversification success, and the occasional multiple rerating when the market decides the narrative has shifted. The downside comes from geopolitical events, Apple supply chain decisions, and periods where the automotive and AI investments fail to convert into meaningful profit contribution. Both scenarios are plausible and both have happened before.