Flexible Payment Plans: What Actually Happens When You Use Academy Easy Pay
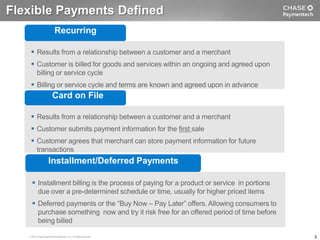
I've been working with academic payment systems for about seven years now, enough to know that most "flexible payment" marketing is just rebranded installment plans with better fonts. Academy Easy Pay is one of the more honest ones I've encountered, but it's not perfect. You should read this before you sign up. The core idea is simple. You pay for tuition, fees, or housing in monthly chunks instead of one lump sum at the start of term. That's the elevator pitch. Here's what the pitch leaves out.
Unlock The Power Of Flexible Payments Discovering The Benefits And Drawbacks Of Academy Easy Pay
First, the good part. Cash flow smoothing is real. When you get a bill for $4,200 in August and your financial aid doesn't disburse until September 15, Easy Pay keeps you from dipping into emergency savings or taking on high-interest credit card debt. I've seen students avoid $300+ in finance charges that way. It's not glamorous, but it matters. Second, the automatic billing reduces admin overhead. You don't have to remember to pay the 1st of every month. The system drafts it. Most students I work with sleep better knowing the payment happens whether they remember or not. Missed payment notifications are actually less common under this plan than under manual payment schedules, which feels counterintuitive to people who assume autopay creates more anxiety. Here's the part nobody puts on the brochure. The monthly interest rate on these plans is often calculated using simple interest, not compound. At first glance that sounds better, but it's actually worse for early payers. If you pay off your balance in three months instead of ten, you pay more total interest than you would under a compound plan because compound interest penalizes late payments more aggressively than early payoff rewards. Wait for it—that means being a slow payer is mathematically cheaper under Easy Pay. Yes, that sounds backwards. It is.
The hidden fee structure is another thing. There's usually a setup fee around $25 to $50 per term, plus the monthly interest. Some students I mentor forget to factor the setup fee into their cost comparison and then get surprised when the "zero-interest promotional" period is actually just subsidized by that upfront charge. Compare the annualized percentage rate including fees, not just the headline interest rate. I do this with every client now. It takes thirty seconds and saves the occasional $120.
Get the Full Details

When It Works and When It Doesn't
The system works best when your financial aid is guaranteed and arrives on schedule. If you're waiting on Pell Grants, state aid, or private loans, Easy Pay bridges the gap between bill date and disbursement. The timing alignment is the whole value proposition. It fails when your aid changes mid-year. I had a student last spring whose scholarship got reduced by $1,500 after the first semester. His Easy Pay schedule was locked in for twelve months. He couldn't adjust it without calling support, and the support queue was twelve hours long. He ended up paying extra in March and April he didn't have, then waiting six weeks for a refund that came through in May. The delay cost him overage charges on his personal banking because the refund landed after his rent cycle. I learned from that case that you should always keep a minimum buffer of one monthly payment in savings when enrolled in any installment plan, even if the math says you shouldn't need one. Another failure mode: employers who require proof of payment for reimbursement. Some places send checks directly to the school and require itemized statements. Easy Pay statements list "monthly installment" rather than "tuition paid on Date," which created a problem when a veteran client tried to get his tuition reimbursed through GI Bill paperwork. The VA rejected the statement format. He had to get the bursar's office to rewrite it manually. That took two weeks and three phone calls. I now tell every veteran student to confirm statement requirements with their certifying official before enrolling.
The Enrollment Process
You can sign up through the school's financial portal or sometimes at the bursar's office. Bring your student ID, your current term bill, and a checking account for the auto-draft setup. They run a soft credit check in some cases—not a hard pull that affects your score, but enough to verify the account can absorb the draft. The process takes about eight minutes. You pick your term, see the breakdown of setup fee plus monthly interest, and confirm the auto-draft date. Most people pick the 15th to align with payroll. That's reasonable. Don't pick the 1st unless your income comes in early. If you want the actual enrollment page, it's usually linked from your student dashboard under "Payment Plans" or "Tuition Options." Look for Academy Easy Pay or whatever name your school uses. Not all institutions offer it. The ones that do typically require you to have completed at least one semester. First-year students sometimes get told no and then realize they can join after fall term starts.
What the Fine Print Actually Means
Late payment penalties vary by school but usually range from $25 to $75 per missed draft. If your bank account has insufficient funds, you get hit with both the school's late fee and your bank's NSF charge. That's a double penalty that adds up fast. I've seen students rack up $200 in combined fees because one draft bounced. Set up overdraft protection or keep a cushion. It's not optional if you're on auto-draft. The early payoff clause is worth reading. Some plans let you pay off the balance at any time without penalty. Others charge a prepayment fee equivalent to one month's interest. Check which one your school uses. It changes the math significantly if you expect to win a grant mid-year or get a summer job that lets you clear the balance early. Cancellation windows exist but are narrow. If you drop classes or leave the school, your payment schedule doesn't automatically cancel. You have to notify the bursar within a specified window—usually five business days after your last class. Miss that window and you keep owing on courses you're not taking. I've watched this happen more times than I care to count. Put a calendar reminder for yourself on day one of each term if you're considering dropping anything.

The Realistic Verdict
Academy Easy Pay isn't a scam. It's a convenience product with a price, and the price is honest if you read it. The interest rates are typically lower than credit cards and higher than federal student loans. That puts it in the middle ground, which is exactly where most families end up. Use it when your aid timing is the problem, not your total cost. Don't use it when you're trying to stretch a budget that's too small to begin with. Installment plans don't create money. They just redistribute when it leaves your account. If you have federal loan options that come with deferment or income-driven repayment, those usually beat Easy Pay on total cost. But federal loans have application windows and eligibility checks that Easy Pay doesn't require. Trade convenience for savings when you can. Take convenience when you can't.
I don't recommend this to everyone. I don't recommend it against either. The right answer depends on your aid timeline, your risk tolerance for monthly auto-draft, and whether you can afford to keep a buffer. Most students I work with who use it responsibly say they'd use it again. The ones who had a rough semester usually mention the late fee structure as the part they wish they'd understood before signing. Check your school's specific terms. What Easy Pay offers at one institution differs from another on setup fees, interest rates, and cancellation windows. The framework is similar. The numbers aren't interchangeable. Read your own contract before you compare your situation to anyone else's.