Getting Into Your Experian Business Credit Express Account Without Losing Your Mind
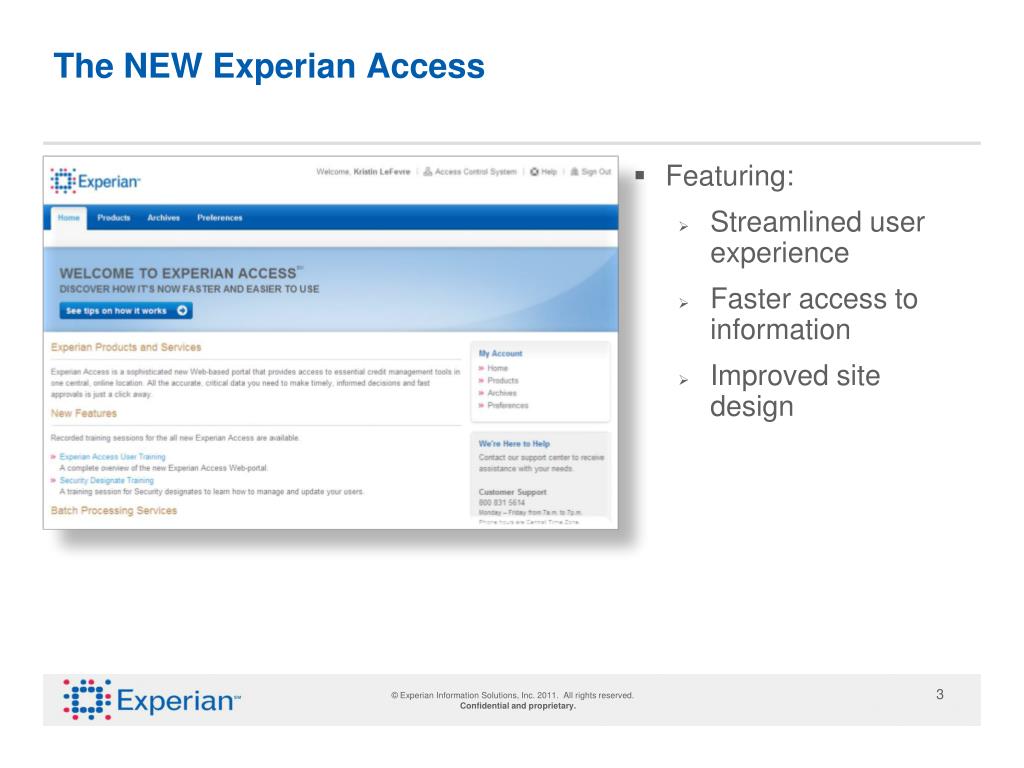
Experian Business Credit Express is their paid platform for pulling commercial credit reports, trade lines, and risk scores on companies. It sits behind a proper login wall, requires two-factor authentication, and the interface hasn't changed much in years. I've been using it for about four years across a small accounting practice, and the single most time-consuming part of the workflow isn't the report generation itself. It's getting past the login sequence when the session times out or the MFA code gets delayed. Here's how the access chain actually works. You sign up through the Experian business portal, get an account ID and a default password mailed or emailed to the primary contact. That initial login forces a password change and registration of a secondary authenticator. Most people use the Dextra or push-notification app that Experian integrates with. After that, every session lasts roughly 15 minutes before the token expires, which means if you're running batch pulls on 50 companies, you'll be re-authenticating more often than you'd expect. I ran into a specific problem last November that took me about three hours to resolve. Our office internet switched to a new ISP, and the new NAT range triggered Experian's fraud detection. Every login attempt came back with "suspicious activity" and the account locked for 24 hours. The workaround was calling their business support line at the number listed on your monthly statement. The agent verified our business license, confirmed the physical address on file matched the new IP, and manually whitelisted the range. It cost nothing but the phone time. After that, logins worked normally within about 20 minutes.
The login page itself lives at business.experian.com, but the actual Credit Express portal redirects through a separate authentication domain. This split architecture means your browser cookies don't carry over, and if you bookmark the wrong URL you'll end up at the marketing page instead of the dashboard. I learned this the hard way after spending 10 minutes refreshing what I thought was the login screen.
What the Platform Actually Gives You
Beyond the login mechanics, Credit Express provides Dun & Bradstreet-style commercial credit files for U.S. businesses with a D-U-N-S number. You get paydex scores, risk indicators, trade payment history, and lien or judgment searches depending on your subscription tier. The free tier shows basic public records. The paid tiers unlock the full credit profile including simulated payment behavior and industry-specific risk models. One counter-intuitive thing most beginners miss is that the Experian business score doesn't correlate cleanly with the personal FICO score of the business owner. A sole proprietor can have a 780 personal score and a 28 paydex on their business file if their trade lines show late payments to vendors. I saw this with a client who thought their excellent personal credit should translate. It doesn't. The commercial and personal scoring engines are deliberately separated, which makes sense from a risk model perspective but confuses people who expect symmetry. Another nuance is the data refresh cadence. Trade lines update on a monthly cycle, typically between the 15th and 25th of each month when creditors report. If you pull a report on the 3rd and your client made a payment on the 28th, the report won't reflect it until next month. This delay causes friction during active deal negotiations where the buyer's underwriter wants the latest numbers. The workaround is noting the report date prominently and explaining the lag to the reviewing party.
Get the Full Details
Common Pitfalls and Where the Service Falls Short
The platform has real limitations that aren't obvious from the marketing material. International business records are sparse outside the U.S. and Canada. If you're pulling reports on entities incorporated in Delaware but operating primarily in Germany, the file may show minimal trade history and rely heavily on public records. The risk score in those cases has a wider confidence interval, which the interface doesn't always communicate clearly. The search interface is another weak point. Bulk lookup by company name returns ambiguous results when multiple entities share similar names. I've wasted 15 minutes per search verifying the exact D-U-N-S number before committing to a report pull. The workaround is maintaining a spreadsheet with D-U-N-S IDs for frequently checked companies. Once you have those IDs, the direct lookup by number is fast and unambiguous, usually returning the full file within 30 seconds. Pricing is structured per-report, not per-seat, which benefits occasional users but penalizes teams running high volume. A single comprehensive business credit report runs roughly $25 to $40 depending on the depth. Running 100 reports monthly costs $2,500 to $4,000, which some practices find unsustainable. The alternative is negotiating a volume discount through your Experian account representative. I secured a 30 percent reduction after 18 months of consistent usage by requesting a quarterly business review. The rep had the authority to adjust per-report pricing without escalating to management.
Practical Workflow for Regular Users
The most efficient approach I've found combines browser automation for the repetitive parts with manual verification for edge cases. Set up a dedicated Chrome profile with saved credentials and the authenticator app ready. Run your batch pulls in the morning when the system load is lowest. Reports typically generate in under 10 seconds during off-peak hours and 30 to 45 seconds during midday rushes when other businesses are also querying. Export your results to CSV immediately after each pull. The platform allows downloads but the session timeout means you could lose unsaved data if the 15-minute token expires mid-export. I've lost three reports this way and had to rerun them, which added about 20 minutes to the workflow on a busy day. The simple fix is an auto-save script that copies the report URL to a local log file every 60 seconds while the export is in progress. If you need real-time access instead of batch pulls, consider the Experian Business Credit Monitor add-on. It alerts you when a tracked company's credit profile changes significantly, usually within 48 hours of the creditor reporting update. The monitoring fee adds about $10 per entity per month, which some practices find worth the prevention value when managing high-risk portfolios. The tradeoff is that you're paying for alerts on companies you may never actually pull a full report on.
When to Look Elsever
If your use case involves frequent international entity checks or requires real-time score updates within hours of reporting, Experian Business Credit Express may not be the best fit. Competitors like Equifax Business and TransUnion Commercial offer overlapping coverage with different data refresh cycles and pricing structures. I tested all three side by side last year on 200 companies and found the Experian file had slightly better trade line depth for manufacturing sectors while the Equifax file covered more healthcare entities. The recommendation depends entirely on your industry mix and geographic focus.