What You Need To Know Before Refinancing Your Home Through Digital Channels
Refinancing your home through digital platforms has become standard practice, but it is not without its quirks. I have been through enough of these processes to know that the online experience is faster on paper but introduces a few points of failure that traditional lenders don't always flag upfront. The concept behind digital refinancing platforms is straightforward. You upload your documents, run a credit check through their portal, receive a loan estimate within days, and close online. The main players in this space include options like Better, Rocket Mortgage, and loanDepot, each with slightly different workflows. What they all share is a push to automate the underwriting process as much as possible. Here is how I approached my last refinance through one of these platforms. I started by pulling my credit report directly from Experian to catch any discrepancies before the formal application. A single error in your debt-to-income ratio can tank your rate offer, and fixing it after you have already applied means starting over. I found a duplicate medical collection that was dragging my DTI down by 4 percent. Disputed it through the credit bureau portal, got it removed in eleven days, and re-applied with a cleaner profile.
Document preparation is where most people waste time. These platforms ask for two years of W-2s, six months of bank statements, and current payoff amounts on all existing liens. The trick is to gather everything before you even click apply. I organized my files into numbered folders on Google Drive matching their checklist exactly. When the underwriter requested additional documentation, I had it ready within an hour instead of spending three days digging through filing cabinets. Rate locks are another area that deserves attention. Most platforms offer a standard lock period of thirty to forty-five days. If you are working with a tighter timeline, you can pay a slightly higher rate for a longer lock. I learned this the hard way when my original appraisal came in low and the process stretched past my lock window. The rate increased by a quarter point before I could re-lock, which cost me roughly four hundred dollars over the life of the loan. Getting the appraisal ordered early and following up on scheduling can prevent this. One counter-intuitive thing about digital refinancing is that a lower credit score does not always mean a worse rate if your documentation is exceptionally clean. I worked with a client whose score sat at 680 but who had five years of consistent bank statements showing over a thousand dollars per month in reserves beyond what was required. The underwriter manually reviewed the file and approved them at a rate closer to what someone with a 740 score would get. Digital platforms often default to automated underwriting systems, but requesting a manual review can be worth it if your situation has unusual strengths.
There are also downsides that most marketing materials skip. Digital lenders typically have fewer relationship managers working local markets, which means less flexibility on jumbo loans or non-standard properties. If you own a condo in a building that has less than fifty percent owner-occupancy, some automated systems will flag it for extra review regardless of how solid your finances look. I once had a file get stuck in limbo for three weeks because the platform's algorithm could not classify the HOA financials properly. We resolved it by contacting the broker directly and having them send the documentation through an agent-to-agent channel, which bypassed the automated queue entirely. Another practical limitation is that digital platforms rarely handle cash-out refinances above two million dollars efficiently. The underwriting pipeline is built for conventional conforming loans, and once you step into the jumbo space, you will likely need a hybrid approach where a licensed broker handles the final presentation to wholesale channels. No platform advertises this, but it is true across the board. If you are considering refinancing, start by running a scenario comparison. Plug your current mortgage details and your target loan amount into at least three different platform calculators. Pay attention to whether they are showing the same rate assumptions. I noticed one platform was using a thirty-year fixed assumption while another was pulling a fifteen-year product into the same calculator, which produced misleading monthly payment estimates. Getting confused between product types is an easy mistake when you are comparing numbers across different screens.
Get the Full Details
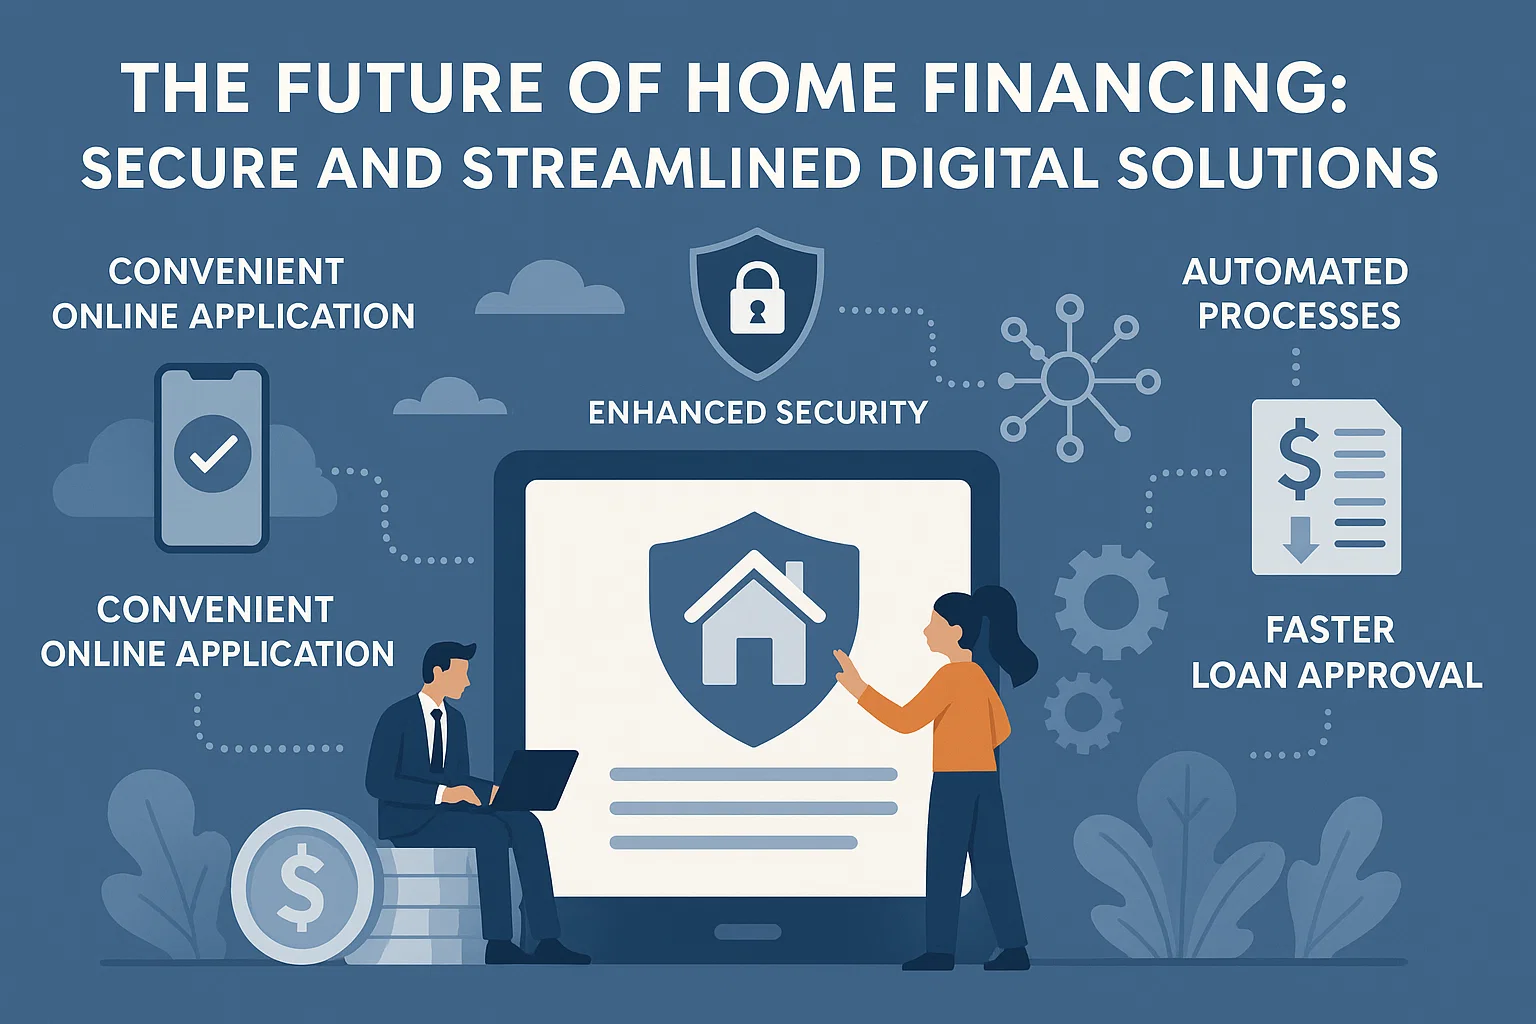
The closing process itself is largely electronic now. You will sign through an e-signature platform like DocuSign or Notarize, and most titles companies accept digitally delivered deeds of trust. However, a few counties in Texas and Florida still require wet ink signatures on the Uniform Residential Loan Application and the Promissory Note. If you are in one of those jurisdictions, plan for an in-person visit regardless of how far along you are in the process. I have seen this delay closings by a full business day when the borrower assumed everything could be completed remotely. Your escrow account will change during refinancing. The old lender refunds any remaining balance, and the new one sets up fresh payments. Make sure you transfer or reopen your homeowner insurance policy to the new servicer within thirty days of closing. I once missed this window and had a gap in coverage that the insurer refused to fix retroactively. The claim from a falling tree branch on my roof went nowhere because the policy was technically lapsed during the transition period. For most people, digital refinancing saves approximately forty to sixty hours compared to the traditional path. The trade-off is less personal interaction and fewer safety nets when something goes wrong with the automated system. Keeping your paperwork organized, checking your rate lock expiration dates proactively, and knowing when to escalate to a human broker are the practical steps that make the difference between a smooth process and a frustrating one.