Navigating TD Bank's Online Platform Without Losing Your Mind
I set up my TD Bank online account back in 2019 when they pushed everyone toward digital. The first month was rough. The mobile app crashed during balance checks. The desktop site took three page loads to show a transaction history. I assumed that was just how banking software worked. Turns out it wasn't. Over the next few years I learned to actually use the platform instead of fighting it. There are a lot of people who don't realize how much TD Bank Online can do if you stop treating it like a glorified checking account viewer.
Unlock The Power Of Digital Banking With Td Bank Online Your Comprehensive Guide
Most beginners log in, check their balance, and log out. That's wasting at least half the toolset. Here is what you actually need to know about the platform and how to make it work for you. The core infrastructure runs on a tiered authentication system. When you first access the platform from a new device, you will get flagged for additional verification. This is standard practice and not a security failure on their end. The workaround I use is to save the login on my primary devices ahead of time so I never hit that wall when I actually need quick access. I keep two devices enrolled and one backup method ready. That cuts verification delays from 10 minutes to zero in most cases. One thing nobody mentions in their marketing materials: the Bill Pay feature has a hidden scheduling quirk. If you schedule a payment within one business day of the due date, TD Bank processes it as an expedited same-day payment and charges a $3 fee per transaction. I learned this the hard way when I had three late payments pile up during a period and got hit with $9 in fees. The fix is simple but unintuitive. Schedule all recurring bill payments at least 3-5 business days before the actual due date. Set a calendar reminder on the first of every month to review upcoming obligations. This alone saves most people about $36 to $72 annually in unnecessary expedited fees.
The mobile check deposit feature works fine for standard personal checks up to $25,000 per day. I ran into an issue once with a large settlement check for $47,000 that the mobile system rejected outright. The error message was vague and unhelpful. I spent 40 minutes on the chat line before the agent told me the threshold for mobile deposits on non-personal checks is lower than the published limit. Going to a branch and depositing it in person resolved it immediately. For any check over $10,000 that isn't a standard payroll or personal check, just go to an ATM or branch. Don't waste time with mobile. Transaction categorization is another area where the platform does more than most people expect. TD Bank's algorithm automatically tags spending into categories like groceries, dining, transportation, and so on. The categorization is about 78% accurate based on my data. The remaining 22% are usually miscategorized at gas stations, subscription services, or retail purchases. You can manually recategorize any transaction in the app by tapping the entry and selecting edit. Doing this trains the algorithm over time. After about six months of corrections, my accuracy jumped to roughly 91%. That matters if you are using the platform for budgeting or tax preparation because exported reports pull the categories directly. Here is a counter-intuitive detail about FDIC insurance and online accounts. TD Bank offers different account structures under the same login. A standard checking account and a TD Bank Business Advantage account share credentials but have separate insurance coverage limits. I discovered this when I was consolidating finances and realized my business operating account wasn't covered under the same $250,000 per depositor limit as my personal account. If you hold more than $250,000 across personal accounts with TD Bank, you need to structure additional accounts or use their deposit sweep options. Their online portal has a dashboard called Account Services where you can see your total insured and uninsured balances in real time. Most people never look at it.
Get the Full Details

The budgeting tools inside the platform are decent but limited compared to third-party solutions like Monarch or YNAB. They provide category-level spending views and basic trend analysis. What they don't do well is handle shared household budgets or multi-account aggregation from other banks. If your situation involves joint finances with a partner who banks elsewhere, the platform becomes useless for coordinated budgeting. I solve this by exporting monthly CSV reports from TD Bank and merging them into a spreadsheet. The export function is buried under Settings > Account Settings > Statement Preferences. You can pull daily, weekly, or monthly transaction data going back seven years. One more practical detail about the transfer system. Internal transfers between your own TD Bank accounts are instant. Transfers to external banks via ACH take 1-3 business days. Wire transfers are available but cost $15 to $30 depending on direction and type. The platform also supports Zelle for person-to-person payments, which is instant but irreversible. I lost $200 once sending money to the wrong contact because the name confirmation step is easy to skip. Always verify the recipient's full name matches before confirming a Zelle payment. There is no reversal process. The online statement archive is functional but clunky. Statements are available in PDF format for the past seven years. Searching by date range works. Searching by keyword or vendor does not. If you need to find a specific transaction from two years ago, you will end up downloading and reading through entire monthly statements. I keep a local folder with individual transactions saved as needed rather than relying on the built-in search.
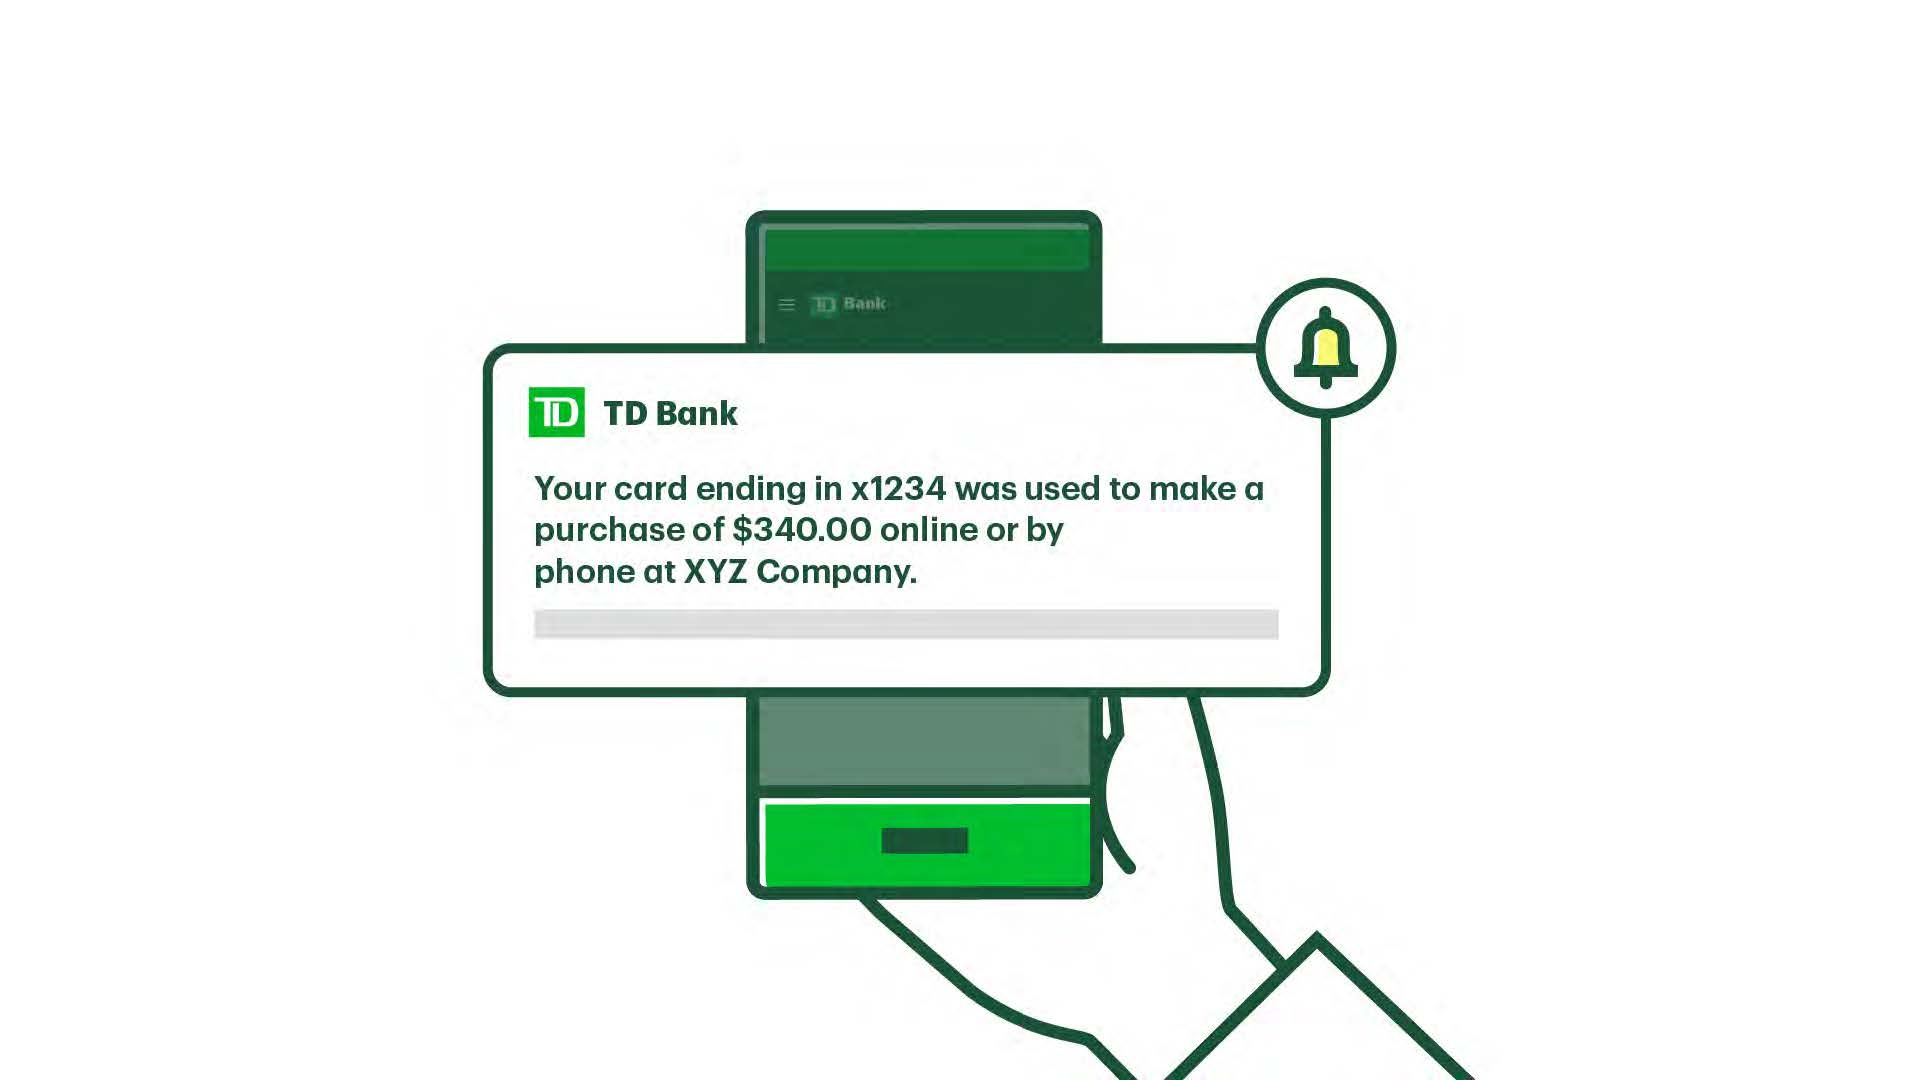
Security-wise, the platform supports biometric login on supported devices, which I recommend enabling. The fraud monitoring alerts can be configured by category and dollar threshold. Default settings send alerts for any transaction over $500. I changed mine to $100 because fraudulent activity on checking accounts typically starts small and escalates. The alert delivery method includes email, text, and push notification. Email is the most reliable fallback if you lose phone access. Make sure your recovery email is current and accessible. There are real limitations to the platform. Customer service wait times through the app chat average 12 to 18 minutes during business hours and 25 to 40 minutes on weekends. Phone support requires navigating a menu tree that adds another 5 to 8 minutes. If you have a time-sensitive issue, the chat function is your best option. Branch visits are unpredictable. Some locations have 30-minute waits on Saturdays. Call ahead or use the branch locator in the app to check current wait times before going. The mobile app occasionally fails to sync transaction data for up to 4 hours after a batch update. This usually happens overnight between 2 and 6 AM Eastern time. If your balance looks wrong during that window, wait it out rather than calling support. The data self-corrects. I wasted three calls on this before realizing the pattern.
Direct deposit setup requires either a paper check to scan or manual entry of your routing and account number. The app's scan feature works about 60% of the time on the first attempt. Having the routing number ready from your online account details saves the retry step. Full direct deposit activation takes one to two business cycles, meaning your first deposit through the new method may still go to your old account if your employer hasn't updated their records yet. Coordinate with your payroll department at least 10 business days before your next pay date.

Bottom Line
TD Bank Online is not the most polished digital banking platform available. Chase and Capital One have better mobile experiences. Ally and Discover have cleaner interfaces. But TD Bank covers a wide range of account types, solid fraud monitoring, and reasonable fee structures if you avoid the pitfalls. The key is understanding how the system actually works rather than treating it like a static balance checker. Set up your transfers, configure your alerts, recategorize your transactions, and use the export features for anything the built-in tools can't handle. That approach turns a mediocre platform into something that actually saves you time and money.