Why People Obsess Over Compound Interest Without Actually Understanding It
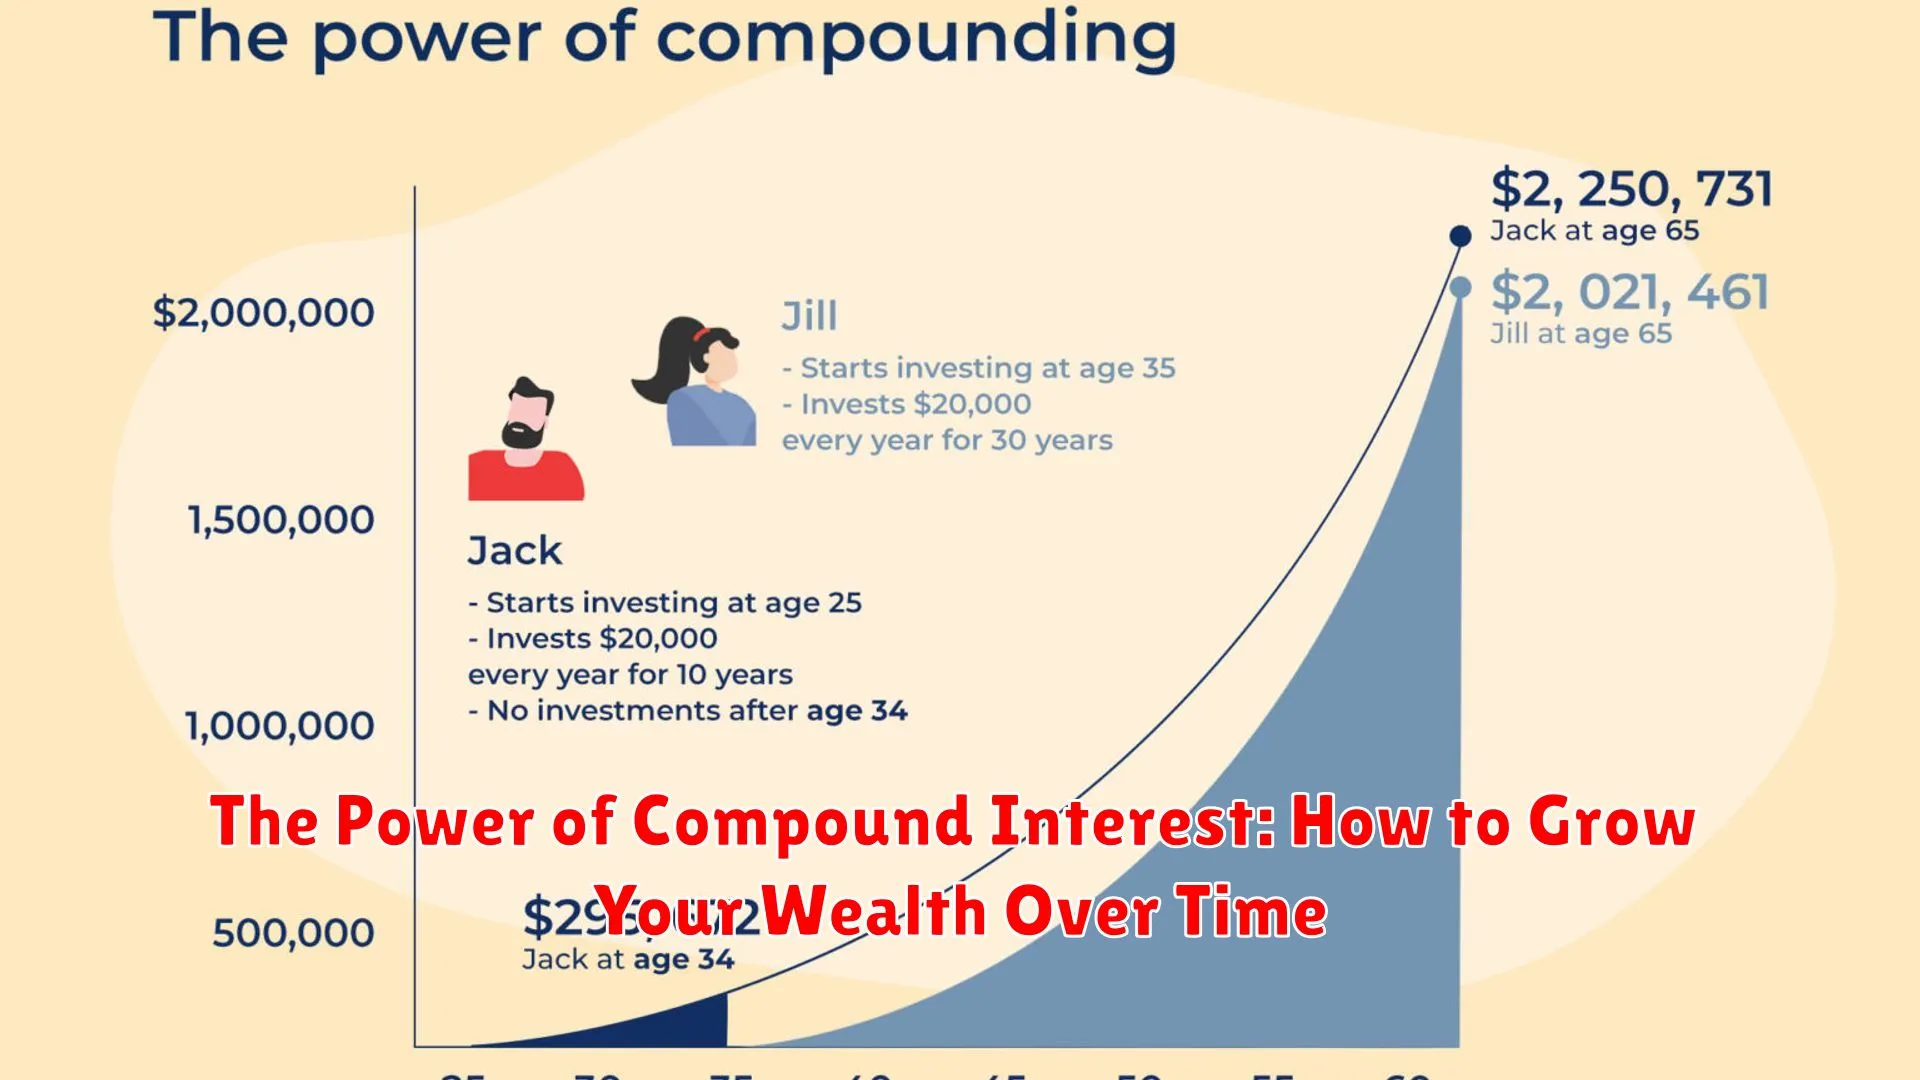
Compound interest is just interest on top of interest. You deposit money, it earns a rate, and next period you earn on the original plus the previous interest. That's literally all it is. Most people skip past this because they've already heard the motivational speeches. Here's the part nobody emphasizes enough: the timing of your contributions changes the result more than the rate does in practice. I worked with a client last year who had two portfolios. One person started at 25, investing $500 a month. The other started at 35, investing $1,000 a month. By age 55, the later starter actually had more money in the account because they doubled the contribution. Compounding rewards time, but it also rewards capital. Both matter, and most calculators you find online don't make that tension visible without you manually adjusting inputs several times.
Unlock The Power Of Compound Interest How Investorgovs Calculator Can Help You Grow Your Wealth
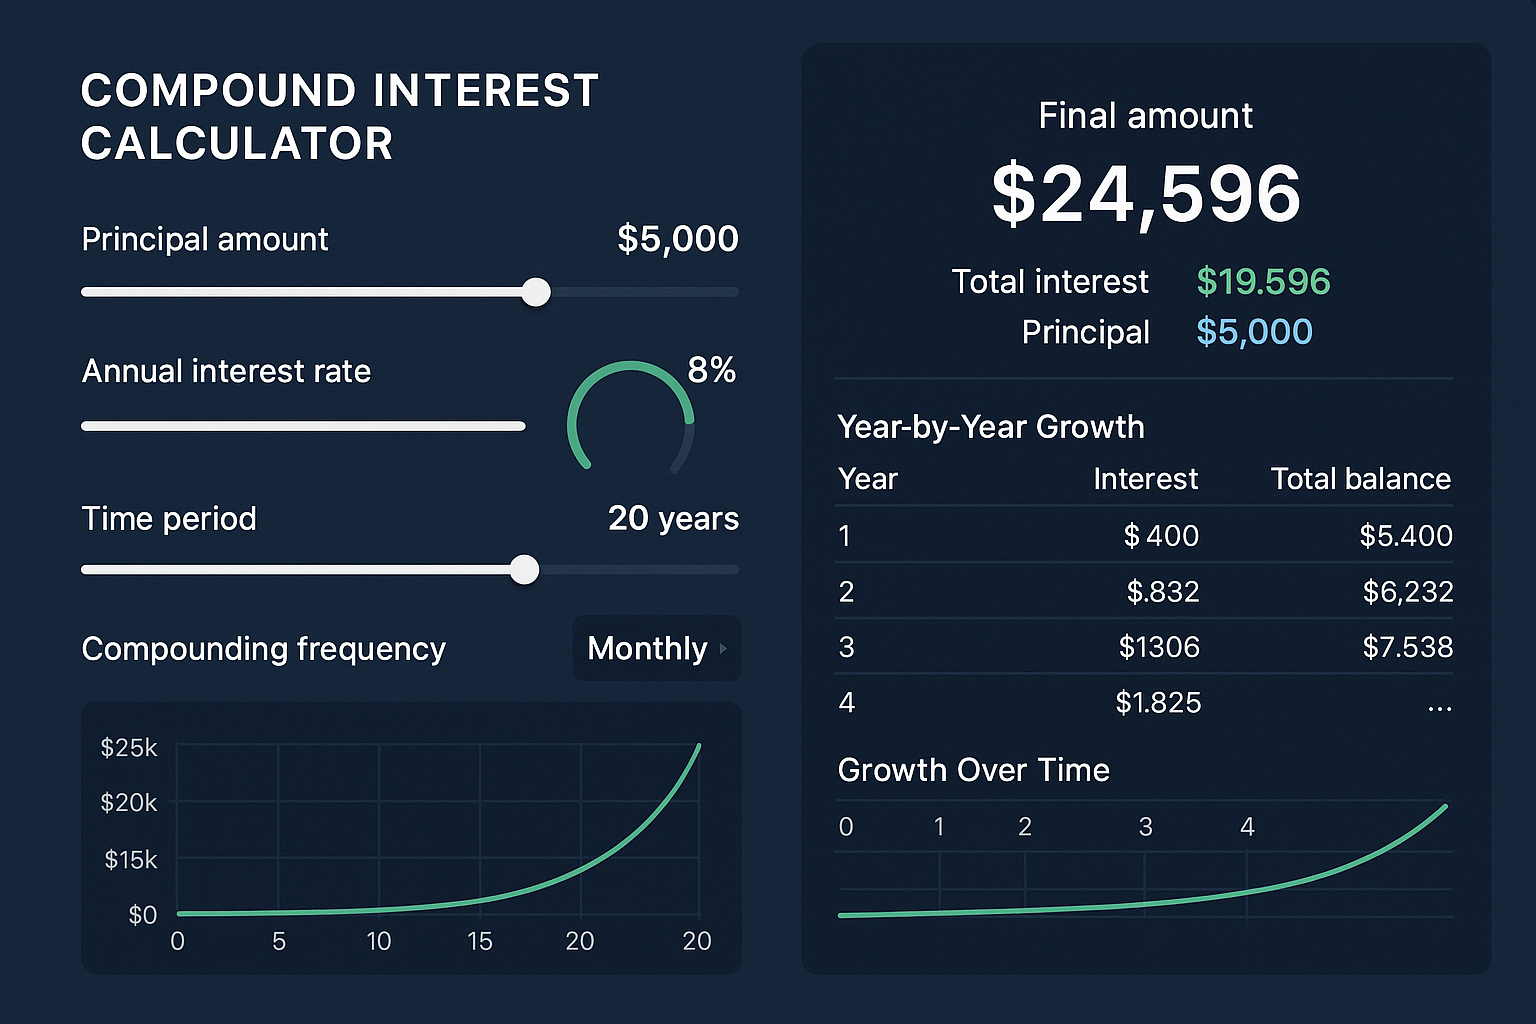
The Investorgovs compound interest calculator works the same way every standard tool works: you plug in a starting amount, a monthly or annual contribution, an expected rate, and a time horizon. It applies the standard formula and gives you a projection. Where it differs from the generic spreadsheet template your accountant sent you three years ago is that it defaults to showing the breakdown between principal and interest earned each year. That breakdown is useful because it tells you when compounding actually starts doing the heavy lifting. In my experience, the most frustrating edge case with these calculators is how they handle intra-year compounding frequency versus contribution frequency. Most people enter a monthly contribution and a daily compounding rate without realizing the math assumes the contribution goes in at the beginning of each period. If your actual contributions happen at the end of the month, you're going to be off by roughly half a period's worth of interest on each deposit. Over twenty years, that difference can be thousands of dollars depending on the rate. The workaround I use is simple. I enter the contribution as if it arrives at the beginning of the month, then I run a second calculation with a slightly higher rate offset—about 0.1 to 0.2 percent lower in the input—to approximate the end-of-month timing. It's not perfect, but it closes the gap enough for planning purposes. For exactness, you should build a cash flow schedule in a spreadsheet where you model each deposit date against the actual compounding periods. That takes about twenty minutes for a ten-year horizon, and it catches discrepancies like this.
The Practical Mechanics You Need to Know Before You Trust Any Projection
Let's look at the core mechanics without the sales pitch. The formula behind compound interest is A equals P times one plus r over n, all raised to n times t, where P is principal, r is annual rate, n is compounding periods per year, and t is years. When you add recurring contributions, the math becomes a geometric series, which is why calculators exist. Doing this by hand is tedious and unnecessary unless you're auditing someone else's numbers. Here is a realistic scenario. Say you start with ten thousand dollars, contribute five hundred each month, and expect an eight percent annual return compounded monthly. Over thirty years, the calculator will show a final balance somewhere near seven hundred fifty thousand dollars. The interest portion will be roughly six hundred fifty thousand. That means only about twelve percent of your total is from your own contributions. The rest is compounding doing what it does. Now here's the part that trips people up. If you switch to a six percent return, the final number drops to around four hundred eighty thousand. The difference is almost three hundred thousand dollars. A two percentage point change in expected return creates a result gap that most beginners underestimate. That's why rate assumptions deserve scrutiny, not blind faith. An eight percent return is reasonable for a diversified equity portfolio over thirty years, but it is not guaranteed, and it certainly isn't available from a savings account.
Get the Full Details
When This Tool Actually Fails You
Compounding calculators assume a constant rate. Markets do not cooperate with that assumption. If you're using projections to plan for retirement or a major goal, you need to stress test against bear markets. I once had a student who projected a fifteen-year horizon with an average nine percent return. He didn't account for a sequence-of-returns risk scenario where the first five years delivered negative returns. His portfolio wouldn't have survived. The calculator showed he'd be fine. The reality was different because withdrawals during downturns lock in losses and leave less capital to recover. If your goal involves regular withdrawals, like in retirement, you should use a withdrawal calculator instead, or layer a sequence-of-returns analysis on top of the compounding tool. The Investorgovs calculator can help with accumulation phases, but it does not model variable market returns or inflation adjustments unless those options are explicitly provided. Check whether the tool allows you to input an inflation-adjusted rate. If it doesn't, you need to do that adjustment yourself by subtracting expected inflation from your nominal return before entering the rate.
How to Actually Use the Calculator Without Getting Misleading Results
First, decide whether your contributions are monthly or annual and set the compounding frequency to match. Monthly contributions with monthly compounding is the standard combination. Next, pick a rate that reflects your actual investment vehicle, not an optimistic benchmark. Use the after-fee return you expect, not the gross index return. Finally, run the numbers for multiple time horizons. A twenty-year projection looks very different from a thirty-year one, and seeing both helps you understand how much additional time is actually worth compared to adding more capital. I usually run three scenarios: a conservative estimate using four percent, a moderate estimate using six percent, and an aggressive estimate using eight percent. The range between them tells you how sensitive your plan is to market performance. If the gap between conservative and moderate is larger than you're comfortable with, you either need to extend your time horizon, increase contributions, or adjust your asset allocation toward something with a higher expected return. There is no harm in downloading or bookmarking tools like the Investorgovs calculator. It is a straightforward utility. The value comes from how you use it and how honestly you fill in the inputs. Garbage inputs produce garbage outputs. That is the entire issue with compound interest projections, not a flaw in the tool itself.
What I Wish People Understood About Compounding Earlier
Compounding is not magic. It is arithmetic. But it is arithmetic that rewards patience and punishes interruption. Every time you withdraw from a compounding account during accumulation, you reset the growth curve. Every time you miss a contribution window, you lose the compounding effect on that specific amount for however many periods remain. The calculator shows you the ideal path. Real life rarely follows it exactly. I have seen people treat these projections as guarantees. They are not. They are estimates based on assumptions you control, mixed with variables you cannot control. The rate assumption is the biggest weak point. Contribution consistency is the second. Time horizon is the third, though time is generally the one variable you can control best if you start early enough. Use the calculator. Run the numbers. Check the edge cases. Adjust your assumptions until the projection feels aligned with realistic outcomes, not fantasy outcomes. Then build a plan that survives when those assumptions prove wrong. That is how you actually grow wealth, rather than just visualize it on a chart.