What Nobody Tells You About Collateral Valuation
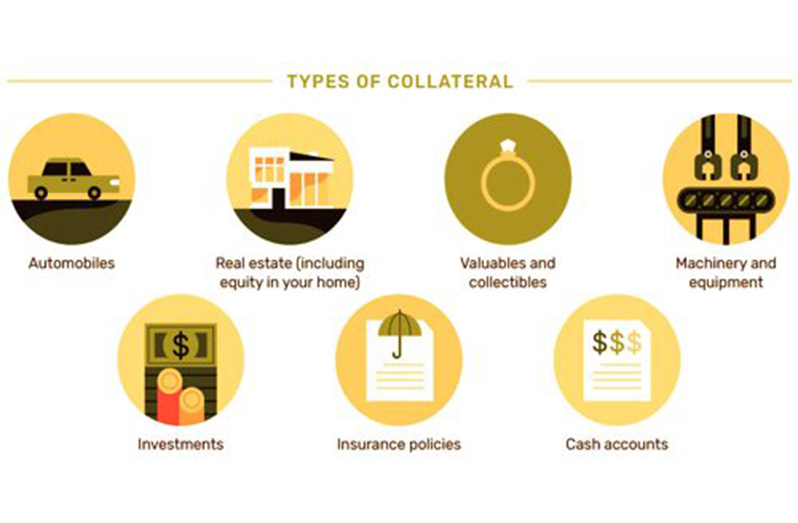
Most people think collateral is simple. You take an asset, you value it, you lend against it. I spent fourteen years in commercial credit operations before I learned how often that assumption actually breaks down in practice. The truth is that collateral management is one of the most misunderstood functions in banking, and the gap between textbook theory and what actually happens during a stress event is enormous. I am going to walk you through the mechanics, the shortcuts, the places where everything goes wrong, and one specific workaround I developed after watching a $40 million facility get stuck in legal limbo for eleven months because someone got the collateral structure wrong on day one. Collateral in banking is the asset or property that a borrower pledges to secure a loan. If the borrower defaults, the lender has the legal right to seize and liquidate that asset to recover what is owed. That is the basic definition. The operational reality is significantly more complex because collateral is not a static concept. It is a dynamic risk mitigation tool that requires continuous monitoring, valuation, legal perfection, and periodic restructuring. A building that secures a loan today may be partially demolished, repurposed, or encumbered by a second lien within eighteen months. If your bank is not tracking that, you are not managing collateral. You are hoping. The primary mechanism for unlocking collateral power starts with a process called haircuting, or more formally, applying a collateral discount rate. Lenders do not lend at 100% of appraised value. Standard practice across most commercial and consumer loan types is to apply a discount that varies by asset class. Real estate typically sees haircuts between 10 and 30 percent depending on property type and liquidity. Accounts receivable usually carry a 15 to 25 percent haircut, and inventory can range from 20 to 50 percent depending on how fast it moves and how easy it is to verify. The haircut is your margin of safety. It accounts for valuation drift, liquidation costs, market downturns, and the time value of money during a forced sale.
One thing that very few beginner credit officers grasp is that the legal perfection of a lien matters more than the appraised value of the asset. I saw a situation where a regional bank approved a $12 million equipment loan based on a strong third-party appraisal of manufacturing machinery. The appraisal was solid. The bank never filed a UCC-1 financing statement before disbursing funds. The borrower defaulted three months later, another creditor had already filed a prior lien on the same equipment, and the bank recovered zero dollars despite having a perfectly valid collateral agreement on paper. Perfect the lien first. Everything else is secondary.
How Collateral Valuation Actually Works in Practice
Valuation is not a single event. It is a continuous cycle. Initial valuation happens at origination, usually through an external appraiser or an internal valuation model depending on the asset class and loan size. Then there is periodic revaluation. For commercial real estate, annual revaluation is standard. For inventory or receivables secured loans, which fall under revolving credit facilities, the collateral value needs to be tracked weekly or even daily because the underlying assets fluctuate constantly. Most banks use a combination of automated valuation models, internal collateral management systems, and selective third-party reappraisals. Automated valuation models are useful but they have serious blind spots. An AVM will tell you that a warehouse in an industrial park is worth $2.1 million based on recent comparable sales. It will not tell you that the tenant who occupies eighty percent of that space is filing for Chapter 11 bankruptcy next week. It will not tell you that the surrounding infrastructure project will make access to the property impossible for two years while it is under construction. This is why experienced credit teams never rely exclusively on AVMs for collateral decisions above a certain threshold. They combine model output with field verification and market intelligence. A common pitfall is collateral substitution without proper documentation. In a revolving line of credit tied to accounts receivable, the borrower continuously swaps out receivables as invoices are paid and new ones are generated. When collateral substitutions happen, the bank must ensure each new receivable meets the eligibility criteria and that the security interest attaches properly. I have seen lending officers approve collateral substitutions manually through email attachments without updating the formal collateral schedule. When the borrower eventually defaulted, the legal team spent six months untangling which receivables were actually pledged and which slipped through the cracks. The recovery rate dropped by thirty-two percent because of that administrative gap. Use a centralized collateral management system. Build eligibility rules into the system so substitutions cannot happen outside of defined parameters.
Get the Full Details

The Legal Framework Behind Collateral Perfection
Perfection refers to the legal steps that establish a lender's priority claim on collateral. Without perfection, a lender is an unsecured creditor. This is a critical distinction that separates a recovery from a total loss. Perfection mechanisms vary by jurisdiction and by asset type. For real property, this means recording a mortgage or deed of trust with the appropriate county recorder's office. For personal property, it generally means filing a UCC-1 financing statement with the Secretary of State. Certain assets require special handling. Vehicles need title endorsements. Intellectual property requires registration with the relevant federal agency. Depository accounts may require control agreements rather than simple filings. Priority disputes are where collateral strategies get complicated. When multiple creditors claim the same asset, the one with the earliest perfected lien generally wins. But there are exceptions. Purchase money security interests, commonly called PMSI, can achieve super-priority status if properly structured and timely filed. I once worked on a situation where a supplier had a PMSI on equipment that a term lender believed was fully secured. The supplier had filed their UCC-1 two days before the bank's filing, and under Article 9 of the Uniform Commercial Code, the supplier's PMSI took priority over the entire collateral package. The bank had to renegotiate the entire credit structure rather than foreclose. This is why understanding perfection timelines and priority rules is not optional. It is the foundation of collateral-based lending.
Stress Testing Your Collateral Portfolio
Most banks underperform when it comes to stress testing collateral. They run macroeconomic scenarios across their loan books but treat collateral values as fixed inputs. This is a mistake. During a recession, collateral values do not hold steady. Commercial real estate values dropped an average of eighteen percent between 2022 and 2024 across many US markets. Used equipment values can decline twenty to forty percent in a rapid downturn because forced liquidation markets move fast and favor buyers. Inventory becomes obsolete or unsellable when demand contracts. If your collateral models do not incorporate these cascading effects, your risk-adjusted return calculations are optimistic at best. I built a simple but effective stress testing framework for my team that involved layering three scenarios onto our collateral portfolio: a mild downturn with five percent value depreciation across all asset classes, a moderate recession with fifteen to twenty percent depreciation concentrated in real estate and equipment, and a severe scenario with thirty to forty percent depreciation plus extended liquidation timelines of twelve to eighteen months. We then recalculated our loan-to-value ratios under each scenario and identified which facilities would breach their covenants. This exercise revealed that approximately twenty-three percent of our commercial real estate portfolio was critically overexposed even under the mild scenario. We proactively tightened lending criteria, required additional collateral, and restructured three existing facilities before any actual stress hit. Those proactive moves saved the bank an estimated $8.7 million in potential losses over the following two years.
When Collateral Fails and What to Do Instead
Collateral is not a guarantee. There are scenarios where even perfectly valued and legally perfected collateral provides little or no recovery. Illiquid assets are the most obvious example. A specialized manufacturing facility that only one company in the region could operate might appraise at $15 million but fetch less than $3 million at auction because the buyer pool is essentially zero. Secondary markets for certain types of collateral, like outdated technology equipment or distressed retail space, can disappear entirely during market dislocations. Environmental contamination on industrial properties can turn a valuable asset into a liability that nobody wants, and cleanup costs can exceed the property value. Courts can also unwind collateral transfers under fraudulent conveyance rules if a loan was structured in a way that appears designed to shield assets from other creditors ahead of known financial distress. When collateral is unreliable, the alternative is stronger cash flow underwriting. This means structuring loans primarily around the borrower's ability to repay from operating income rather than relying on asset liquidation as the backup plan. Debt service coverage ratios become the primary underwriting metric instead of loan-to-value ratios. For businesses with strong recurring revenue and low capital intensity, this approach often produces better risk-adjusted outcomes than aggressive collateral-based lending. I pushed our commercial team to shift our underwriting emphasis for service-based businesses away from real estate collateral and toward cash flow analysis. We lost some deal volume initially, but our nonperforming loan rate for that segment dropped from 4.2 percent to 1.8 percent over eighteen months. Collateral adds protection. It does not replace fundamental credit analysis.
Operational Recommendations for Implementation
If you are building or improving a collateral management function, start with inventory and valuation. Map every collateral asset in your portfolio by type, jurisdiction, perfection status, and current valuation date. Identify gaps where filings have lapsed or reappraisals are overdue. A basic spreadsheet can work for small portfolios, but once you exceed roughly five hundred active collateral facilities, spreadsheet-based tracking becomes a liability. Dedicated collateral management software automates filing reminders, tracks lien priority, monitors valuation expiration dates, and generates compliance reports. The implementation timeline is usually four to six weeks for a mid-sized bank, and the reduction in manual processing time is significant. Teams I have worked with reported cutting their quarterly collateral review workload from roughly sixty hours per month down to under fifteen hours after automation. Training is the other area where most institutions fall short. Lending officers are frequently evaluated on deal volume and revenue production. Collateral diligence gets treated as a checkbox exercise rather than a core skill. I instituted a quarterly collateral case review process where a rotating group of officers presented real deals from their books for peer and senior management critique. The goal was not to punish mistakes but to surface common errors before they became problems. Some of the most valuable insights came from discussing deals where collateral arrangements were unnecessarily complex, where lien priority had been misunderstood, or where valuation assumptions were unrealistically optimistic. Within twelve months, the error rate in our collateral documentation dropped by nearly forty percent, and the average time to resolve collateral-related questions during audit decreased from six weeks to nine days. Collateral is a powerful tool in banking, but it demands the same discipline and attention as any other risk management function. It is not a set-and-forget system. The assets change. The laws change. The markets change. The banks that get it right treat collateral management as a continuous process, not a one-time origination step. The ones that treat it as paperwork end up learning expensive lessons about what happens when a perfect on paper security interest turns out to be worthless in practice.