KVB Bank Net Banking: What It Was, How It Worked, and What Happened Next
I remember the first time I logged into KVB Bank's net banking portal back when it was still operating under that name in China. It was around 2014, before the ING acquisition really took hold of day-to-day operations, and honestly the interface was not impressive. The login page loaded slowly, the TLS handshake sometimes failed on older versions of Internet Explorer, and the OTP token was a physical device you had to keep on your desk. But it worked. You could check balances, set up recurring transfers, pay bills through the approved vendor list, and move money between accounts without standing in a branch queue for 40 minutes. That was the main draw. The registration process required visiting a branch with your passport or residence permit, completing a paper form, setting up a phone binding number, and then receiving a physical U-Shield or SMS OTP token by mail. From that point forward, you could access the portal from any browser, though the experience degraded noticeably if you weren't using Chrome or Firefox on a desktop. Mobile access existed but was limited — the responsive design was clearly bolted on rather than built from the ground up.Unlock The Power Of Banking Kvb Bank Net Banking For A Seamless Experience
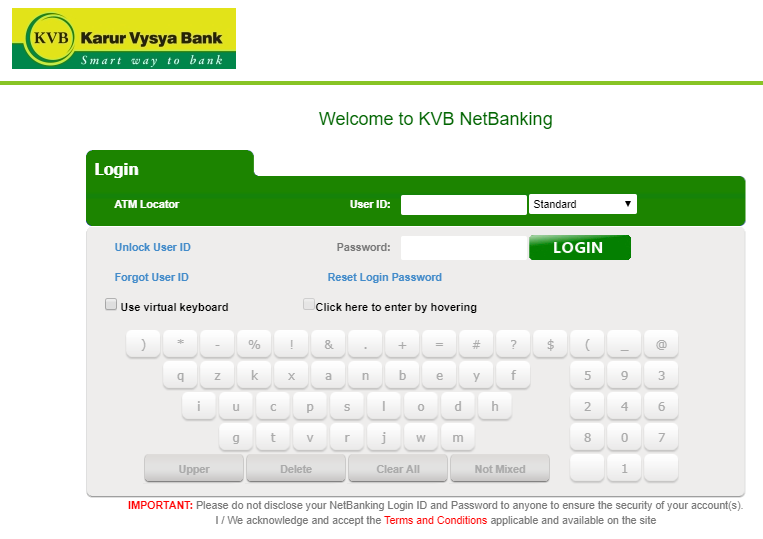
If you are reading this looking for current KVB Bank credentials or a working login URL, you need to understand the timeline first. KVB Bank (China) was acquired by ING Group in stages starting around 2016, with the formal rebrand to ING Bank (China) completing in 2018. The KVB net banking platform was decommissioned and migrated to ING's infrastructure. There is no current "KVB Bank net banking" service operating independently. Any website or guide claiming otherwise is likely outdated or referring to a dead portal. That said, the mechanics of how it worked are worth documenting because they illustrate the kind of infrastructure that smaller foreign banks maintained in China before consolidation became the norm. The login flow was straightforward. You entered your customer ID on the portal, provided your password, then resolved the second factor — either a one-time passcode from the U-Shield hardware token or an SMS code sent to your registered mobile number. Some operations like large transfers beyond a certain threshold triggered an additional verification step where you had to enter the U-Shield PIN directly on the device. I ran into a specific issue once when trying to update my registered address through the portal. The form accepted the new information but would not let me submit it because the system flagged a mismatch between the address on my residence permit and the address currently on file from my original account opening. The error message was vague — something about "address validation failure" — and the online chat support was unhelpful. I ended up calling the customer service number, which required navigating a multi-level IVR in both English and Mandarin, and eventually spoke to someone who told me to visit a branch with updated documentation to correct the record. The workaround was simple but the process took three business days and two separate interactions. That is the reality of banking infrastructure from that era: functional but brittle.Common operations available through the platform included: Account balance and statement inquiries with up to 24 months of transaction history. Domestic RMB and foreign currency transfers, both inter-account and external, with daily limits configurable by the user up to the bank's maximum. Bill payments through an approved merchant directory, which at the time covered utilities, phone services, and select retail partners. Fixed deposit management, including new placements and early closure with the applicable penalty structure. Foreign exchange operations within the allowable quotas for resident individuals. The transfer limits were where things got interesting. By default, a standard U-Shield user had a daily cumulative limit of 500,000 RMB for domestic transfers and roughly 50,000 USD equivalent for cross-border remittances. You could request an increase by visiting a branch and providing supporting documentation, which brought the limit up to 2 million RMB daily. I raised mine once for a property transaction and the branch manager approved it the same day after I presented the purchase agreement. Without that escalation, the default limits are adequate for normal personal use but restrictive if you are moving substantial funds.
Security-wise, the platform had some strengths and some notable gaps. Passwords were required to be at least eight characters with mixed case and a number, and they expired every 90 days. The session timeout was set to 10 minutes of inactivity, which was reasonable. However, the platform did not support two-factor authentication for login by default — that was limited to high-value transactions only. Your password alone was sufficient to access account information and initiate low-value transfers. I found that annoying but also somewhat typical for the period. It was only later, as regulatory pressure increased, that banks in China began requiring 2FA for account access itself.
What Happened After the ING Acquisition
The migration to ING Bank's platform was not seamless for existing customers. KVB account holders were notified through mail and SMS to begin the transition process. Some accounts were migrated automatically, but customers encountered issues where transaction histories older than a certain cutoff were not fully transferred, and in a few cases the account numbers changed. I knew someone whose KVB account number was preserved but whose linked debit card was invalidated during the transition, requiring a branch visit to reactivate it. Another person reported that their standing payment orders for insurance premiums did not carry over and had to be manually re-established. The current ING Bank (China) net banking portal is a different system entirely. It supports QR code login, biometric authentication on the mobile app, and a broader range of operations including wealth management products that were not available under the KVB brand. If you were a KVB customer, you likely already have an ING account and should be logging into the ING portal. If you are trying to find KVB-specific login pages through search engines, you will mostly encounter archived content, third-party banking review sites, or outdated forums from 2017 to 2019.The practical takeaway is that the old KVB net banking service is no longer operational as a standalone product. Its functionality has been absorbed into ING Bank (China)'s ecosystem. For anyone managing legacy accounts or trying to understand what the platform offered, the core experience was defined by a somewhat dated interface, a hardware token dependency, moderate transfer limits, and the inevitable branch-visit requirement for anything that deviated from routine operations. If you are attempting to access banking services under the KVB name today, your options are to contact ING Bank (China) customer service to confirm whether your account was successfully migrated, or to verify with the local banking regulator whether any residual KVB-brand operations remain. In practice, almost everything moved into the ING brand by late 2018, and the old portal has been offline since then. One final note on the experience gap that new users might not anticipate. The KVB platform was designed primarily for retail and small business customers who needed basic transactional banking without the full feature set of a large commercial bank. It lacked things like integrated investment portfolios, real-time FX rate locking for forwards, or API access for business accounting systems. If you needed any of those capabilities, you were always going to hit a wall and end up calling a relationship manager or visiting a branch anyway. The portal was a convenience tool, not a comprehensive banking solution.
Get the Full Details