What actually happens when you move 100 pesos across currencies
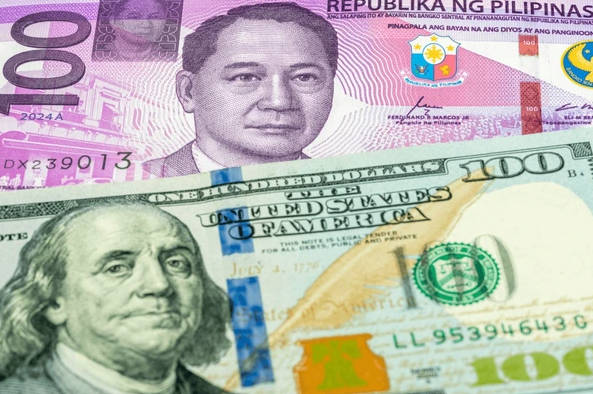
You type 100 PHP into a converter, hit go, and get some number like 1.78 USD. That is the surface level of it. The real mechanics involve spreads, intermediary currencies, fee layers, and the fact that the rate you see on a website is almost never the rate you actually receive. I have been doing cross-currency conversions for over a decade and the gap between quoted and executed rates still catches people off guard.
Unlock The Power Of 100 Peso To USD A Comprehensive Guide To Crosscurrency Trading
Here is how the process actually works from the ground up. You start with Philippine pesos and want US dollars. Most people do not realize that the USD/PHP pair is not always the most efficient route. In certain market conditions, especially during off-hours or when liquidity drops, the spread widens significantly. A better path sometimes goes through a major currency pair as an intermediary. You convert PHP to EUR or SGD first, then that currency to USD. The combined cost can be lower because you are tapping deeper liquidity pools in each leg.I ran into a specific edge case last year that illustrates this clearly. A client needed to move a small amount and insisted on going direct through their bank. The quote was terrible. I dug into the mid-market rate and found that routing through a Singapore dollar leg on a different platform actually saved about two percent. The workaround was simple: use a multi-currency account that lets you hold balances in three or four currencies, execute the PHP to SGD conversion on one venue and SGD to USD on another, then consolidate. It took maybe five minutes longer than a single conversion but the cost difference was real.
The mechanics behind the rate you see
Foreign exchange rates come in several flavors and mixing them up is where most beginners lose money. The mid-market rate is the pure benchmark with no markup. The ask price is what you pay to buy a currency. The bid price is what you receive when selling. The difference between them is the spread and it varies wildly depending on the currency pair and who is quoting you. For USD/PHP the spread on retail platforms typically runs from two to eight pips, but some services charge effectively twenty or thirty pips disguised as a poor exchange rate. Transaction fees are separate from spreads. Some remittance companies advertise zero fees but bake a wider spread into the rate. Others charge a flat fee per transaction and offer near-mid-market rates. You have to look at the total cost, not just one component. A flat five dollar fee makes sense for a large transfer but destroys value on a small 100 peso conversion. At that scale the fee represents a massive percentage of your principal.
Where people make mistakes
Get the Full Details
The biggest error I see is treating currency conversion as a one-time event rather than a process with timing considerations. Exchange rates move constantly throughout the day. If you are converting a small amount the fluctuations matter less in absolute terms but the relative impact of fees and spreads stays constant. Another common mistake is ignoring the settlement time. An instant conversion at a slightly worse rate is fine for small amounts but can be expensive for larger ones where waiting even a few hours could save meaningful money. There is also the issue of dynamic currency conversion, often called DCC. When paying internationally, merchants sometimes offer to charge you in your home currency instead of the local one. This sounds convenient but the exchange rate used is usually terrible. I have seen people lose three to five percent just by accepting the merchant's conversion option at checkout. Always decline DCC and let your own bank or payment provider handle the conversion.
Practical steps to execute a conversion
First, check the current mid-market rate on a reliable source like XE or OANDA. This gives you a baseline. Second, gather quotes from at least three providers. Include banks, digital remittance services, and specialized currency exchange platforms. Third, calculate the total cost including every fee and the final amount the recipient would get. Fourth, compare the effective exchange rate each provider offers against the mid-market rate. The difference tells you the true cost. For smaller amounts under a thousand dollars equivalent, digital platforms like Wise, Revolut, or LocalBitex tend to offer better rates than traditional banks. Banks mark up their spreads heavily on small retail transactions. They make their profit on the spread, not on fees, so even when fees are zero the rate itself is working against you. I typically recommend digital services for amounts in the one hundred to five thousand dollar range. Above that threshold, negotiating with your bank or using a dedicated FX broker becomes worthwhile.
When this approach does not work
Cross-currency trading through intermediary pairs is not a universal solution. It breaks down in several scenarios. If the intermediary currency has low liquidity against both your source and target currencies, the spread on one leg will eat any savings from the other. This commonly happens with exotic currency combinations. It also fails when transaction fees are high relative to the amount being converted. A two percent saving on the rate means nothing if you pay a ten dollar flat fee on a small transfer. Regulatory restrictions can also block certain routes. Some platforms do not support PHP directly, which forces you through yet another intermediary and adds friction. If your destination country has capital controls, the USD conversion might get stuck in compliance review for days. No amount of rate optimization matters if the money does not arrive on time. The most honest recommendation is to treat this as a practical framework rather than a magic solution. Check rates, compare total costs including all fees, avoid DCC, and understand that for very small conversions the math rarely favors complex routing. Sometimes the simplest path through a reputable digital service is the right one. The goal is not to find the perfect rate. It is to avoid the ones that are clearly worse than they need to be.