Commerzbank Jakarta And The Jakarta Economy
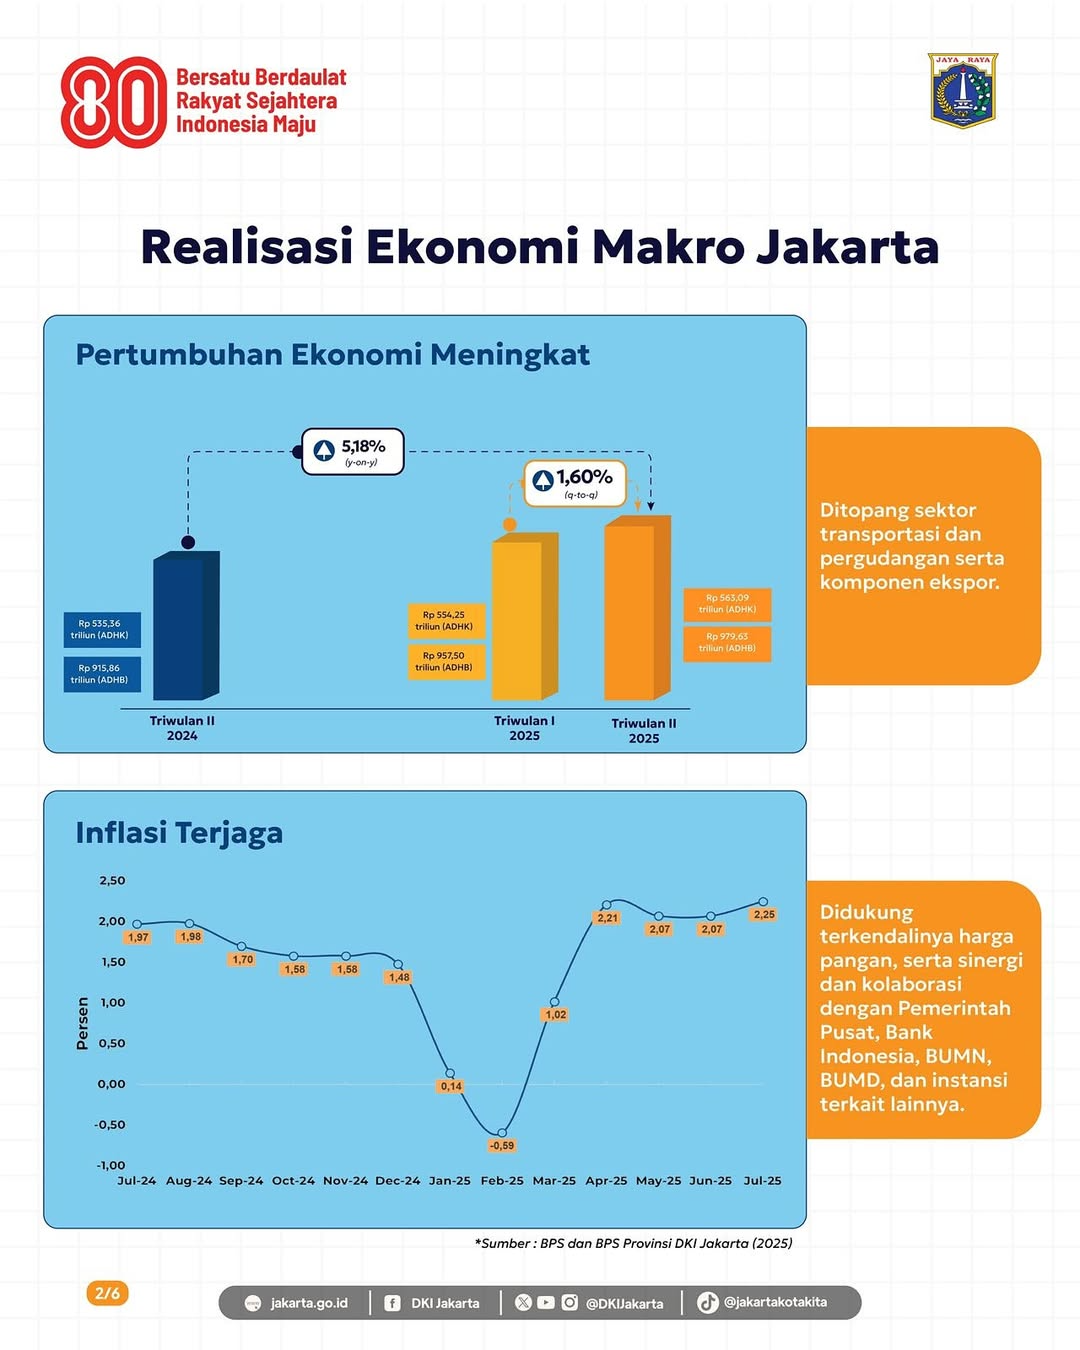
Commerzbank has a presence in Jakarta that most people driving through Sudirman don't even notice. The branch sits quietly in Plaza Indonesia or near SCBD, handling corporate and commercial clients. If you're looking at Indonesia from a banking perspective, this is one of the bigger German institutions operating here, and it's relevant if you're doing cross-border trade with Europe or need multi-currency infrastructure for a mid-sized business. I worked with a manufacturing client in Tangerang who needed to set up letters of credit for importing raw materials from Hamburg. The paperwork alone was painful. Commerzbank Jakarta handled the LC process, but the bottleneck wasn't the bank itself -- it was the documentation mismatch between Indonesian export rules and German banking requirements. We spent three weeks reconciling Incoterms 2020 clauses with what the bank's compliance team would actually accept. The workaround was getting the client's German supplier to agree to specific wording on the invoice before any paperwork was submitted. Without that pre-alignment, every LC application gets stuck in review for 10 to 14 business days instead of the standard 3 to 5. What makes Jakarta interesting as an economy right now is the gap between the official growth numbers and what's actually happening at the ground level in sectors like manufacturing, logistics, and digital services. GDP growth sits around 5 percent officially, but the real story is in trade finance activity, foreign direct investment inflows into special economic zones, and the rupiah's volatility against the euro, which directly affects anyone doing business with European counterparties.
How Commerzbank Jakarta Fits Into The Picture
The bank's main offering for businesses in Jakarta revolves around trade finance, treasury services, and working capital solutions. They're not trying to be a consumer bank here. If you're a small shop in Pasar Baru looking for a personal loan, go somewhere else. This is for companies moving money across borders, managing currency exposure, and handling the kind of transactions that require actual banking relationships rather than an app download. Their corporate lending desk has been active in financing for the industrial sector, particularly clients involved in export-oriented manufacturing. I've seen their credit terms compete with DBS and Standard Chartered on similar deals. The interest rate spreads aren't dramatically different, but the real variable is how fast they move on documentation and whether their compliance team actually understands Indonesian regulatory requirements or just runs everything through a generic ASEAN template. Here's something most guides won't tell you: Commerzbank Jakarta's relationship with the Bank Indonesia reporting framework is tighter than their public materials suggest. They have internal systems for autoprocessing certain cross-border payment reports that most local banks still handle manually. If you're processing high-volume intercompany transfers between your Jakarta office and a European parent company, this automation can save you roughly 4 to 6 hours per week of compliance staff time. The trade-off is that your transaction patterns need to be clean and consistent. Any unusual spike or irregular beneficiary triggers manual review, and that kills the efficiency gain completely.
Opening An Account There
The process takes longer than you'd expect from a European bank. You're looking at 3 to 6 weeks for a corporate account, depending on your company structure and whether you have existing Indonesian tax identification (NPWP). The documents required include the standard corporate filings, beneficial ownership declarations, projected transaction volumes, and references from your current banking relationships. The NPWP issue is where most foreigners and new businesses get stuck. If your company doesn't have one yet, you need to get it from the Directorate General of Taxes first, which adds another 2 to 3 weeks to the timeline. I had a client who tried to open an account with an old NPWP from a previous business entity. The bank's system rejected it because the NPWP didn't match the current company structure. We ended up having to apply for a new one and restart the account process. That cost them about 5 weeks total instead of the 3 they were expecting.
Get the Full Details
Trade Finance Capabilities
This is where Commerzbank Jakarta actually earns its keep. Letters of credit, documentary collections, guarantee issuance, and supply chain financing. The LC process for imports into Indonesia through them typically takes 5 to 7 business days from document submission to issuance, assuming everything is in order. For exports, they offer pre-shipment financing against confirmed LCs, which can free up working capital while you're waiting for goods to ship. The counter-intuitive part that nobody mentions: Indonesian import LCs through German banks face less scrutiny from EU-side compliance than you might think, but they face more scrutiny from Bank Indonesia on the Indonesian side. Specifically, the Lartas (larangan dan pembatasan) import restrictions list changes frequently, and your bank's compliance team needs to verify that the HS codes on your LC match whatever the current restrictions allow. I've seen LCs held up for days because a single line item on an invoice had a slightly wrong HS code classification. The workaround is getting your customs broker to verify HS codes before the LC is drafted, not after.
FX And Treasury Services
Rupiah volatility is a real problem for businesses doing regular EUR/IDR transactions. Commerzbank Jakarta offers forward contracts and options, but their FX pricing on the IDR side isn't the most competitive in the market. You'll typically get a wider spread compared to local banks like BCA or Mandiri on straightforward spot transactions. The advantage shows up on more complex structures -- layered forwards, collar strategies, or multi-currency cash pooling arrangements across your regional operations. If you're doing simple weekly EUR payments to suppliers in Germany, a local Indonesian bank might actually give you a better rate. But if you have revenue coming in from multiple Asian markets and need to convert everything through IDR to a consolidated account in Frankfurt, the treasury infrastructure and netting capabilities become valuable. The setup time for a cash pooling arrangement is typically 4 to 8 weeks and requires approval from both the Indonesian and German regulatory sides.
What It Actually Feels Like Working With Them
The staff at the Jakarta branch are generally competent but overloaded. Turnaround times are reasonable for standard requests but deteriorate quickly during peak periods or when regulatory changes hit. I've experienced cases where a straightforward guarantee amendment sat in queue for 10 business days because the relationship manager was reassigned to another client without proper handover. The key is building a direct line to someone who actually knows your file, not relying on the general inquiries channel. Digital banking through their platform works for routine transactions but is nowhere near as polished as what you get from digital-first banks. The interface is functional but dated. For anything beyond simple payments and balance checks, you'll still be picking up the phone or walking into the branch.

The Downsides Nobody Talks About
Commerzbank Jakarta has real limitations. Their deposit rates for corporate accounts are not competitive with local banks. If you're holding significant IDR balances and looking for yield, you're leaving money on the table. Their credit approval process for SMEs is slower than competitors, often requiring credit committee approval that adds 1 to 2 weeks to decisions that other banks would make in 3 to 5 days. And their customer service response times vary wildly depending on which relationship manager you're assigned to. For smaller businesses that don't need heavy trade finance or complex treasury solutions, going with a local bank like BCA, Mandiri, or even DBS Singapore with an Indonesian presence might be more efficient. The paperwork is faster, the digital tools are better, and the relationship management tends to be more responsive. Commerzbank Jakarta is worth considering primarily if you have substantive cross-border operations with Europe, need sophisticated trade finance structures, or already have an established relationship with the Frankfurt headquarters.
Bottom Line
Jakarta's economy is growing, trade finance activity is increasing, and foreign banks continue to compete for corporate clients. Commerzbank Jakarta is a legitimate player in this space with real capabilities, but it's not a one-size-fits-all solution. Evaluate your actual transaction volume, your currency exposure, and how much you value European banking infrastructure versus local agility. The banks that win in Jakarta right now are the ones that understand that speed matters as much as reliability, and Commerzbank is still catching up on that particular balance.