Understanding USAF Compensation: A Practical Guide
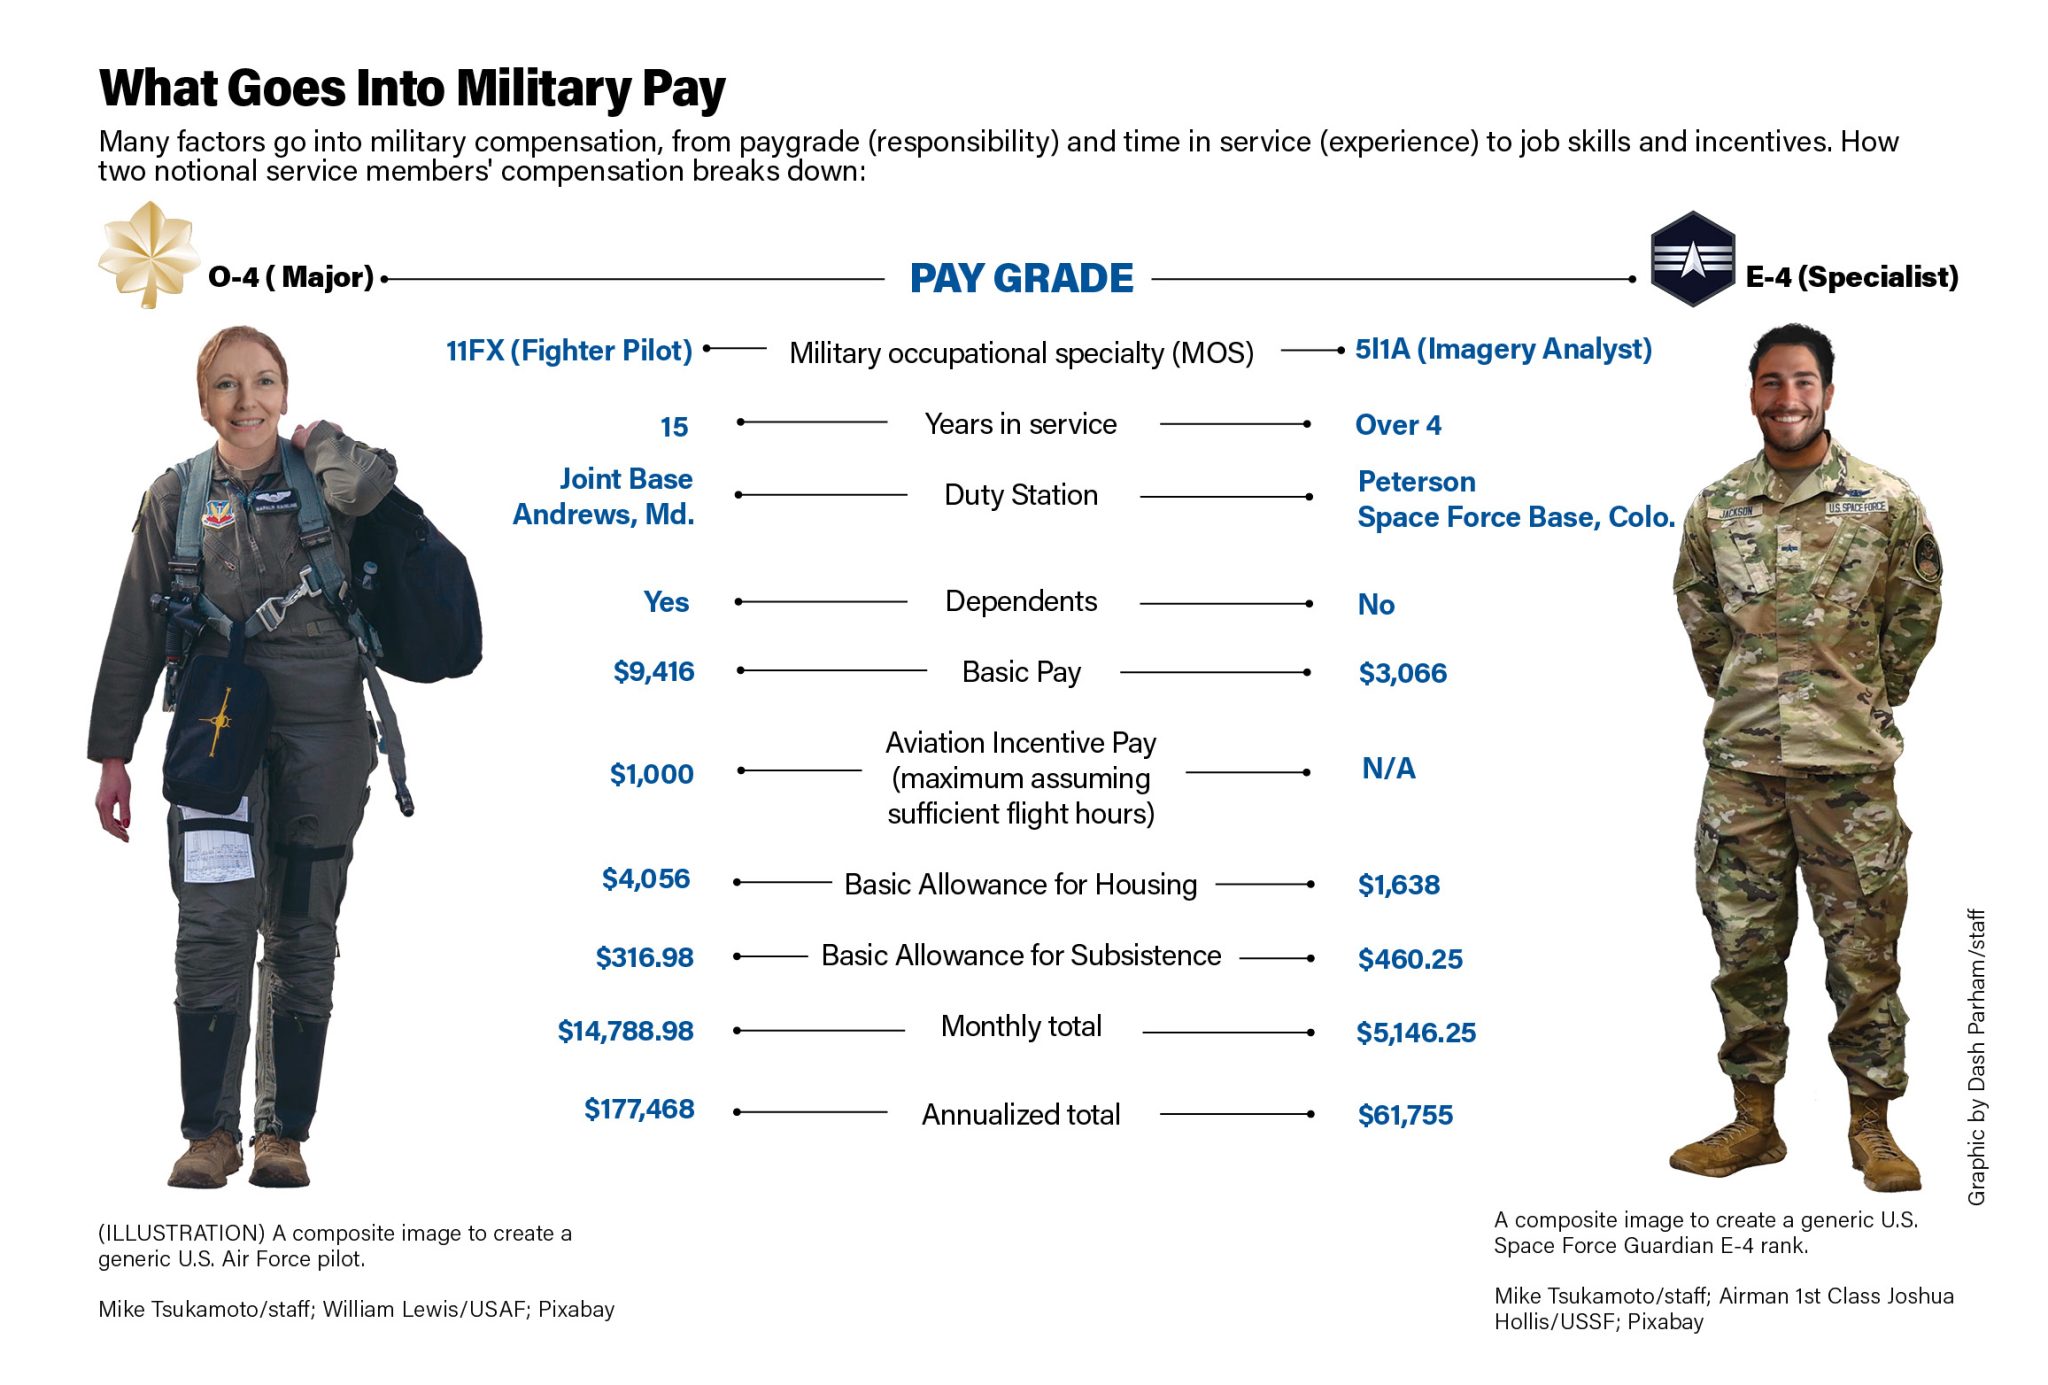
I spent about six years working through military finance systems before I stopped trying to memorize every pay table and started just knowing where to look. The system isn't broken, but it's also not intuitive if you've never worked in defense administration. People get confused about base pay, allowances, and the various benefit programs because they're managed by different departments and updated on different schedules. You're basically dealing with three separate budget streams that sometimes overlap and sometimes contradict each other if you're not paying attention. The core of USAF compensation comes down to basic pay, which is determined by rank and time in service, plus several allowances that aren't taxed. Basic allowance for housing covers your quarters, and basic allowance for subsistence handles your meals. These change based on whether you have dependents, where you're stationed, and your current pay grade. Then there's the special and incentive pays that apply to certain jobs or situations. A pilot gets flight pay, a recruiter gets commission pay, someone deployed to a hostile area gets hostile fire pay. None of this is automatic. You often have to apply or get certified for these programs.
Unlock The Future Of Military Finance Master Usaf Pay And Benefits Today
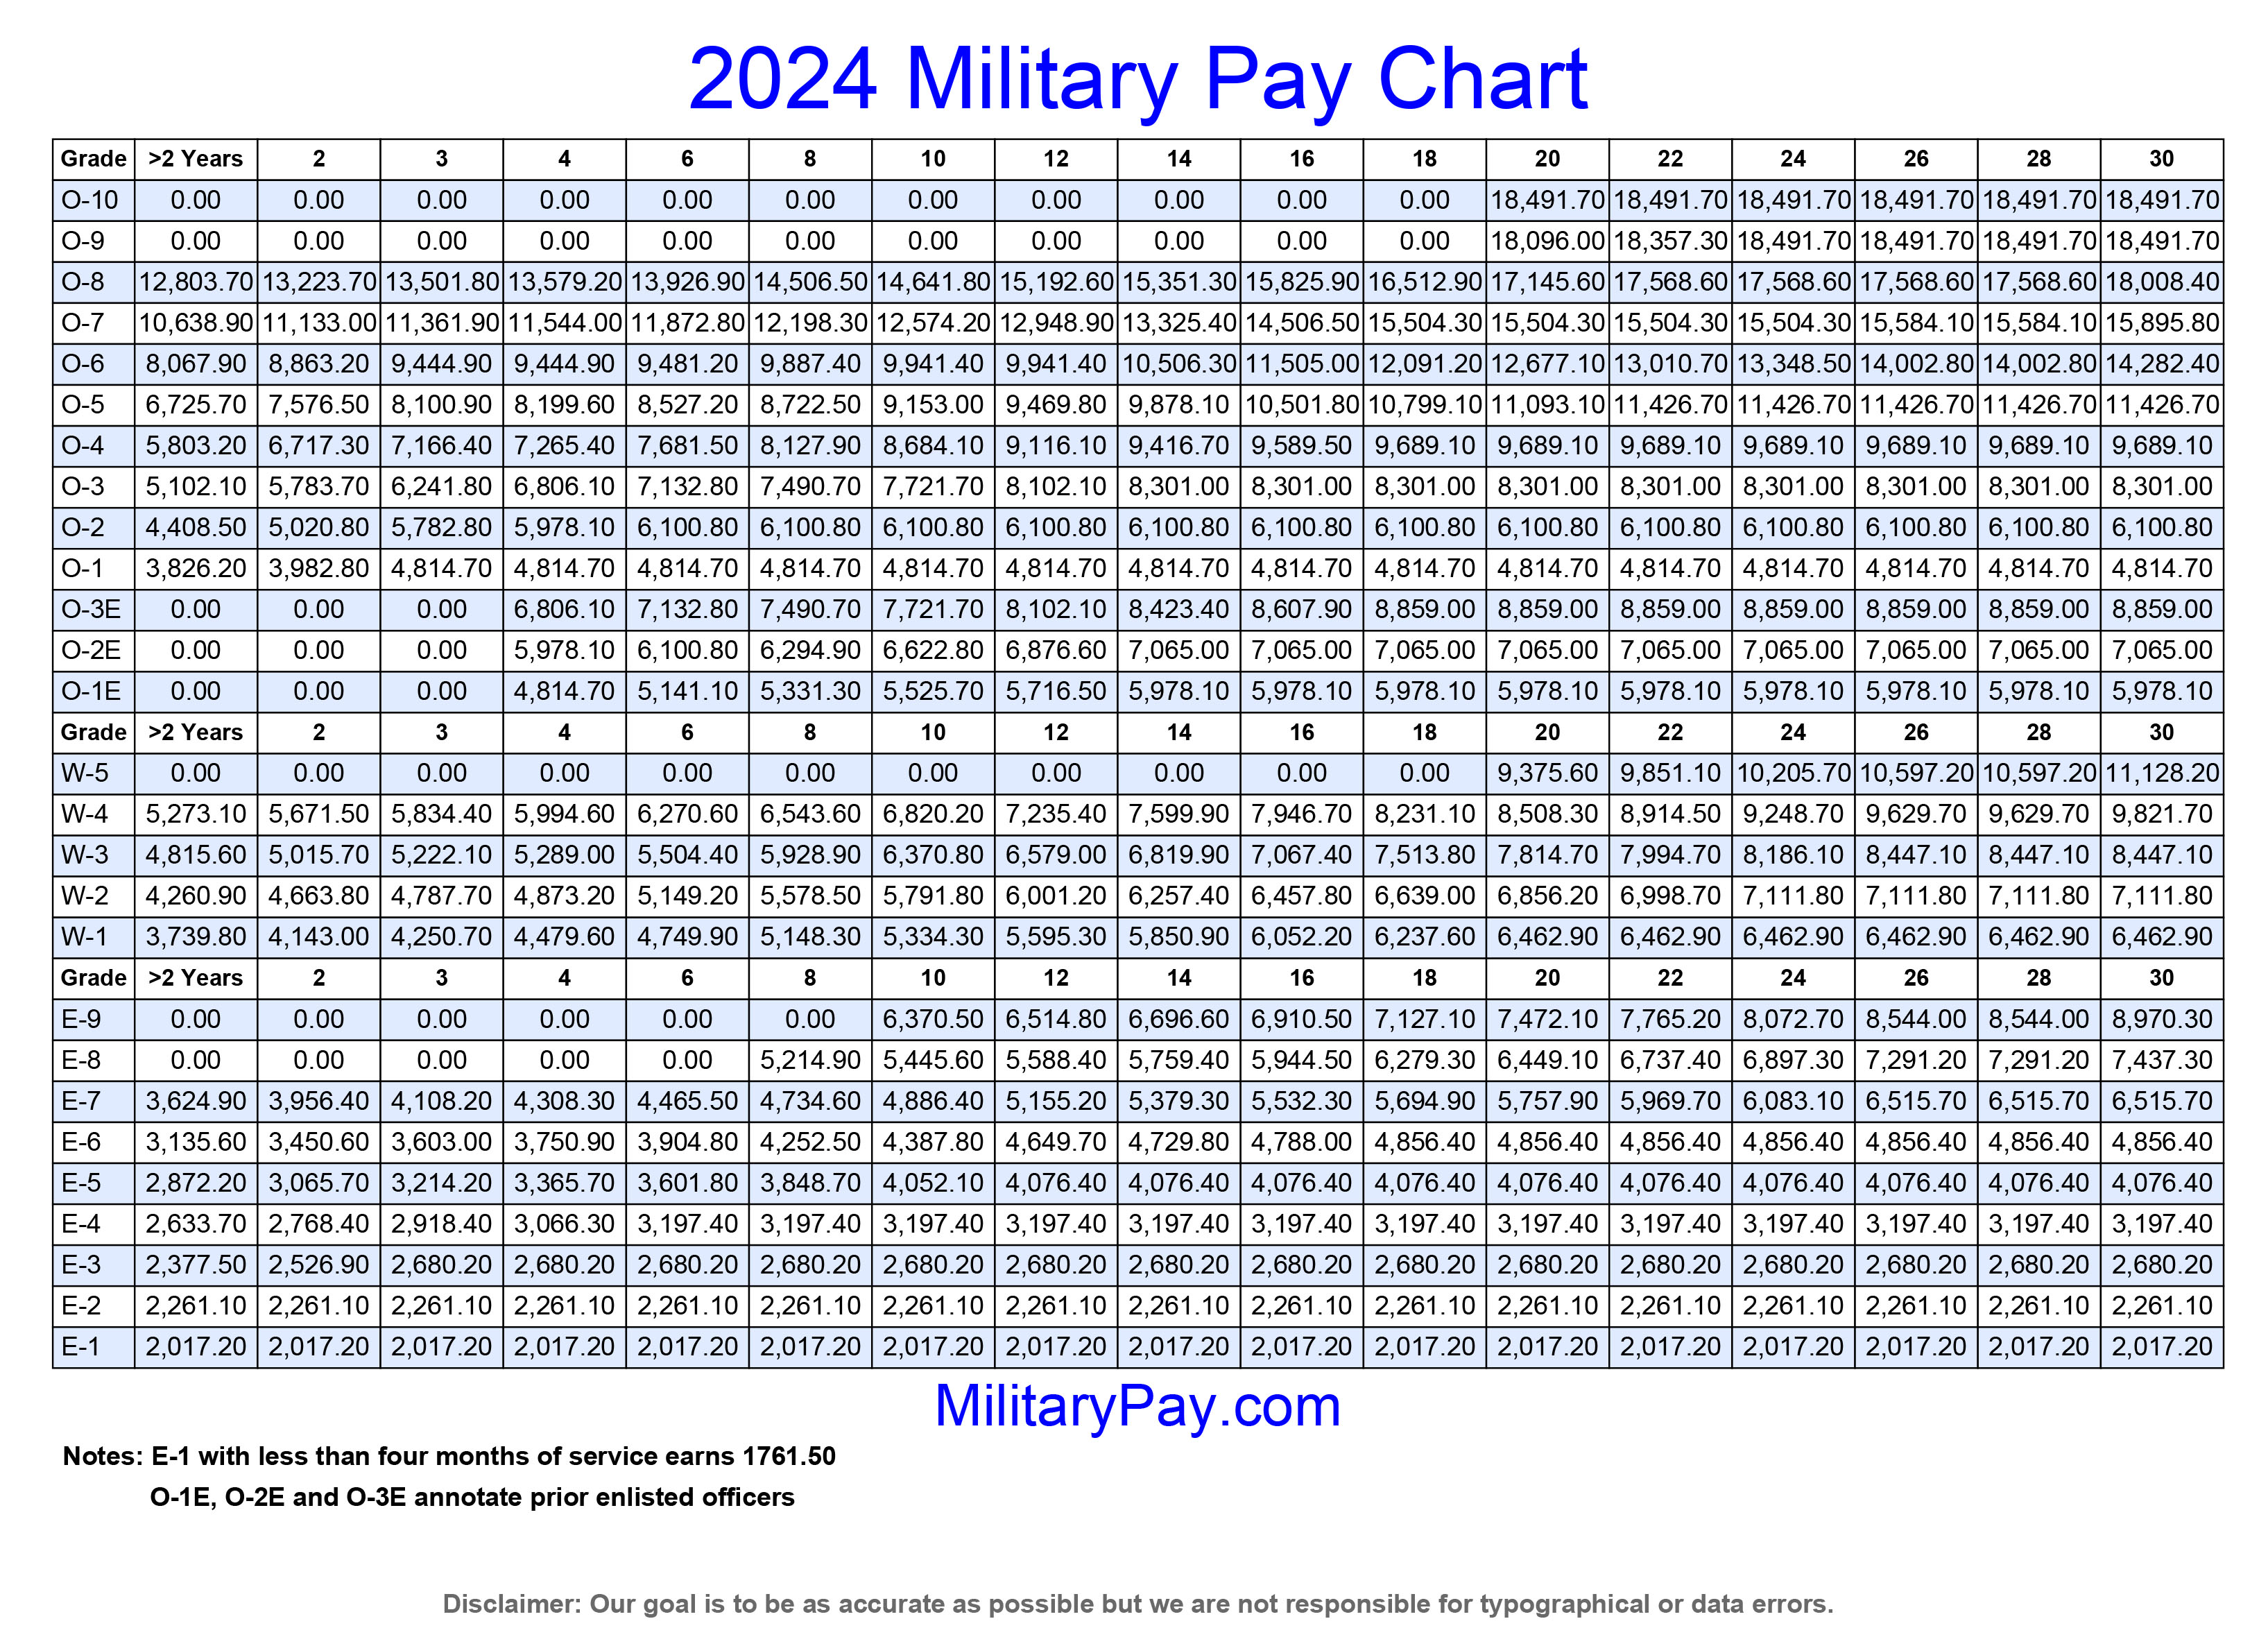
Here's where most people make mistakes. They look at their first leave and earnings statement and think they understand the system. A basic E-4 with twenty-four months gets roughly $2,500 a month in basic pay before taxes, plus whatever housing and subsistence allowances apply to their situation. That sounds like a lot if you're coming straight from civilian life and haven't had your taxes withheld for the first time. Then deployment starts, or you get a PCS move, and suddenly your paycheck looks completely different. The tax situations change depending on where you're assigned, and housing allowances can shift dramatically between high-cost and low-cost areas. I ran into this exact problem with a junior officer who thought she was being underpaid because her BAH changed after a transfer. She'd signed orders to a base in a higher cost-of-living area and expected her housing allowance to increase automatically. It doesn't work that way. The Defense Finance and Accounting Service updates these based on annual cost-of-living data from the military housing offices, and there's usually a lag of several months between when the data changes and when your check reflects it. She filed a formal inquiry through myPay and ended up getting about four months of back pay because the system had miscalculated her location code during the transition. The workaround was straightforward once someone explained the discrepancy timeline, but it cost her nearly a year of chasing it because she didn't know the right form to file. Healthcare is another area that confuses people. The Tricare system has multiple tiers depending on your status. If you're active duty, you're on Tricare Prime with minimal out-of-pocket costs. Spouses and children fall into the same category. Once you retire, you transition to Tricare Reserve Select or become eligible for standard Tricare at age sixty-five. The key thing most people miss is that while you're on active duty, your coverage continues for about eighteen months after separation if you're transitioning without immediate civilian health insurance. This is the Temporary Extended Health Coverage program, and it's automatic if you're separating under qualifying conditions. You don't have to apply separately, but you do need to verify your enrollment through the Defense Enrollment Eligibility Reporting System before your separation processing completes.
Retirement calculations are where the system gets genuinely complicated. The old system based your pension on your final base pay multiplied by years of service and a percentage factor. The new High-36 system works differently, and you can't choose between them retroactively. Someone who enlisted before 2018 and stayed past September 2024 now has to decide which plan applies to their final creditable service. I had a case where a chief master sergeant with thirty years assumed he was locked into the legacy plan because he'd been in since 1995. He wasn't. The transition provisions let him elect the new system if it produced a better outcome, but he had to submit the election form within a specific window after the policy took effect. Missing that window meant he was stuck with whichever plan the system auto-assigned, and in his case it actually reduced his projected retirement pay by about twelve percent. The GI Bill is another benefit people misunderstand. The Post-9/11 GI Bill isn't the same as the original Montgomery Bill, and you can't use both simultaneously for the same period of attendance. Some people try to stack them or assume they can convert between programs without checking eligibility. The truth is that your entitlement depends on your aggregate active duty service, and certain types of service like reserve time may count differently than active duty. A reserve member with six years of service might only qualify for fifty percent benefits if they haven't completed the required active duty threshold. The conversion options exist but have strict limitations, and using the Yellow Ribbon Program requires your school to participate in it specifically. Education benefits through the Air Force itself deserve separate attention. The Tuition Assistance program covers up to one hundred percent of undergraduate tuition at accredited institutions, but you have to get command approval before you enroll. This isn't something you can do retroactively. I worked with someone who took a college course on TA funding, got a good grade, and then tried to reimburse herself after the fact. The finance office rejected the claim because the approval wasn't on file before the semester started. The workaround is simple but requires discipline. You request TA through the MyEFMP portal at least thirty days before the term begins, get the approval number, and submit it to your school's certifying official before the add-drop deadline passes. If you miss that window, you're paying out of pocket and hoping for reimbursement later, which the system doesn't always honor.
Get the Full Details

Savings and investment options available through military service are frequently overlooked. The Thrift Savings Plan works like a civilian 401k but with different contribution limits and employer matching structures. Active duty members get automatic five percent contributions from the government if they contribute at least five percent of their base pay. That's essentially free money you'd be foolish to leave on the table. The catch is that you can't access these funds without penalty until you separate or reach retirement age, except through the new SGLI options that allow partial withdrawals under specific hardship conditions. A young Airman who treats TSP as their primary retirement vehicle while also contributing to a Roth IRA often ends up with better tax diversification than someone who only focuses on one account. Life insurance is mandatory for all active duty members through the Servicemembers' Group Life Insurance program. The default coverage is one hundred thousand dollars or your annual base pay, whichever is greater, but you can increase it up to half a million dollars if you meet the underwriting requirements. Death gratuity payments go to your designated beneficiary and aren't subject to income tax. I encountered a situation where a service member designated his mother as the primary beneficiary but never updated it after getting married. When he died in a training accident, the Navy judge advocate general's office had to get involved because his spouse had a legal claim to the proceeds despite the designation on file. The lesson is that you should review your beneficiary designations every time your family situation changes, not just when you first enter service. The Veterans GI Bill transferability rules are particularly strict. If you're currently on active duty and want to transfer your education benefits to your spouse or children, you must have at least six years of service remaining and certify that you'll serve four additional years. This isn't discretionary. The system denies transfers automatically if you're within four years of retirement unless you have special waiver authority from your service secretary. I helped someone who was three years from retirement and wanted to transfer benefits to his daughter. The automated system rejected his request, and he assumed it was a clerical error. It wasn't. The four-year service obligation requirement is hard-coded into the Defense Manpower Data Center system, and the only workaround is requesting a waiver through your service's personnel office, which requires demonstrating exceptional circumstances or critical skill retention needs.
Relocation assistance during PCS moves is another benefit people don't fully utilize. The government covers your move costs, but the per diem rates for temporary lodging during transit are based on General Services Administration rates that vary by location and season. Someone moving from Texas to Hawaii during peak travel season might find their allowable lodging expenses fall short of actual costs. The recommendation to use government-contracted moving services helps, but it doesn't solve the per diem gap. I found that filing a meal expense claim through the Defense Travel System with proper documentation often recovers a portion of the shortfall, though the approval process can take three to four months and requires receipts for every meal over a certain threshold. The paperwork burden is real, and many people abandon the claim rather than spend hours assembling documentation. Tax situations for military members are surprisingly variable depending on your assignment. If you're stationed in a combat zone or designated hostile fire area, your income is tax-exempt while you serve in that location. This includes base pay, bonuses, and most allowances. However, if you receive supplemental income from a side business or investment activity, that income remains taxable regardless of your duty station. I worked with a technical sergeant who ran a small online consulting business while deployed to an overseas combat zone. He assumed all his income was tax-free and didn't file quarterly estimated payments. When he returned stateside, the IRS flagged his omission, and he owed approximately fourteen thousand dollars in back taxes plus penalties because his self-employment income never received the combat zone exclusion. The Survivor Benefit Plan deserves careful consideration before you separate. It provides a monthly annuity to your designated beneficiary after your death, calculated as a percentage of your retired pay. The cost is roughly six to seven percent of your elected annuity amount, deducted monthly from your retirement check. Some retirees skip SBP to save money, assuming their spouse will be fine without it. That's a risky assumption if your spouse isn't covered by another pension plan or isn't employed full-time. I had a case where a colonel with thirty-two years elected no survivor coverage to maximize his monthly retirement income. His spouse outlived him by nine years and had no income source other than his social security survivor benefit, which was roughly sixty percent of his retired pay. The math worked out poorly compared to what SBP would have provided.
Health care for retired members transitions at age sixty-five, but the coordination between Tricare and Medicare requires proactive management. If you're retired before sixty-five and eligible for Medicare, you can enroll in Tricare for Life, which acts as secondary coverage to Medicare. This eliminates most out-of-pocket costs for covered services, but you must pay Medicare Part B premiums unless you qualify for a premium-free exception based on your work history or your spouse's record. A service member who retires at fifty-five and doesn't enroll in Medicare Part B when first eligible will face late enrollment penalties that last for the remainder of their life. The penalty is ten percent of the standard premium for each twelve-month period you were eligible but didn't enroll, and it compounds annually. Disability compensation through the Department of Veterans Affairs is separate from military retirement and operates on a different calculation system. If you retire with a disability rating of fifty percent or higher, your VA compensation offsets your retired pay dollar-for-dollar under concurrent receipt provisions. This means you receive full retirement pay plus full VA disability compensation without the old rule that required choosing one or the other. The qualification process requires medical documentation from military treatment facilities and often independent examination through the VA system. I assisted someone who was diagnosed with tinnitus and back injuries during service. His unit commander initially suggested he wait until separation before filing a VA claim, which is bad advice. Filing while still on active duty allows the VA to establish an effective date based on when you submitted the claim, potentially backdating your compensation to months before your separation. Waiting until after you leave means losing that benefit period. The Air Force Long-Term Care Insurance program is frequently underutilized because members assume they'll never need it or that Tricare will cover it. Neither assumption is correct. Tricare does not cover custodial care or long-term nursing facility stays beyond acute medical necessity. The LTCI program provides monthly benefits if you require assistance with activities of daily living due to chronic illness, cognitive impairment, or physical disability. Premiums are affordable for active duty members at roughly fifteen to twenty-five dollars monthly depending on your benefit level and waiting period. I recommend enrolling before you separate because your insurability is guaranteed while on active duty, and private long-term care insurance after separation can cost three to four times more if you have pre-existing conditions that develop during service.
Legal assistance through the Judge Advocate General's office is a free resource many service members ignore until they face a problem. Family law matters like divorce, child custody, and prenuptial agreements fall within their jurisdiction, as do simple wills and powers of attorney. However, they cannot represent you in civilian court proceedings or handle business disputes involving your off-duty activities. A master sergeant I worked with had a landlord-tenant dispute after hisPCS move and assumed JAG could resolve it. They couldn't. The matter required a civilian attorney because it involved contractual interpretation under state law, not military regulations. The initial consultation was free, but the referral to a legal assistance attorney who handles the case costs time and potentially money if you owe your unit for the referral. Personal financial counseling services offered through the Air Force are another underused resource. These counselors help you create budgets, manage debt, and plan for major purchases like homes or vehicles. The service is completely free and confidential, and they can intervene with creditors on your behalf if you're facing collection actions. I encountered a situation where a senior airman was struggling with credit card debt accumulated during basic training and didn't qualify for standard debt consolidation through civilian banks due to limited credit history. The financial counselor helped him negotiate a payment plan with the creditors and established a structured budget that eliminated his balances within eighteen months without requiring bankruptcy or debt settlement programs that damage credit scores significantly. Homeownership assistance through VA loans is perhaps the most valuable benefit many service members don't understand. VA loans require no down payment and no private mortgage insurance, which saves you thousands compared to conventional financing. The funding fee ranges from two to three percent of the loan amount depending on your service type, disability status, and whether this is your first VA loan use. This fee can be financed into the loan rather than paid upfront. A service member with a credit score above six hundred who puts down five percent on a conventional loan will pay PMI monthly until equity reaches twenty percent, which typically takes three to five years. That PMI cost alone often exceeds the VA funding fee over the same period.
The key to managing military finance effectively is understanding that each benefit program has its own eligibility requirements, application processes, and time limitations. You cannot rely on the system to automatically enroll you in everything you qualify for, even though some programs do have automatic enrollment features. Setting reminders for beneficiary designation reviews, TSP contribution increases, and education benefit transfer windows prevents costly oversights that compound over your career. The finance systems themselves are reliable when you provide accurate information, but the complexity of coordinating multiple benefit streams across different agencies means proactive management is essential rather than optional. When things go wrong with your pay or benefits, the first step should always be checking myPay for any discrepancies in your record before filing a formal inquiry. Most issues stem from incorrect rank, dependency status, or duty station information rather than calculation errors. Updating your profile through the proper channels often resolves problems within two to four weeks, whereas filing an inquiry without verifying your record first can delay resolution by an additional month while the system staff verifies information you could have checked yourself. The DFAS contact centers are available Monday through Friday during standard business hours, and they can pull up your transaction history to identify where discrepancies occurred. The ultimate takeaway is that military compensation and benefits are substantial when you understand how to navigate them properly. The system rewards those who take the time to learn the rules and deadlines, and it penalizes those who assume everything will work out automatically. Your first Leave and Earnings Statement is just the beginning. The real financial planning happens when you start coordinating your pay, allowances, retirement contributions, insurance coverage, and benefit elections into a coherent strategy that accounts for your career trajectory and family situation. This requires ongoing attention, but the payoff in terms of financial security and readiness is significant compared to what most civilians achieve over equivalent time periods.