Getting the Most Out of Capital One Mobile App
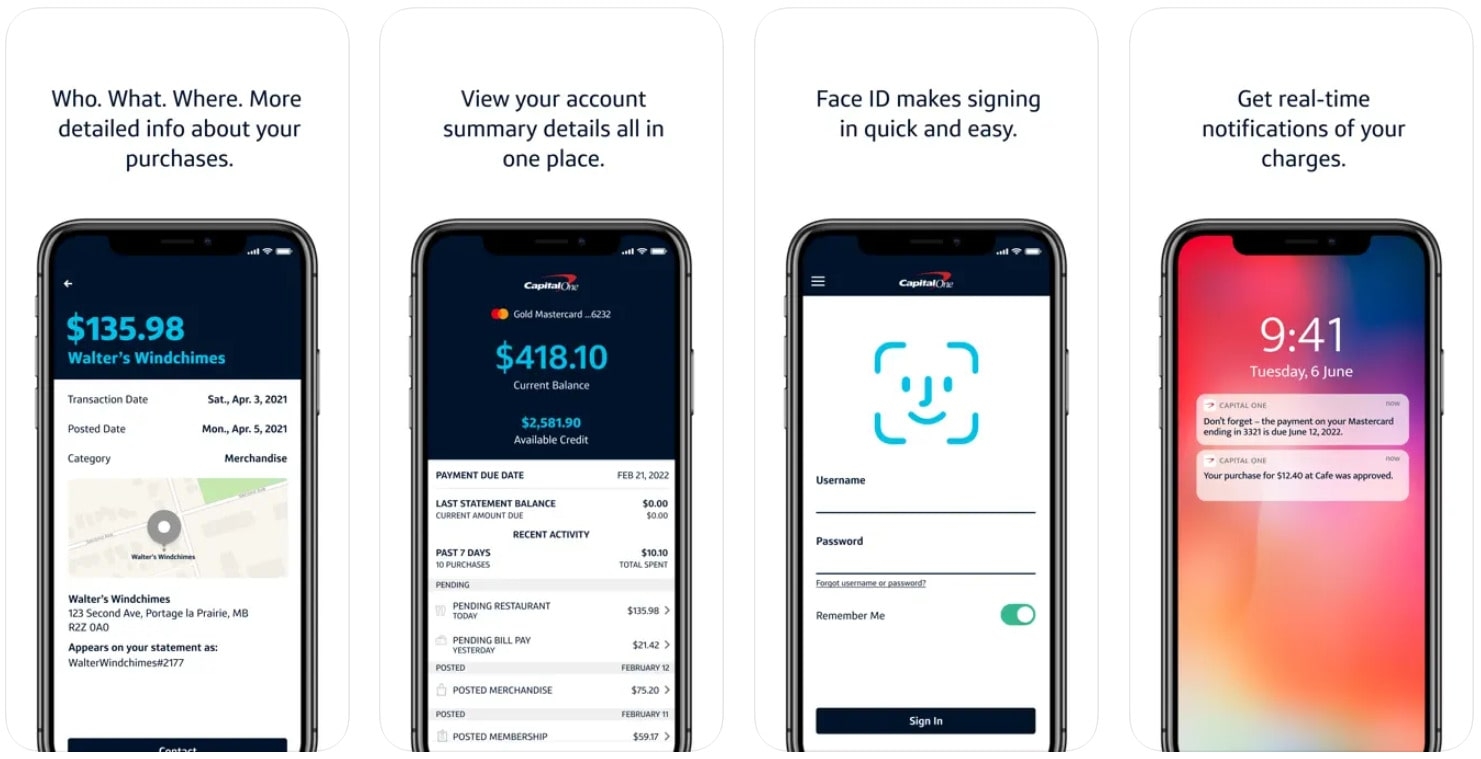
Most people download the Capital One app and immediately get lost in a maze of tabs. I figured it out the hard way after wasting two weeks just trying to find my credit score without realizing it was buried under Rewards on the account screen. Here is what actually matters if you want to stop treating the app like a glorified balance checker. Download it from the official App Store or Google Play listing — that is the only place that makes sense. Sideloading APKs from third-party sites is a fast track to credential theft, and the last thing you need is a fake banking app sitting on your phone. Once installed, you sign in with your existing Capital One credentials. If you are a new customer, you can open an account in the app, though some users report the verification step takes longer on mobile than on desktop, usually around five to ten minutes depending on document loading speed. That phrase gets thrown around in marketing copy, but here is what it actually looks like on a Tuesday night. The app has a "Virtual Card Numbers" feature most people never notice. I discovered it when I needed to sign up for a free trial and didn't want to hand over my real card details. Virtual card numbers generate a one-use or recurring card number tied to your actual account. They have their own spending limits you set per card. That means if a merchant accidentally or intentionally charges more than the limit, the rest of your account stays untouched. I used this for a streaming service subscription that kept getting weirdly inflated on my statement until I switched to the virtual card with a hard $15 cap. No more negotiating with support.
The Cash Manager section is another feature I barely used for months. It pulls together your checking, savings, and credit card balances into a single net worth view. Simple enough. What I did not realize until someone pointed it out is that it also shows your pending transactions in real time, which is different from what you see in the main accounts tab. Pending transactions sometimes show up hours before they post, and this view surfaces them first. Useful if you are tracking whether a refund hit or a hold cleared.
Advanced Features Beginners Miss
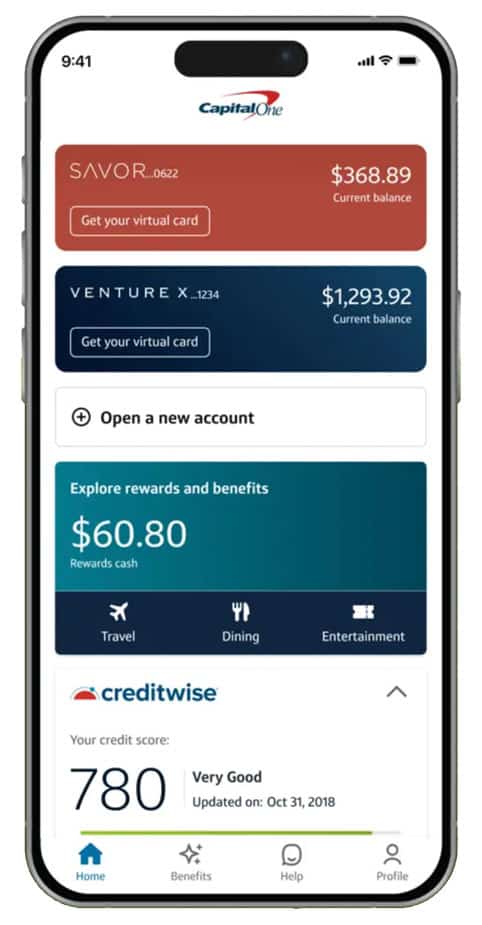
The app has a "CreditWise" integration that pulls your TransUnion score. This is not the exact same score your lender uses — it is a VantageScore 3.0, not a FICO 8 or 9. The difference matters if you are shopping for a mortgage. A mortgage lender runs a FICO Auto/Residential score, and your CreditWise number could be off by fifteen to twenty points. I learned this when my CreditWise showed a 745 and my mortgage pre-approval came back at a 728. Not a dealbreaker, but annoying if you are budgeting around a specific threshold. The 360 Perform card has an automatic upgrade feature. I thought this meant the app would notify me when I was eligible for a higher limit. It does not work that way. The upgrade is entirely manual — you have to click the offer inside the app, review the terms, and accept. There is no auto-application. I waited three months hoping for a notification that never came, then found the offer sitting in My Cards > Account Management > Available Offers. Took about thirty seconds to submit. Here is the part nobody tells you: you can set custom transaction alerts for any dollar amount below what the app defaults to. The default minimum alert threshold is $50. If you want to know immediately when you spend $10 at a gas station, go to Alerts > Set New Alert > Transaction, and enter $10 as the threshold. The interface does not advertise this flexibility, so most people just sit with the defaults. I set one for any purchase over $5 at Starbucks because I was trying to cut that habit and the notification did the trick.
Get the Full Details

Common Problems and Workarounds
The biggest complaint I see on forums is push notifications being delayed by thirty minutes or more. This happens because Capital One batches notification jobs rather than firing them individually. There is no setting to change this, but if you need near-real-time alerts, you can turn on the "Instant Notification" toggle inside the alert settings for transactions. It is only available for certain card types and accounts, and honestly it does not always resolve the delay during high-volume periods. If you are dealing with fraud concerns, downloading a second banking app as a backup — like the one from your local credit union — sometimes gives you faster notifications because smaller institutions often use different infrastructure. Another issue is the app occasionally freezing during balance loads when you have a lot of recent transactions. The workaround is to pull down on the account screen to force a refresh, then wait the full ten to fifteen seconds before tapping anything else. Double-tapping the refresh button makes it worse. I tried that once and ended up logged out with a session error that required a full restart to fix. The bill pay feature is the most unreliable part of the entire app. I scheduled a payment to my electric company through the app on a Friday evening. The app showed a confirmation screen. Monday morning, the payment was still listed as "scheduled," not "sent." I called support and found out the routing went through a batch process that only runs twice a week on Capital One's side. Scheduled bill pay through the app does not equal instant or same-day processing. If you need a payment to go out immediately, use the web version instead, or better yet, set up autopay directly with the vendor.
Security Settings You Should Actually Change
After installing the app, go into Settings > Security right away. Default login is fingerprint or face ID, which is fine, but two-factor authentication is set to SMS by default. Switch it to the app-based authenticator or your linked device. SMS 2FA is vulnerable to SIM-swapping attacks, and Capital One customers have been targeted. I made this change after reading about a friend whose number was ported and who got locked out of every banking app within forty minutes. The port wasn't even attempted through Capital One — it happened because his phone number was registered everywhere. Locking down 2FA was step one. Also set a PIN for the app itself, separate from your device passcode. I know it seems redundant, but if someone borrows your phone, they can open the app with Face ID if that is your only gate. The app PIN requires something you know, not something you are. It adds about two seconds to every login and prevents exactly one class of social engineering.
What the App Cannot Do
There is no way to merge two Capital One accounts through the app. If you have a 360 Checking and a Personal Platinum card and want to link them for automatic payments, you do that inside the online banking portal at capitalone.com, not in the mobile app. The app's relationship with linked accounts is strictly display. Transfers between your own Capital One accounts work fine on mobile, but external account linking — Chase, Wells Fargo, whatever — requires the desktop interface. I wasted twenty minutes trying to figure out why the "link external account" button was grayed out before I switched to Chrome on my laptop and had it done in three clicks. The mobile check deposit has a limit of $1,000 per day and $5,000 per month unless you are a Prism member or have a high-limit Platinum card. Even then, the limit is discretionary. I deposited a $2,400 check and the app rejected it on the second try without explaining why. Called support, found out the hold was because the check was from a credit union not in their preferred network. They approved the deposit manually over the phone. This is the kind of friction that never makes it into a review. Finally, the app does not support setting up trust accounts or business accounts from scratch. If you are running a small business and want a Capital One business checking, you have to call or visit a branch. The app is consumer-only. I tried applying for a business account inside the app once and got a generic "this feature is not available" message with no further explanation. That was not helpful.
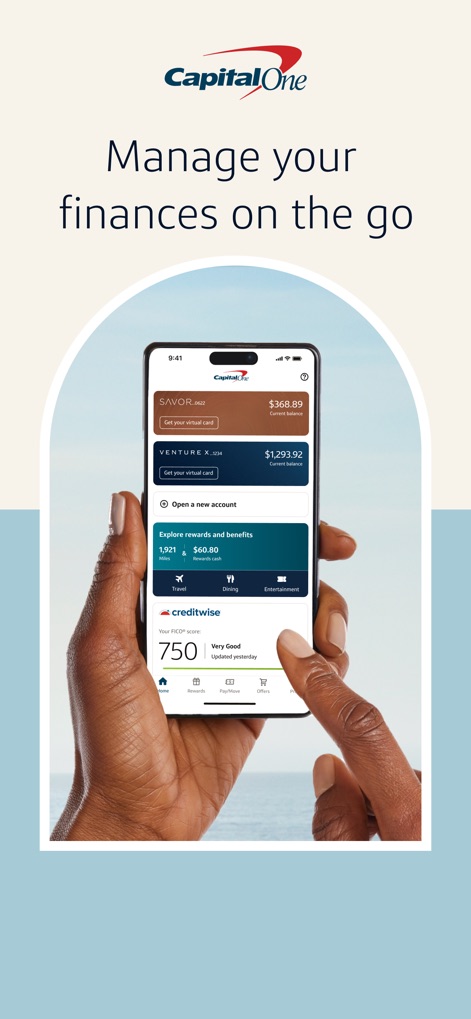
Bottom line: the app is solid for daily checking, transaction monitoring, and credit score tracking. It is clunky for anything involving account setup, external linking, or bill payment timing. Knowing where the boundaries are saves more time than any tutorial can. Download it, enable the security features, set up at least one custom alert, and use the desktop site for anything complicated. That is the pattern that works.