
Equipment financing is one of those things every business owner hears about but barely understands until the moment they actually need it
I spent about eight years in commercial lending before moving to the borrower side, and I still see the same mistakes repeated. People apply for equipment loans the way they'd apply for a credit card—glancing at the monthly payment and ignoring everything else. That approach works fine for small purchases. It falls apart when you're looking at six figures. The basic mechanism is straightforward. You identify the equipment you need. You find a lender. They assess the equipment itself as collateral alongside your credit profile. You sign paperwork. Money moves. You pay it back with interest. The equipment is pledged until the balance hits zero. That's the textbook version. The real version involves more moving parts. Most equipment financing comes in three flavors: traditional term loans, operating leases, and capital leases. Each one impacts your balance sheet, your taxes, and your cash flow differently. Pick the wrong one and you'll be paying more over the life of the loan while also taking a hit on your debt-to-income ratio that makes future borrowing harder than it needs to be.
I had a client a few years back who was buying a fleet of commercial refrigeration units for a expanding restaurant group. The salesperson at the equipment vendor pushed a lease that looked attractive on paper—low monthly payments, nice and clean. But when we dug into the actual terms, it turned out to be a capital lease with a balloon payment at the end that was larger than the original purchase price. My client would have owed roughly $84,000 in a single lump sum after three years, and the depreciation schedule meant they got almost nothing in tax deductions during the lease term. We restructured it as an installment loan with a fixed rate instead. The monthly payment went up about $600, but the total cost dropped by nearly $22,000 and they owned the equipment outright at the end with a clear depreciation schedule to work with.
Unlock The Full Potential Of Your Business With Financing Iin0oscdjsc Equipment A Complete Guide
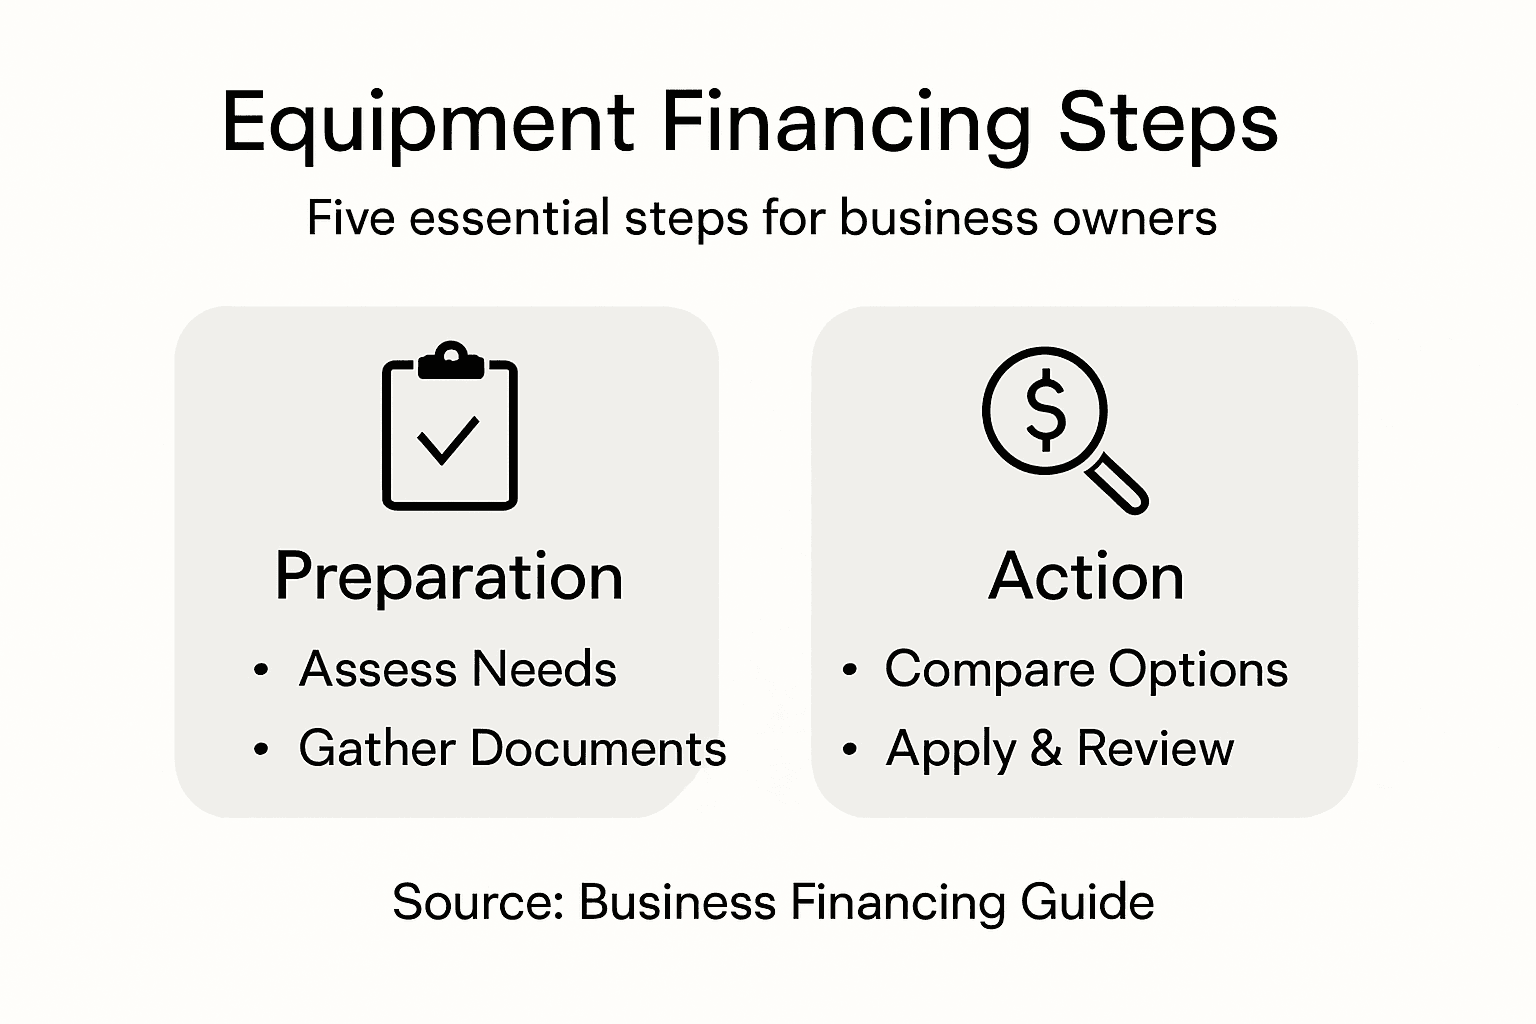
When you're evaluating an equipment financing option, the first thing I check is the effective annual percentage rate, not the monthly payment. Lenders will happily hide a 12.5% APR behind a payment schedule that looks reasonable because they stretch the term out to sixty or seventy-two months. A longer term lowers the monthly hit but adds significant interest cost. On a $150,000 piece of industrial machinery, a five-year loan at 9% APR costs about $37,500 in interest. A seven-year loan at what looks like a comparable 8% costs roughly $52,000 in interest. That's a fifteen-thousand-dollar difference that most people miss because they're focused on whether the monthly number fits their cash flow projection. Another thing nobody warns you about: residual value risk. If you lease equipment and the residual is set too low, you might be on the hook for the difference when the lease ends. I saw a consulting firm get blindsided by this with a fleet of delivery vans. The leasing company had projected a residual of 40% based on optimistic market assumptions. Actual resale values came in at 28%. The company owed $18,000 per van at lease end just to make up the gap. If you're leasing, always ask for the residual percentage upfront and run your own numbers against current used-equipment pricing on sites like Machinery Trader or Equitrust. The application process itself is where most people waste time. Prepare a one-page summary of what you need, why you need it, how much it costs, and how the revenue from that equipment justifies the payments. Lenders see hundreds of applications. The ones that come in with a clear narrative and basic financials attached—recent tax returns, a year-to-date profit and loss statement, and a simple equipment quote—move through underwriting in days instead of weeks. The ones that don't sit in a queue for three to four weeks while the underwriter asks for documents that should have been included on page one.
Get the Full Details

Where Equipment Financing Falls Short
Equipment financing isn't a universal solution. It only makes sense when the equipment has a clear, measurable useful life and a verifiable resale value. If you're financing specialized manufacturing equipment that only works for one specific product line and has almost no secondary market, lenders will either turn you down or price the loan significantly higher to account for the risk. I worked with a custom packaging manufacturer who needed a specialty die-cutting machine. The lender offered the loan but at 14.5% because the collateral was essentially worthless outside of that one application. The same equipment financed through a manufacturer's internal program at a different vendor would have been closer to 7%. Always check whether the equipment manufacturer or dealer offers in-house financing before going to a bank or credit union. There's also the prepayment penalty issue. Some equipment loans have steep prepayment penalties in the first two to three years. If you're planning to sell the equipment early or refinance when rates drop, that penalty can eat into your savings. I've seen penalties structured as 3% of the remaining balance in year one, dropping to 2% in year two and 1% in year three. On a $200,000 loan with $140,000 remaining in year one, that's a $4,200 fee just for paying early. It's worth reading the prepayment clause carefully before signing anything. The other limitation is qualification. Equipment financing still requires personal guarantees in most cases, especially for small to mid-size businesses. If your credit score is below 650 or your business has fewer than two years of operating history, you're looking at higher rates or outright rejection from traditional lenders. In those cases, a lease-to-own arrangement through a specialized equipment financier might be more accessible, though the total cost will be higher. Sometimes the tradeoff is worth it if you need the equipment immediately and can't wait six months to rebuild your credit profile.
When you walk into this with your numbers organized and a clear understanding of which financing structure actually fits your situation instead of just grabbing the lowest monthly payment, the process is manageable and usually finishes within ten to fourteen business days from application to funded. The people who struggle are the ones who treat it like an afterthought and show up empty-handed.

/CCG-Equipment-Financing-eBook-Cover (LG).png?width=537&height=765&name=CCG-Equipment-Financing-eBook-Cover (LG).png "Download the Equipment Financing Guide | CCG")
