Getting Aetna Medicare Advantage Benefits Working For You
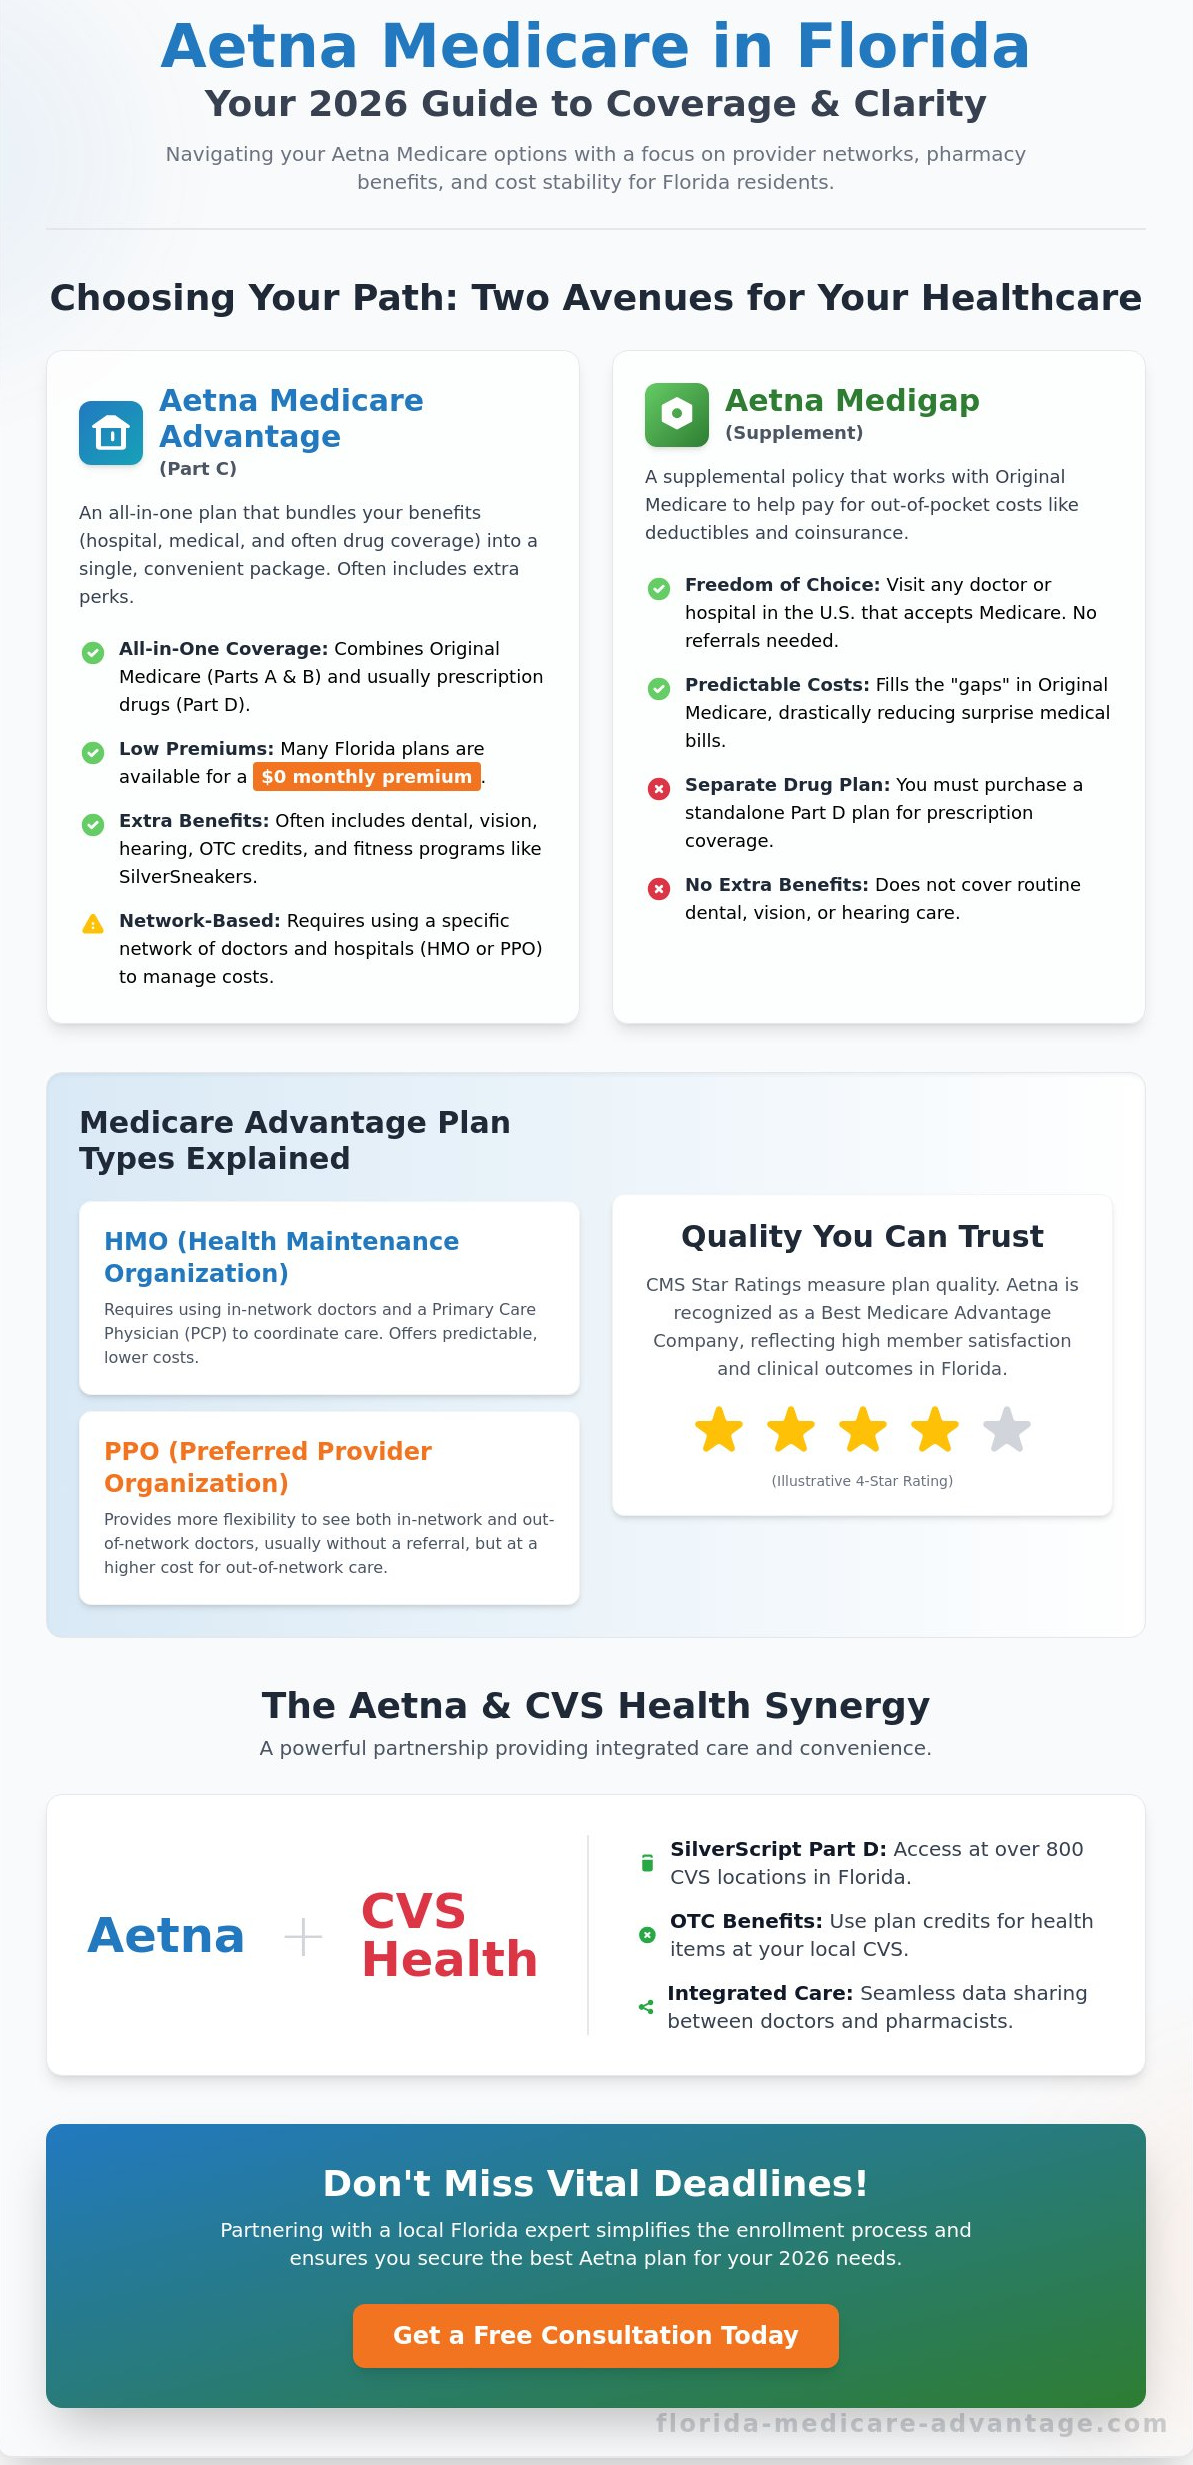
Most people sign up for a Medicare Advantage plan and just forget about it until they get sick. That's not really how it works. Aetna's platform has tools that can actually save you money and reduce headaches, but you have to go in there and use them deliberately. I've spent years watching people miss out on things that were already paid for, or paying out of pocket when they shouldn't have had to. The first thing you need to understand is that Aetna MA plans come in several flavors — HMO, PPO, HMO-POS, SNF, and OAP. Each one has a different network structure, different cost-sharing rules, and different supplemental benefits. Before you do anything else, log into myAetna.com or download the app and pull up your actual plan documents, not the marketing summary. The marketing PDF will tell you your copay for a primary care visit is $0. The Evidence of Coverage (EOC) might say that's only true inside-network, and only if your PCP does a referral first. These details matter when you're actually standing in a doctor's office. Here's what most people get wrong about Aetna's benefit access: they think the benefits are the fixed set listed on the Medicare plan comparison site. They're not. Aetna allows individual plans to vary supplemental benefits significantly based on state and county. Some plans include over-the-counter allowances, dental and vision components, hearing aids, and fitness memberships like SilverSneakers. Others don't. Some include transportation to medical appointments, which sounds like nothing until you need it at 7 AM on a Tuesday and your local hospital is three bus transfers away.
I ran into a specific issue last year with a client whose plan included a dental benefit but she'd been using an out-of-network dentist for years without realizing it. The plan covered 80 percent of preventive services in-network, but her regular hygienist wasn't contracted with Aetna MA. She ended up paying full price for cleanings that should have been free. The workaround was simple but not obvious — I had her pull up the Aetna provider search tool, filter by "dental" and her ZIP code, and book with the nearest participating office. That saved her roughly $400 per year on hygiene visits alone. The myAetna portal is where you'll find most of what matters. After logging in, check these sections methodically: Benefits Summary: This shows your current coverage year by year. Review it every January when benefits reset. Some plans change their supplemental offerings annually without a lot of fanfare.
Claims History: Pull this quarterly. Aetna occasionally processes claims under the wrong code or applies the wrong copay tier. I've seen people get billed for specialist visits when their plan had zero copay for them, or vice versa. Catching a billing error early means you don't have to fight it six months later when the denial letter arrives. Prescription Drug Formulary: This isn't static. Aetna can move medications between tiers at any point during the year, usually with 30 days' notice. If you're on a maintenance medication, check the formulary every few months. Getting bumped from Tier 2 to Tier 3 can add $50 to $120 per month to your costs. Telehealth Access: Aetna offers its own telehealth platform and also contracts with Teladoc. For minor issues — rashes, sinus infections, UTIs — this cuts a typical office visit down from a half-day commitment to about fifteen minutes. The copay is usually the same or lower than in-person. But it only works for appropriate conditions. Don't use telehealth for anything that could be serious. A rash and chest pain might look similar online but require very different responses.
Get the Full Details

Here's something that isn't obvious about Aetna MA plans: the out-of-pocket maximum. Every Medicare Advantage plan has one, but it varies widely. Aetna's typical range is somewhere between $4,500 and $6,950 annually depending on the plan type and location. Once you hit that number, Aetna covers 100 percent of in-network services for the rest of the calendar year. This is different from original Medicare, which has no hard cap. Understanding where you are relative to your OOP max is critical if you're facing any kind of surgery or prolonged treatment. One thing to be careful about — and this is where people get tripped up — is the difference between the plan's annual limit and your individual usage. Some supplemental benefits, like dental or vision, have sub-limits within the broader plan. A common dental sub-limit might be $1,500 per year. If you need a crown that costs $1,200 and a bridge that costs $2,000, you're not going to get full coverage on both. Know your sub-limits before you schedule procedures. Another area where Aetna stands out from some competitors is their care management programs. If you have a chronic condition like diabetes or congestive heart failure, Aetna may proactively reach out to assign you a care coordinator. These people are genuinely useful. They help with care transitions, medication reconciliation, and connecting you with local resources. The catch is you don't always know they exist until they call you. I'd recommend calling Aetna's member services number and asking directly whether you're enrolled in any care management programs. If you have a chronic condition and aren't enrolled, ask to be. It's free and often makes a measurable difference in how smooth your care stays.
There are downsides to consider here. Aetna's network can be narrow in some markets. In certain rural areas, the number of in-network specialists is limited enough that you might end up going out-of-network for things like cardiology or orthopedics. Under an HMO plan, out-of-network care generally isn't covered except in emergencies. Under a PPO, it is, but at a significantly higher copay or coinsurance rate. If your local hospital system isn't contracted with Aetna, that's a real problem you need to plan around. Also, Aetna's prior authorization process can be slow. For non-emergency procedures, MRIs, and specialty medications, prior auth is routine. The turnaround time is typically five to ten business days, but complex cases can take longer. If you're scheduling something elective, start the prior auth process at least three weeks out. Don't wait until the week of your appointment and then discover the authorization hasn't been submitted. If Aetna's network doesn't cover your needs in your area, or if you find the plan structure too restrictive, you can switch during the Annual Enrollment Period (October 15 through December 7) or qualify for a Special Enrollment Period based on life events like moving, losing other coverage, or qualifying for Extra Help. Before switching, make sure you compare the new plan's drug formulary against your current medications — switching plans can easily change what you pay for prescriptions even if the plan itself looks cheaper on paper.
The practical bottom line is that your Aetna Medicare Advantage plan is a toolbox, not a set-and-forget product. Log in, read the documents, check your claims, verify your providers are in-network, and use the supplemental benefits while you have them. People who do that systematically tend to have far fewer billing surprises and lower out-of-pocket costs than people who assume everything will just work itself out.