So You Make 70 Bucks An Hour And Think You're Set
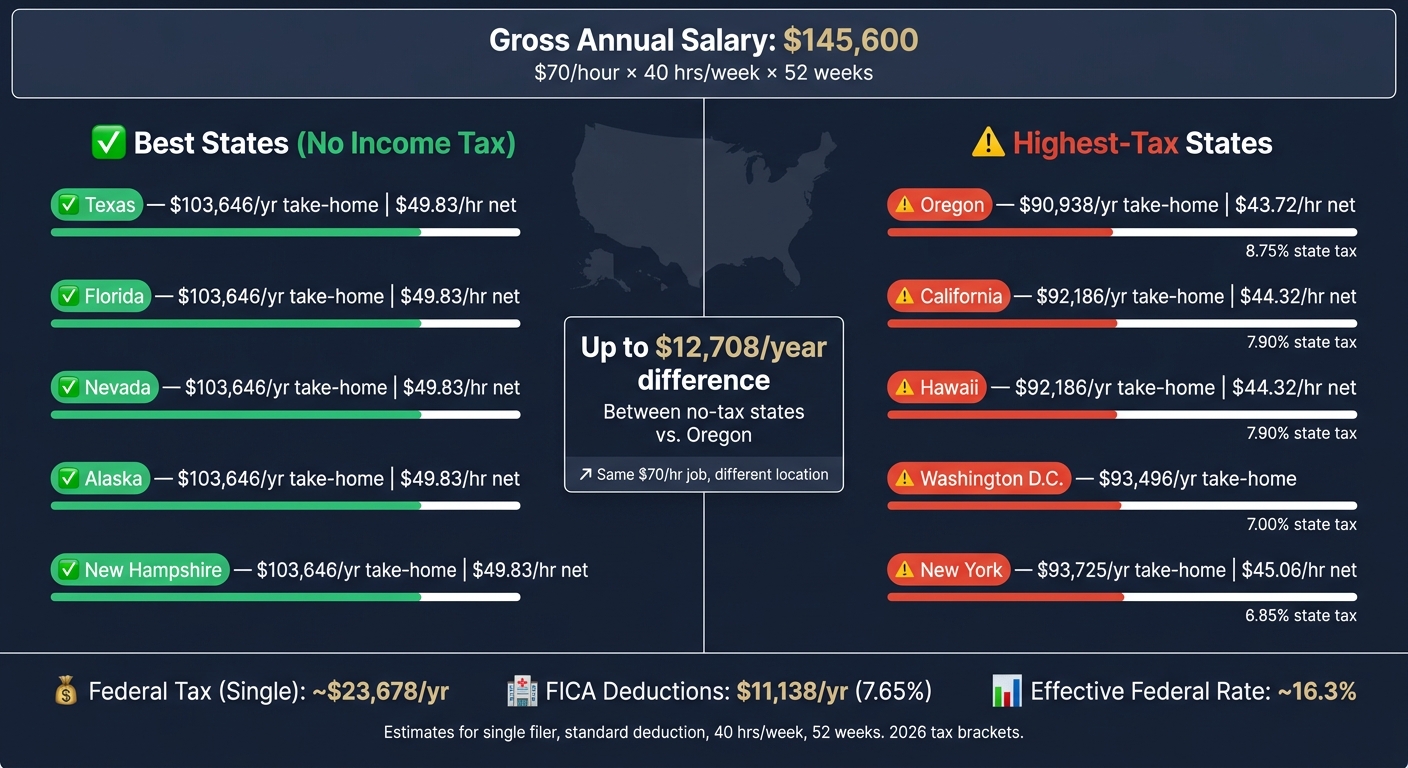
You probably are, relative to most people, but making seventy an hour does not automatically mean you are building wealth. It means you have a better input variable than average. What you do with the output is where everything changes. I have seen contractors at this rate live paycheck to paycheck because their expenses scaled linearly with every raise. I have also seen people making half that hourly rate retire comfortably because they treated the money like it was scarce, not abundant. The core problem with a seventy dollar an hour income is that it lands you in a tax bracket where the government takes enough to make you feel poorer than you actually are, but not enough to trigger automatic wealth-building advantages like the ones available to six-figure salaried employees with employer matches. You are in the gray zone. You need to be intentional about everything. At roughly one hundred forty five thousand dollars a year assuming full time work, you are dealing with marginal rates that vary depending on filing status and state. The first thing I would do is confirm whether your employer offers a 401(k) or similar plan with a match. If they do, take the full match before you touch anything else. That is instant money. If your employer does not offer a retirement plan, open a traditional IRA and then a Roth IRA. Contribute to the traditional IRA first up to the point where it meaningfully lowers your taxable income, then max out the Roth.
If you are self-employed or a contractor, the game changes entirely. A Solo 401(k) or SEP IRA lets you contribute significantly more than a standard IRA. I worked with a freelance developer who was billing at seventy five an hour and had no business structure. He was paying self-employment tax on his entire income with no deductions. We set up a single member LLC, elected S-corp status, and he started paying himself a reasonable salary while taking distributions. His effective tax rate dropped by about eleven percent. It was not a loophole. It was just understanding the structure that was already there.
Expense Scaling Is The Real Trap
This is the part nobody tells you about making seventy an hour. Your lifestyle will try to expand to absorb the income. Rent increases. Car payments increase. Dining out increases. I watched a guy at my old firm make eighty two an hour and still be stressed about money every month because his car payment was nine hundred dollars and his apartment was eighteen hundred. He was spending about forty five percent of his gross income on housing alone. That is unsustainable if you want to build anything. The fix is not complicated but it is uncomfortable. Keep your housing cost under thirty percent of gross income. Keep your total transportation cost under fifteen percent. Everything else is discretionary and it should be budgeted, not accidental. When I ran my own numbers last year, I found that I had been spending about four hundred dollars a month on subscriptions and recurring services I barely used. Canceling those did not change my life quality at all but it added nearly five thousand dollars a year to my investable income.
Get the Full Details
Investment Strategy
With an income at this level, you have enough left over after basic expenses to actually invest consistently. The mistake people make is trying to pick individual stocks or chase crypto because they feel like their income gives them permission to be aggressive. It does not. Your income gives you permission to be consistent. A simple portfolio of low-cost index funds covering total US market and total international market will outperform most actively managed strategies over any meaningful time horizon. I put about twelve percent of my gross income into taxable brokerage accounts and the rest into tax-advantaged vehicles. That has been enough to generate substantial growth over twelve years. The number that matters is not which fund you pick. It is whether you actually deposit money every month without skipping it.
Side Income And Leverage
Seventy an hour is a solid floor but it is still trading time for money. The real potential unlock happens when you create income that does not require your direct hourly presence. This does not mean starting a business unless you actually want to. It can mean building digital products, creating educational content, renting out space you already own, or simply investing in assets that generate passive cash flow. I spent about six months building a small toolkit of automation scripts that I sold once and then maintained for updates. It generates roughly eight hundred dollars a month now with maybe thirty minutes of work per month. That is not exciting but it is real. More importantly, it is income that does not disappear if I lose my primary job. That insurance value alone is worth the initial effort.
Common Mistakes At This Income Level
First mistake is ignoring health insurance optimization. If your employer offers an HSA, use it. It is triple tax advantaged. Contribute the maximum and invest the balance. Most people treat HSAs as spending accounts and leave the money in a low interest savings account. That is leaving free money on the table. Second mistake is carrying consumer debt while investing. If you have credit card debt at twenty percent interest, paying that off is a guaranteed twenty percent return. No investment does that consistently. Clear high interest debt before you worry about optimizing your portfolio allocation. Third mistake is not negotiating. At seventy an hour you are likely in a position where you have some leverage. I have seen people stay at the same rate for three years while inflation ate twenty percent of their purchasing power. A single conversation about adjusting your rate or salary can add tens of thousands of dollars over a career. The worst that happens is they say no and you keep your current rate.

What This Actually Looks Like In Practice
Here is a realistic snapshot. Gross annual income one hundred forty five thousand dollars. Federal and state taxes approximately thirty eight thousand. Take home about one hundred seven thousand. Housing at twenty eight percent of gross is forty thousand seven hundred. Transportation at twelve percent is seventeen thousand four hundred. That leaves about forty one thousand for everything else including food, insurance, discretionary spending, and savings. If you live below that number you are building wealth. If you spend it all you are working very hard for nothing. The math is straightforward. The behavior is hard. Most people fail at the behavior part, not the math part. Track your actual spending for ninety days. You will be surprised. Then adjust. Repeat every quarter.