Getting Financing Through Tractor Supply Is Less Complicated Than Most People Think
Most folks assume you need perfect credit to walk out of a Tractor Supply with financing approved, but that's not how it actually works. Their financing partner runs soft-pull pre-qualification through Credit Karma or a similar service before you ever commit to anything. I've had contractors come in with debt-to-income ratios hovering around 45% and still get approved on terms that are borderline workable. The real trick is understanding what kind of account they're offering you, because not all Tractor Supply financing is the same. There's the standard store card, which operates more like a revolving credit line, and then there's the deferred interest promotional options that show up during seasonal pushes. Those two work very differently, and mixing them up costs people money they didn't plan to spend.
Unlock The Field With Tractor Supply Financing Options Explained
Here's how the process actually goes when you sit down at the register or apply online. You submit your application with your Social Security number, income information, and the address you've been at for however long. They run a soft inquiry first, which doesn't touch your credit score at all. If you pass that screen, you get a hard pull. That's the one that shows up on your report and drops your score by roughly 5 to 10 points, maybe a bit more if you've got a thin file. The approval itself usually comes back within minutes. I've watched people get confirmed while still standing in the checkout lane. The card gets mailed to you, and you can use your digital card in the app immediately. That part is genuinely fast compared to a lot of other retail financing programs out there. Now, the deferred interest promotions. This is where people get tripped up. Let's say you put a $2,000 tractor attachment on a 6-month no-interest offer. If you pay off the full balance by the end of those 6 months, you owe zero interest. If you're short by even $47.32, they retroactively charge interest from the original purchase date at the standard APR, which sits around 29.99% for most applicants. That $2,000 purchase could suddenly become a $2,300 purchase overnight.
I learned this the hard way back in 2022. My neighbor needed a new water pump system for his hay operation, something around $1,400. He qualified for the 12-month deferred interest deal and thought he'd pay it off slowly over the year. He missed the final payment by three days and owed about $380 in back-accrued interest on top of the remaining balance. He called the number on the back of his card, explained the situation, and got a one-time courtesy adjustment that wiped most of it. The rep told him they do this occasionally, but you have to call quickly and be polite about it. That detail never gets mentioned at the point of sale. There's also a nuance about minimum monthly payments that catches people off guard. On deferred interest plans, making only the minimum payment each month rarely clears the balance in time. The payment structures are calculated to keep you in debt longer, not to help you escape the promotional window. If you're going after one of these deals, set up automatic payments for at least half the balance, preferably more. Another thing worth noting is that Tractor Supply financing doesn't report utilization the same way a regular credit card does. Because it's a retail installment account, it tends to sit quietly on your credit report without dominating your utilization ratio the way an open-end credit card would. That can actually be a benefit if you're trying to keep your scores stable while you're carrying a balance.
Get the Full Details
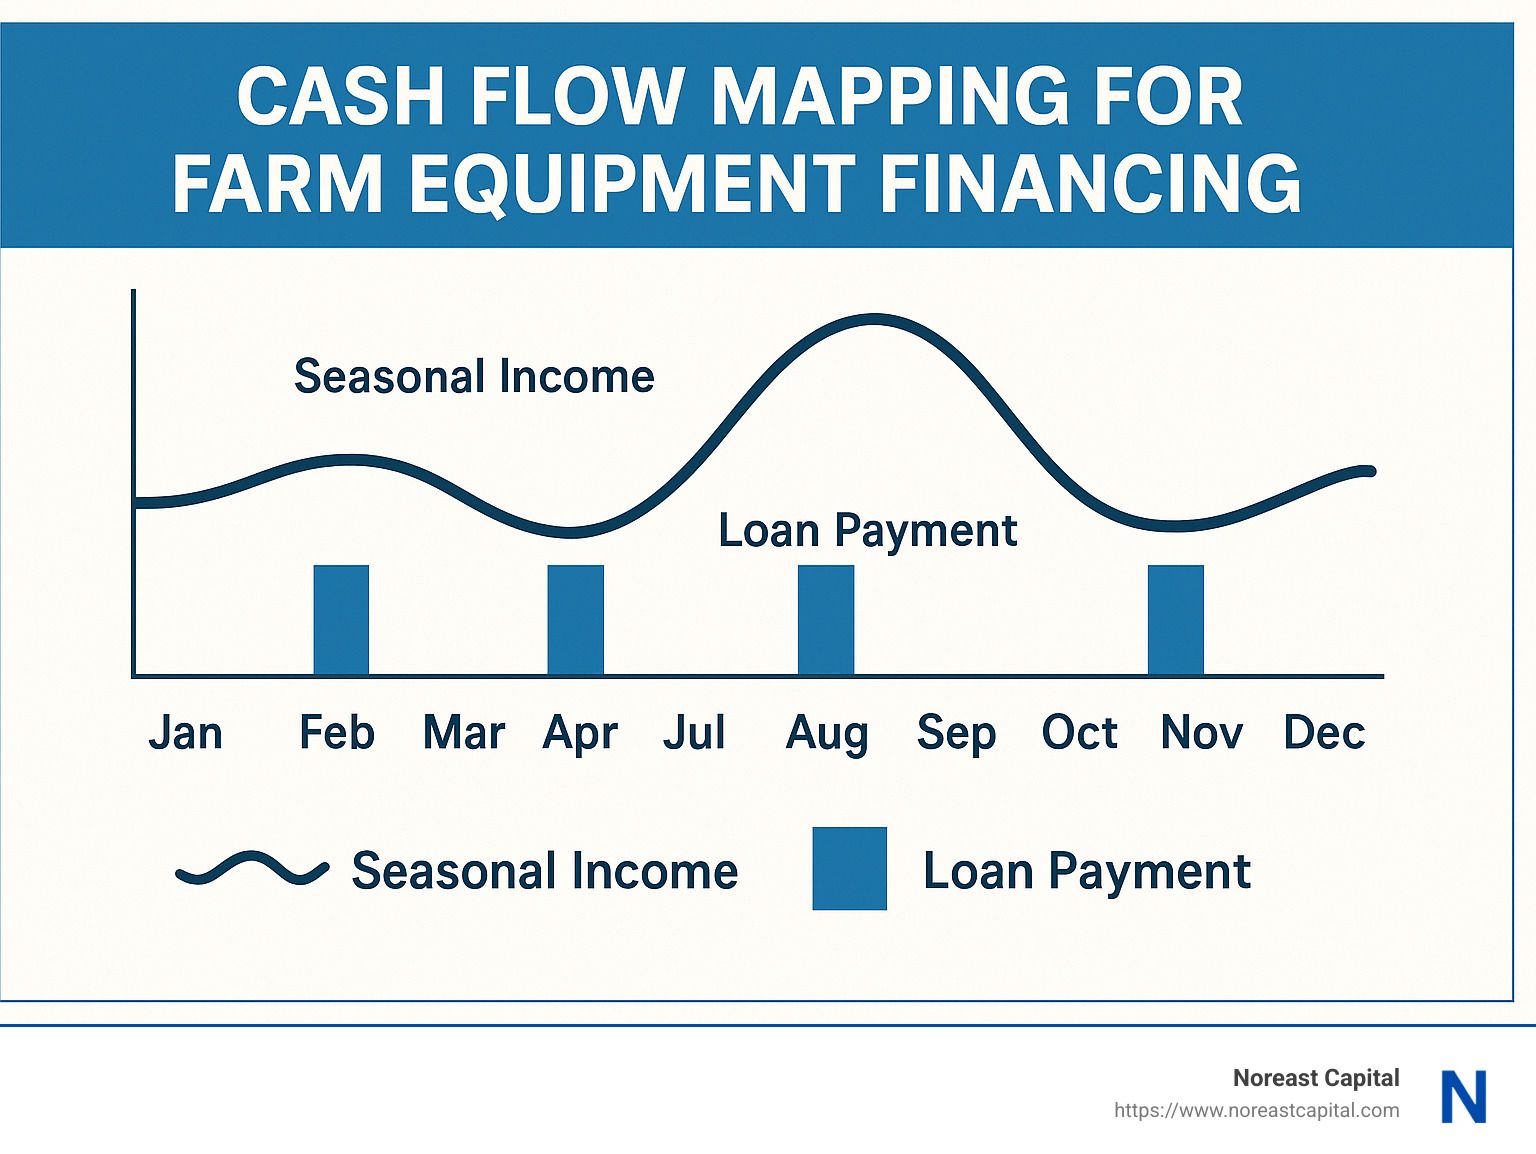
The downside is straightforward. The APR is steep. Even on standard purchases without any promotion, you're looking at 25% to 30% depending on your credit tier. If you're someone who carries a balance month to month on a regular credit card at 18%, switching to Tractor Supply's card will actively hurt your wallet. It's only worth it if you're disciplined about paying it off quickly or if you can reliably clear a deferred interest promo before the clock runs out. I also recommend not combining multiple Tractor Supply credit products at once. Opening both the store card and a promotional financing plan simultaneously creates a situation where minimum payments compound across two accounts. I saw a guy do this after buying fencing supplies and a skid steer attachment in the same transaction window. His total monthly obligation was higher than his take-home pay could sustain, and he ended up in collections within eight months. One account, pay it aggressively, move on. If you're applying and your initial request gets declined, don't just walk away. Ask about the secured card option if they offer it in your state, or consider using a different payment method for now and reapplying later after you've had time to adjust your credit profile. A single application denial doesn't permanently blacklist you, but three within six months creates a pattern that future lenders will notice.
One more practical thing. Download the Tractor Supply app before you apply. The app lets you track your promotional deadlines, view your balance in real time, and set up payment reminders. Without it, you're relying on paper statements or sporadic email notifications, and missing a deferred interest cutoff by a week is embarrassingly easy when you aren't tracking it yourself.