Ulta Beauty Credit Actually Makes Sense If You're Strategic About It
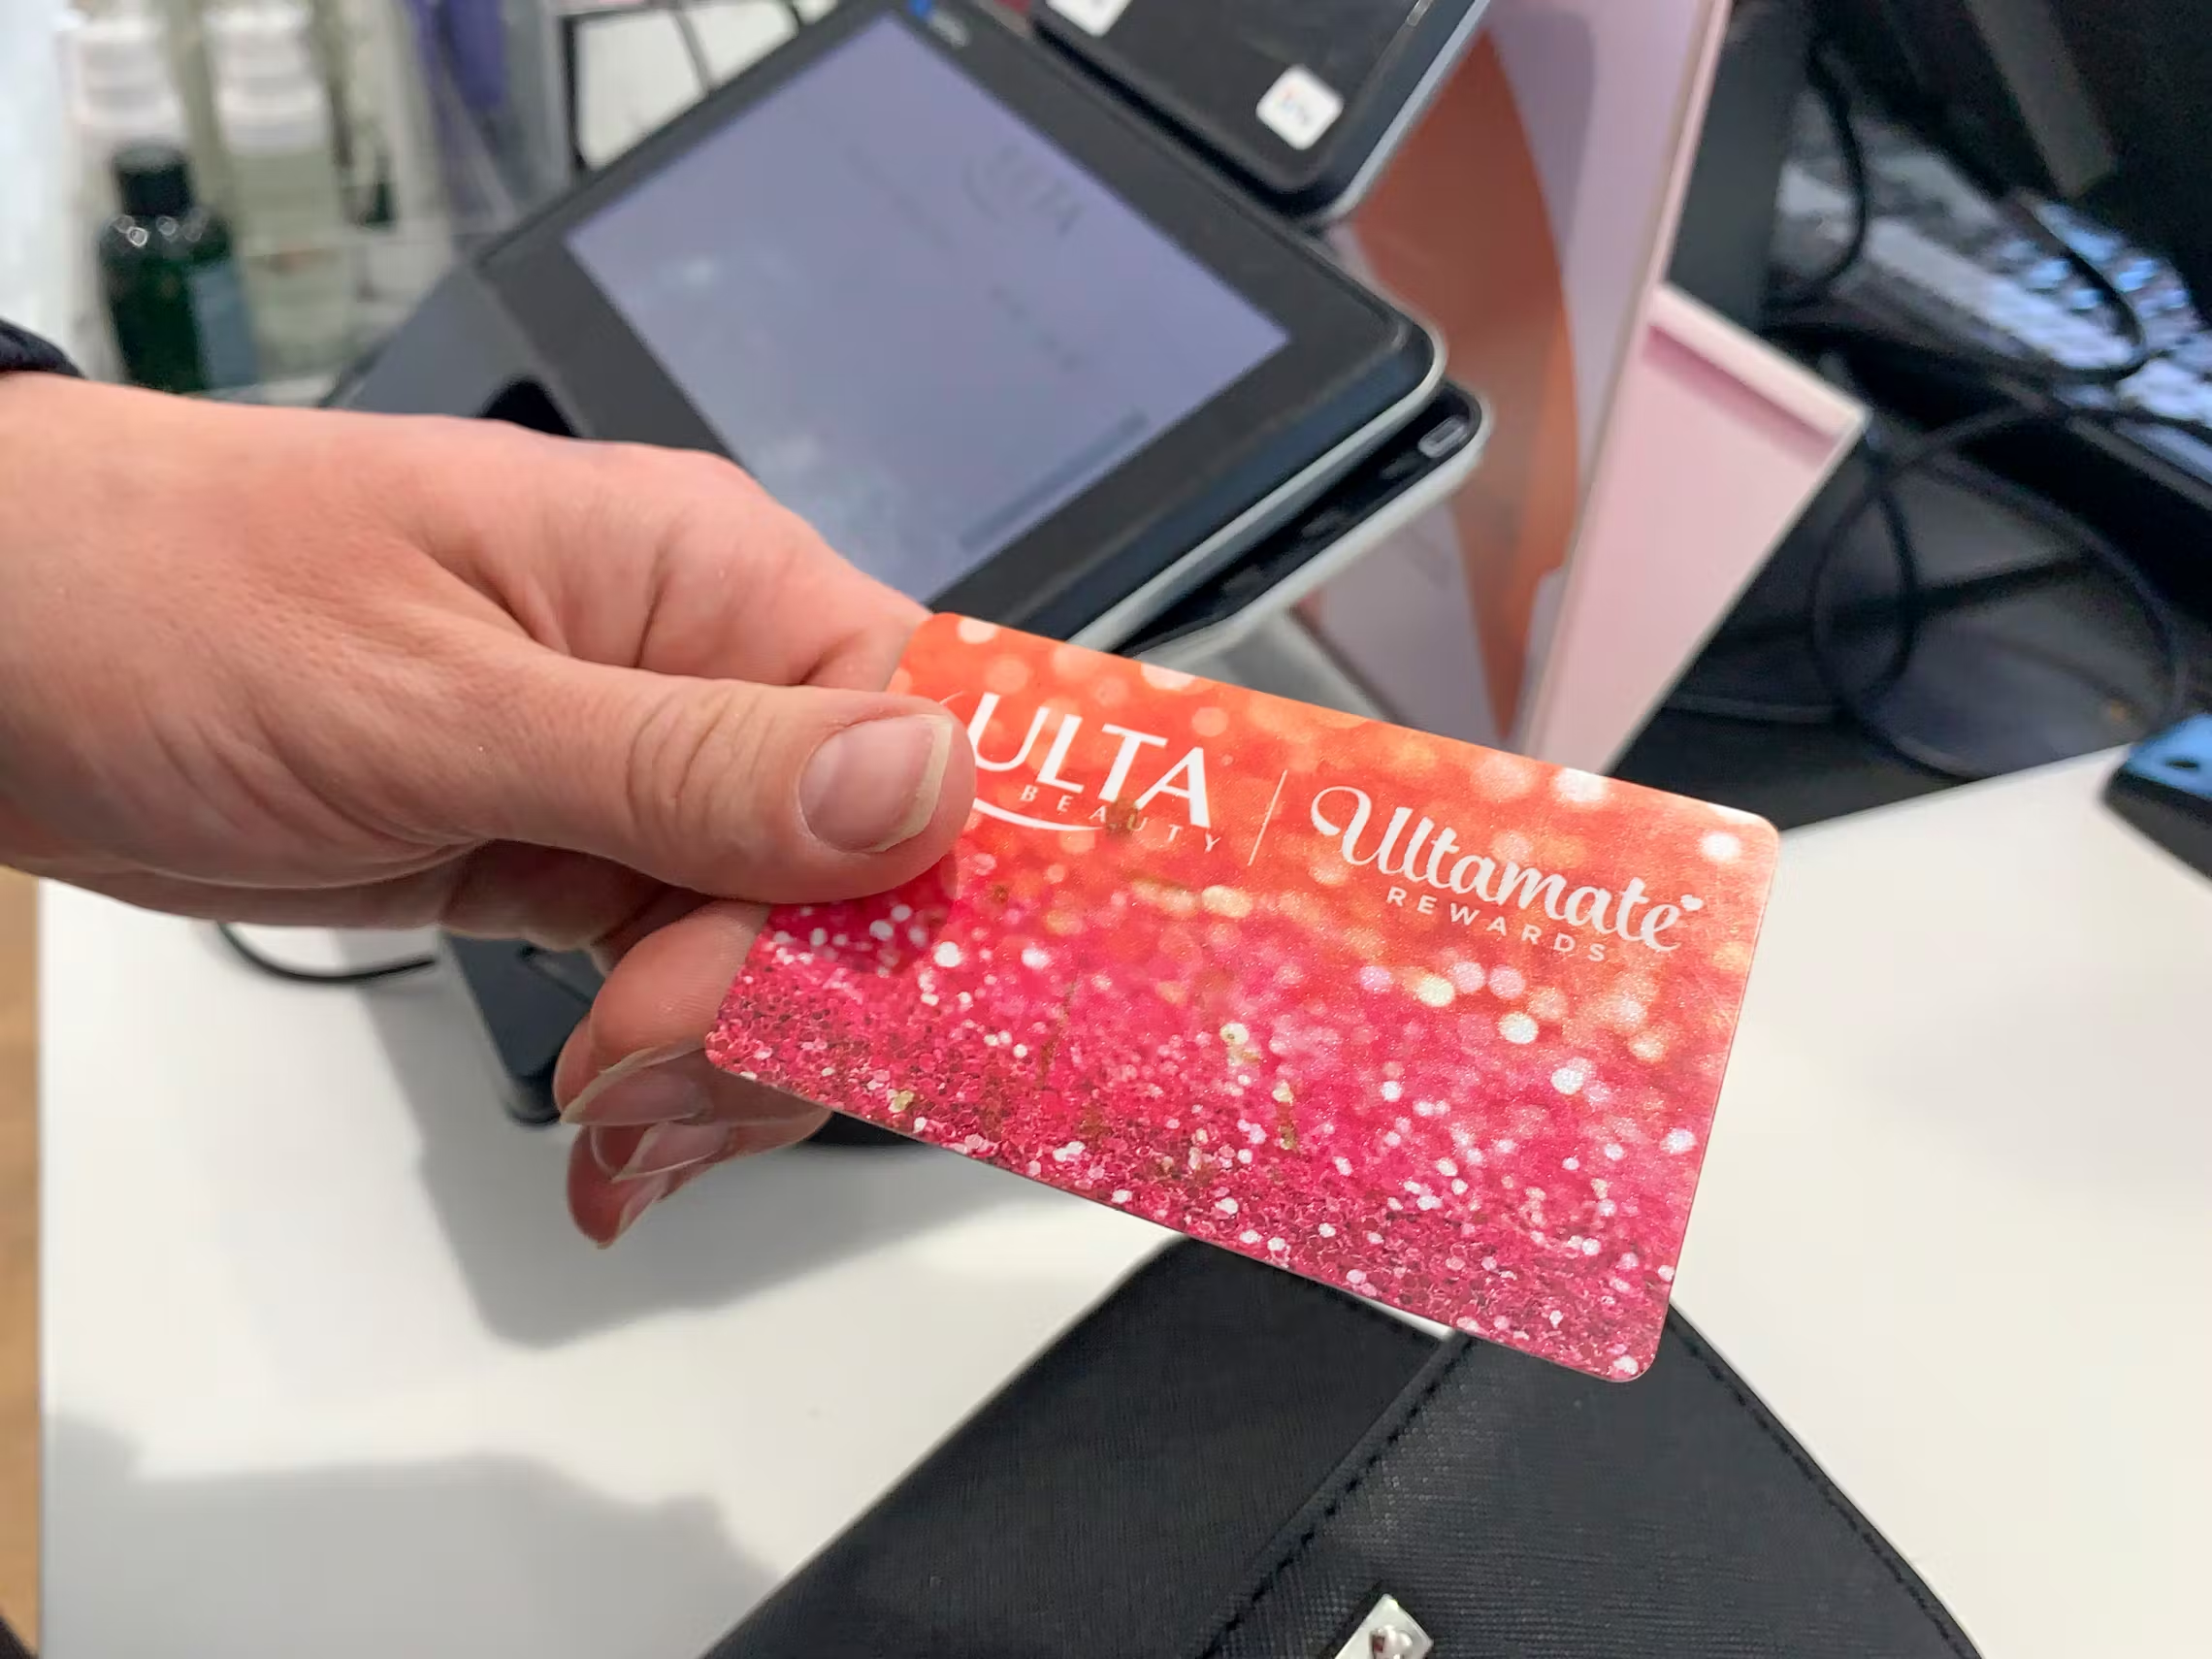
I opened my first Ulta credit card during a Sephora shortage in 2022. Not because I loved the brand, but because I needed something to cover a $180 purchase of products I literally couldn't find anywhere else. Five years later, I still have that card. It's not perfect. It's not terrible. It's just a tool that works if you know how to use it. Ulta offers two main credit products: the Ultamate Rewards Credit Card (branded) and the store card. They look identical on your statement but behave very differently behind the scenes. I learned this the hard way when I tried to split payments across both at checkout and the system rejected half my order because I'd already maxed out the store card limit on a previous return.
Unlock The Door To A World Of Endless Beauty Possibilities Your Beauty Wishlist Just Got Easier With Ulta Beauty Credit
The branded card operates through Citibank. The store card runs through Comenity Bank. Different underwriting, different reward structures, different APRs. When you apply on Ulta.com you're actually applying for both simultaneously unless you uncheck the second box. Most people leave it checked. That means two hard pulls on your credit report from a single shopping trip. Here's how the rewards actually accumulate in practice. The branded card earns 2 points per dollar on all Ulta purchases and 1 point everywhere else. The store card earns 3 points per dollar only at Ulta and 1 point elsewhere. That three-point rate sounds better on paper until you factor in the fact that the store card carries a variable APR hovering around 26.99% versus the branded card's introductory 0% for 12 months on purchases. If you carry a balance, the math flips immediately. I keep both cards. The branded card lives in my digital wallet for routine purchases where I want the grace period. The store card sits in my physical wallet exclusively for big beauty hauls above $100 where that extra point per dollar actually matters. It takes about three minutes to set up that mental rule, and it saves me roughly $40 to $60 a year on average spend.
What Nobody Tells You About the Sign-Up Bonus
Ulta regularly runs promotions offering 20,000 bonus points after spending $150 in your first 90 days. That sounds generous. It translates to maybe $20 in rewards depending on how you redeem. The real trap is that those 20,000 points expire after one year, and most people don't realize they have to actively redeem them through the account dashboard. They don't disappear automatically, but they also don't show up as spendable credit at checkout. I watched a coworker lose 15,000 points last January because she assumed the system would handle it. It didn't. Another thing nobody mentions is that the rewards earnings pause during billing cycles where you carry a balance. If your statement balance isn't paid in full by the due date, you earn zero new points on that cycle. This isn't a penalty, it's just how Comenity structures their programs. It caught me off guard during a particularly rough month last spring when I had medical bills stacked up and suddenly noticed my Ulta spending wasn't generating any new rewards despite normal purchase volume.
Get the Full Details

The Return Problem and How I Work Around It
Returning items purchased with Ulta credit is straightforward until it isn't. When I returned a $95 foundation that I'd bought two months earlier using my store card, the credit appeared as a pending adjustment rather than an immediate balance reduction. The system held that adjustment for five business days before it posted. During those five days, my available credit stayed locked. I tried to make an urgent purchase for a gift and hit my limit because that credit was invisible to me in real time. The workaround is simple but unintuitive: pay down your balance directly through the app before initiating a return. Not after. Before. If you reduce your balance manually, the return credit applies faster and you recover your available limit sooner. It adds a step but saves you from awkward moments at checkout.
When Ulta Credit Completely Fails You
There are scenarios where the card becomes worse than useless. Third-party sellers on Ulta's marketplace don't earn rewards. Limited edition collabs sold through partnership pages sometimes exclude credit card payments entirely. I once tried to use my card for a vintage perfume collection launch that only accepted PayPal and Apple Pay. The checkout page made it clear about ten seconds after I started entering my information. The annual fee on the branded card is zero, which sounds like a selling point until you compare it to cards like the Amex Gold or Chase Freedom Flex where you can reliably extract $120 to $200 in annual value from signup bonuses alone. Ulta's card returns maybe $40 to $60 annually if you're a dedicated shopper. That's break-even at best, negative if you forget to redeem your rewards. If you shop at Ulta once or twice a year, skip the application. Use a cashback card instead and move on. The card only makes mathematical sense if you're spending at least $600 to $800 annually at Ulta consistently over multiple years. Anything below that threshold and you're leaving money on the table compared to a generic rewards card.
Practical Steps to Open and Use the Card
Go to ulta.com and navigate to Ultamate Rewards > Credit Cards. Click Apply Now. You'll need your Social Security number, annual income, and housing status. Approval decisions are instant for most applicants, though some get referred for manual review which can take three to five business days. Check your email and your mail for the physical card. Set up mobile alerts before your first billing cycle starts so you know exactly when payments are due. Download the Ulta app and link your card immediately. Enable push notifications for your rewards balance. Check it every Sunday night while you're already scrolling through your phone. This habit alone prevented me from losing over 30,000 points across two separate cards in the past eighteen months. The points dashboard in the app is clean and shows expiration dates clearly if you actually look at it instead of ignoring it until it's too late. The rewards redemption window opens at 1,000 points for a $10 certificate. You can combine multiple certificates in a single transaction. I've redeemed six certificates at once for a $60 purchase without any issues. There's no minimum purchase requirement beyond the points threshold, so you can burn down small balances gradually over time rather than saving up for one big redemption event.