Getting Into Your Ally Auto Account Without Losing Your Mind
Ally Auto handles billions in auto financing, and their online portal is actually not half bad if you know where everything sits. I've been managing my own loans through their system for years, and I've watched the interface shift around enough times to have opinions about it. The main complaint people have isn't that Ally Auto is broken, it's that they don't clearly explain what certain features do or where to find them. Once you're in, it's straightforward enough. The login page is at ally.com, but here's the thing nobody tells you: Ally Auto accounts and Ally personal loan accounts are separate login tracks. If you signed up for a mortgage or a HELOC through Ally, your credentials won't work for your auto loan portal. You need to go specifically to the auto section or use the auto-specific enrollment path. I learned this the hard way when I tried logging in with my mortgage credentials and spent twenty minutes on the phone with support before someone pointed out I was on the wrong track entirely. Make sure you're using the right credential set from the start, or you'll waste time. When you first log in, the dashboard presents your active auto accounts with current payoff balances, next payment due dates, and autopay status all on one screen. This is where most people stop looking. The useful stuff is buried under a few menus. Click into an account and you'll find options for making one-time payments, setting up autopay, requesting payoff statements, and accessing your original loan documents. The document retrieval system is honestly the best part, it replaces what used to require fax requests and waiting three weeks for paper mail.
One thing that trips people up constantly is the difference between autopay discount and standard billing. Setting up autopay gets you a quarter point rate reduction on your loan, which sounds small but on a thirty thousand dollar loan over six years adds up to real money. The autopay setup page sometimes defaults to showing only checking accounts, and if you want to use a savings account or another bank you might not see it immediately. Scroll or switch the dropdown. I recommend using Ally's own account for autopay because the timing is more predictable, withdrawals process faster on the due date than external bank transfers tend to. The mobile app mirrors most of the web functionality but leaves out a couple of features. You can't pull payoff statements from the app, and document retrieval is limited. If you need official documents for tax purposes or refinancing, do it on the desktop site. The app is fine for checking balances and making a quick payment. It's also worth noting that the app occasionally fails to sync account data within the first five minutes after you make a payment through the website, so don't panic if your balance looks wrong on mobile right after you pay, refresh or wait a bit. Two-Factor Authentication is mandatory now and it's not optional no matter what some help threads claim. You can use the Ally mobile app as your authenticator or receive SMS codes. The SMS option is less secure and frankly slower because you're always waiting for a text that may or may not arrive depending on your carrier. Use the app-based authenticator, it's instant and you stop dealing with that step entirely on return visits if you check the remember device box.
Here's an edge case that probably won't be covered in any FAQ: if you have a co-borrower on your auto loan, neither of you can add the other as an authorized user on the online account without calling Ally directly. There's no self-service toggle for this. I encountered this when my partner needed to see the payoff balance for a refinance comparison and couldn't access the account. We ended up on hold for forty minutes. The workaround if you need shared access is to split the loan, which requires a formal request and credit review, or just share login credentials if you trust each other fully. Nobody likes that second option but it happens. Another thing people miss is the ability to request a change of loan servicer or transfer the account within Ally's own system. If you bought your car through a dealership that partners with a different Ally entity, your account might be sitting with a sub-servicer that has a worse online experience. You can sometimes initiate a transfer through the portal by contacting support and asking for the primary Ally Auto servicing group. It doesn't always work depending on your loan type and origination date, but it's worth trying if the interface you're dealing with is clunky or missing features. Password resets take about three minutes if everything is working normally, but I've seen cases where the reset email lands in spam or gets delayed, especially if you recently changed your email address on file. If you're locked out, don't just keep clicking forgot password, that can sometimes trigger a temporary lockout period where Ally blocks further attempts for security reasons. Wait ten minutes and try again, or call support directly to expedite it.
Get the Full Details
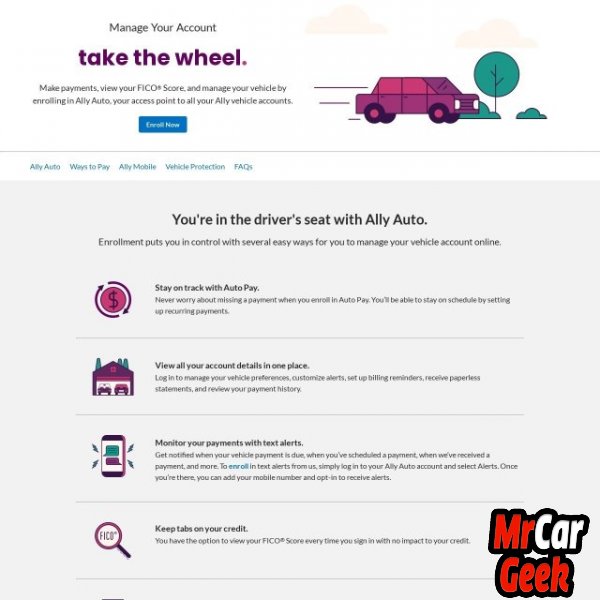
The portal does have a few genuine quirks. The payment confirmation screen doesn't always update in real time, so if you submit a payment and immediately check your balance, it might still show the old number. Give it fifteen to thirty minutes. The download button for your loan agreement PDF sometimes opens the file in the browser instead of prompting a save, which is annoying if you need a local copy. Just press Ctrl+S when it opens in the browser tab. Overall, Ally Auto's login system works. It's not the prettiest interface you'll use, and there are enough friction points that you learn to navigate around them rather than fighting them. Set up autopay, use the app for authenticator codes, do paperwork on desktop, and give yourself extra time the first few times you log in until you learn where everything is. The convenience argument mostly holds up once you get past the initial learning curve.