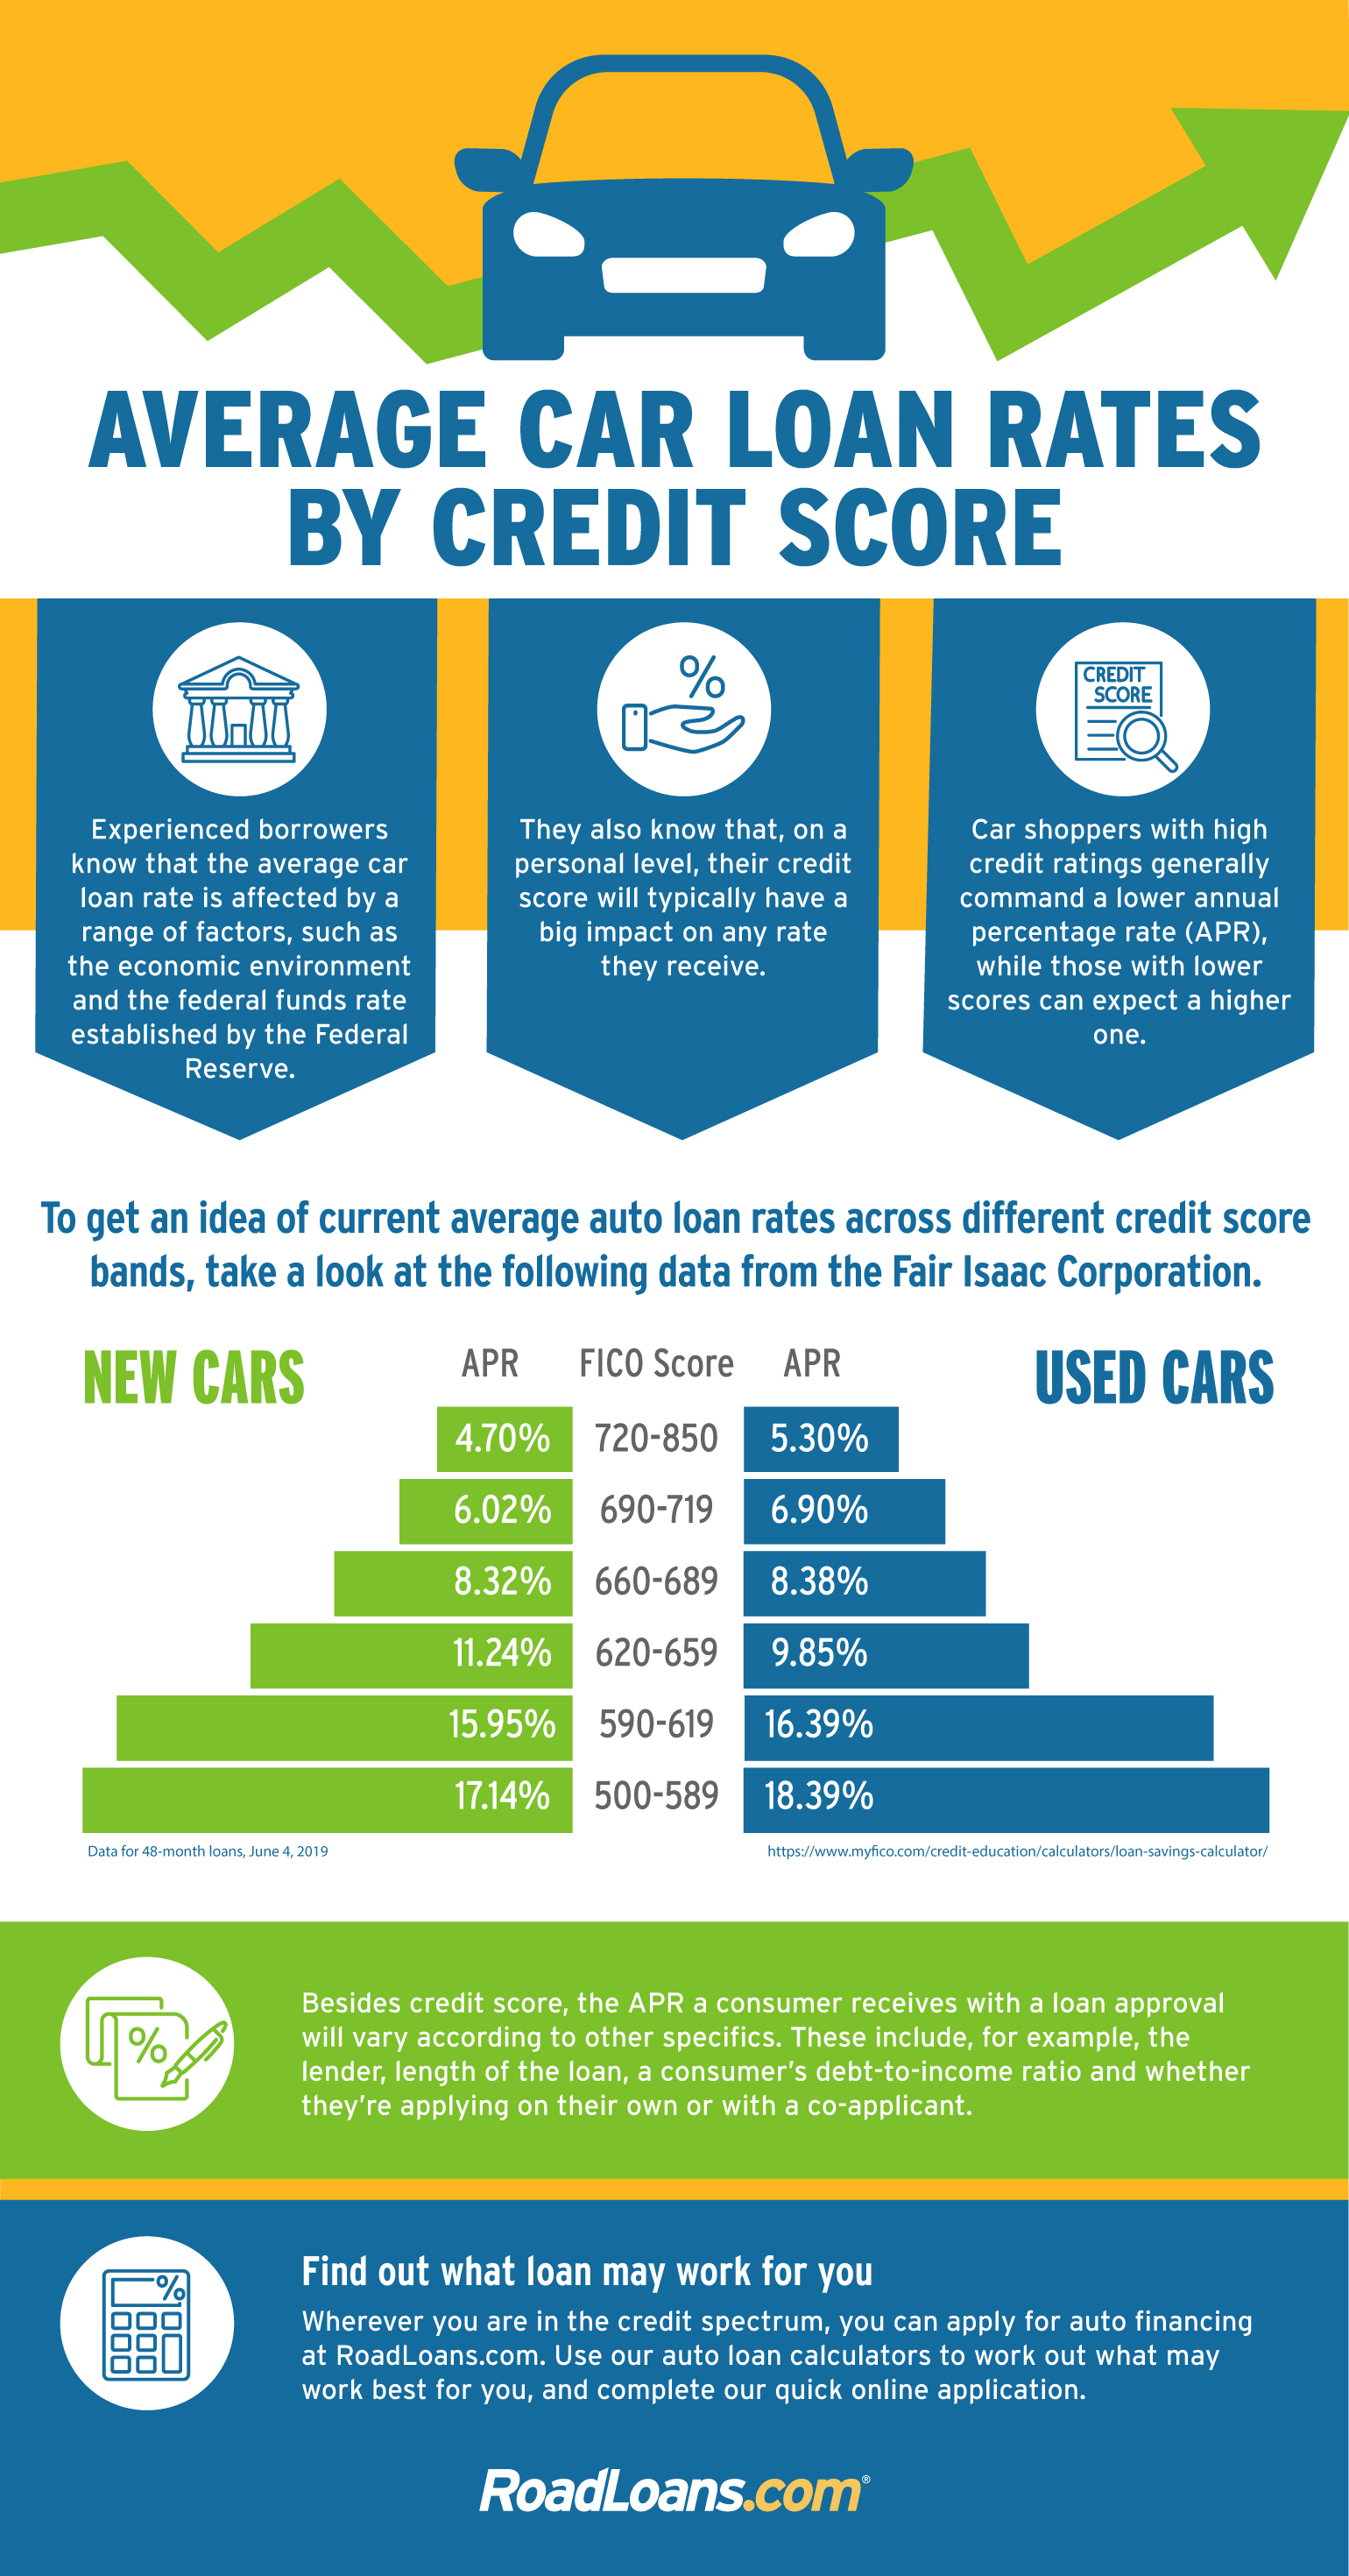
Getting a decent rate on a used car loan is harder than it should be, and most people don't actually know why their rates keep getting bumped up
USA Auto Finance is a legitimate lender that specializes in subprime and near-prime auto lending. They work with people who have less-than-perfect credit, which means they can offer competitive rates for that segment of the market. But the rates you actually qualify for depend on a stack of variables that most borrowers never learn to optimize. The first thing to understand is that USA Auto Finance doesn't publish a single rate. Their rate sheet runs from roughly 5.99% to over 21%, depending on credit tier, loan term, and whether the vehicle passes their age and mileage requirements. A 2016 Honda Civic with 85,000 miles and a 680 credit score will get a completely different number than a 2011 Ford F-150 with 142,000 miles and a 620 score. The gap between those two loans could be six to eight percentage points, which translates to hundreds of dollars per month and thousands over the life of the loan. Here's how the application process actually works. You start on their website and enter the basic vehicle and loan details. They run a soft credit pull first, which doesn't touch your score. Then you provide income documentation, employment verification, and your down payment amount. The hard inquiry happens only when you're ready to commit to a specific rate and terms. This soft-pull-first model is one of the main reasons people go with them instead of walking into a dealership credit desk blind.
I ran into a specific edge case about two years ago that took me a while to figure out. A client of mine had a 640 credit score but had recently paid off a collections account for about $800. The collections entry was still showing as active on all three credit bureaus, which tanked his qualifying rate. He expected USA Auto Finance to automatically refresh his report, but they don't do that on their own. The workaround was filing a dispute with each bureau through their respective online portals, attaching the payoff documentation, and waiting about 30 days for the accounts to update. Once the collections tradeline aged and dropped to zero balance status across the board, his rate improved by roughly 3.2 percentage points. He wouldn't have known to go that route without knowing how FICO scoring weighs recent derogatory marks against closed accounts. Another thing people miss is the relationship between loan term and rate. USA Auto Finance typically offers terms from 24 to 72 months. Shorter terms generally come with lower rates because the lender's risk exposure is shorter. But here's the counter-intuitive part: a 60-month loan at 9% can sometimes be cheaper in total dollars paid than a 36-month loan at 7% if the monthly payment on the shorter term stretches you too thin and forces you into a higher down payment you can't actually afford. The key metric isn't the rate alone, it's the total cost including any origination fees and the impact on your monthly cash flow. Origination fees are another hidden cost that matters more than most borrowers realize. USA Auto Finance structures some of their products with upfront fees ranging from 1% to 3% of the loan amount. On a $15,000 loan, that's $150 to $450 coming out of your proceeds or rolled into the balance. Always ask for the fee disclosure before you accept a rate quote, because the advertised rate plus the fee tells a different story than the rate alone.
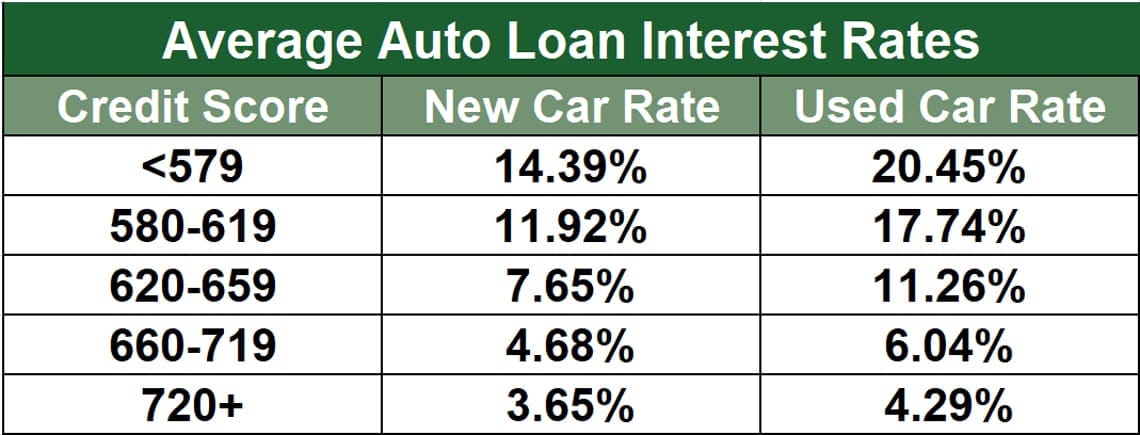
Vehicle eligibility is where a lot of applications hit a wall. USA Auto Finance has restrictions on vehicle age and mileage. Most lenders in their space won't finance cars older than about 10 years or with more than 120,000 to 150,000 miles, depending on the model. Trucks and SUVs sometimes get slightly more lenient treatment than compact cars because they tend to hold value longer in the subprime market. If your vehicle is near the cutoff, the system may reject it before a human ever reviews your file. The workaround is getting pre-qualified with a slightly newer vehicle in mind and then shopping around for the actual car, rather than falling in love with a specific one that won't qualify. Down payment requirements are another area where expectations often clash with reality. USA Auto Finance typically wants a minimum of 10% down for most subprime profiles. That's not as steep as some alternative lenders that demand 20% or more, but it's higher than what prime lenders usually require. If you're bringing less than 10%, your rate will jump significantly, and in some cases you may not qualify at all. A gift letter from a family member for the down payment is acceptable, but they'll want written documentation proving the funds aren't a loan themselves. Paperwork like that should be prepared before you apply rather than after, because missing documents are the most common reason applications stall. There are scenarios where USA Auto Finance simply isn't the right path. If your credit score is above 700, you should look elsewhere first. Prime lenders like credit unions and national banks will offer you noticeably better rates on used cars, often by 2 to 4 percentage points compared to what a subprime-focused lender can do. USA Auto Finance is built for the middle and lower end of the credit spectrum, not the top. Sending a 720 score applicant through their system is just wasting everyone's time.
Get the Full Details
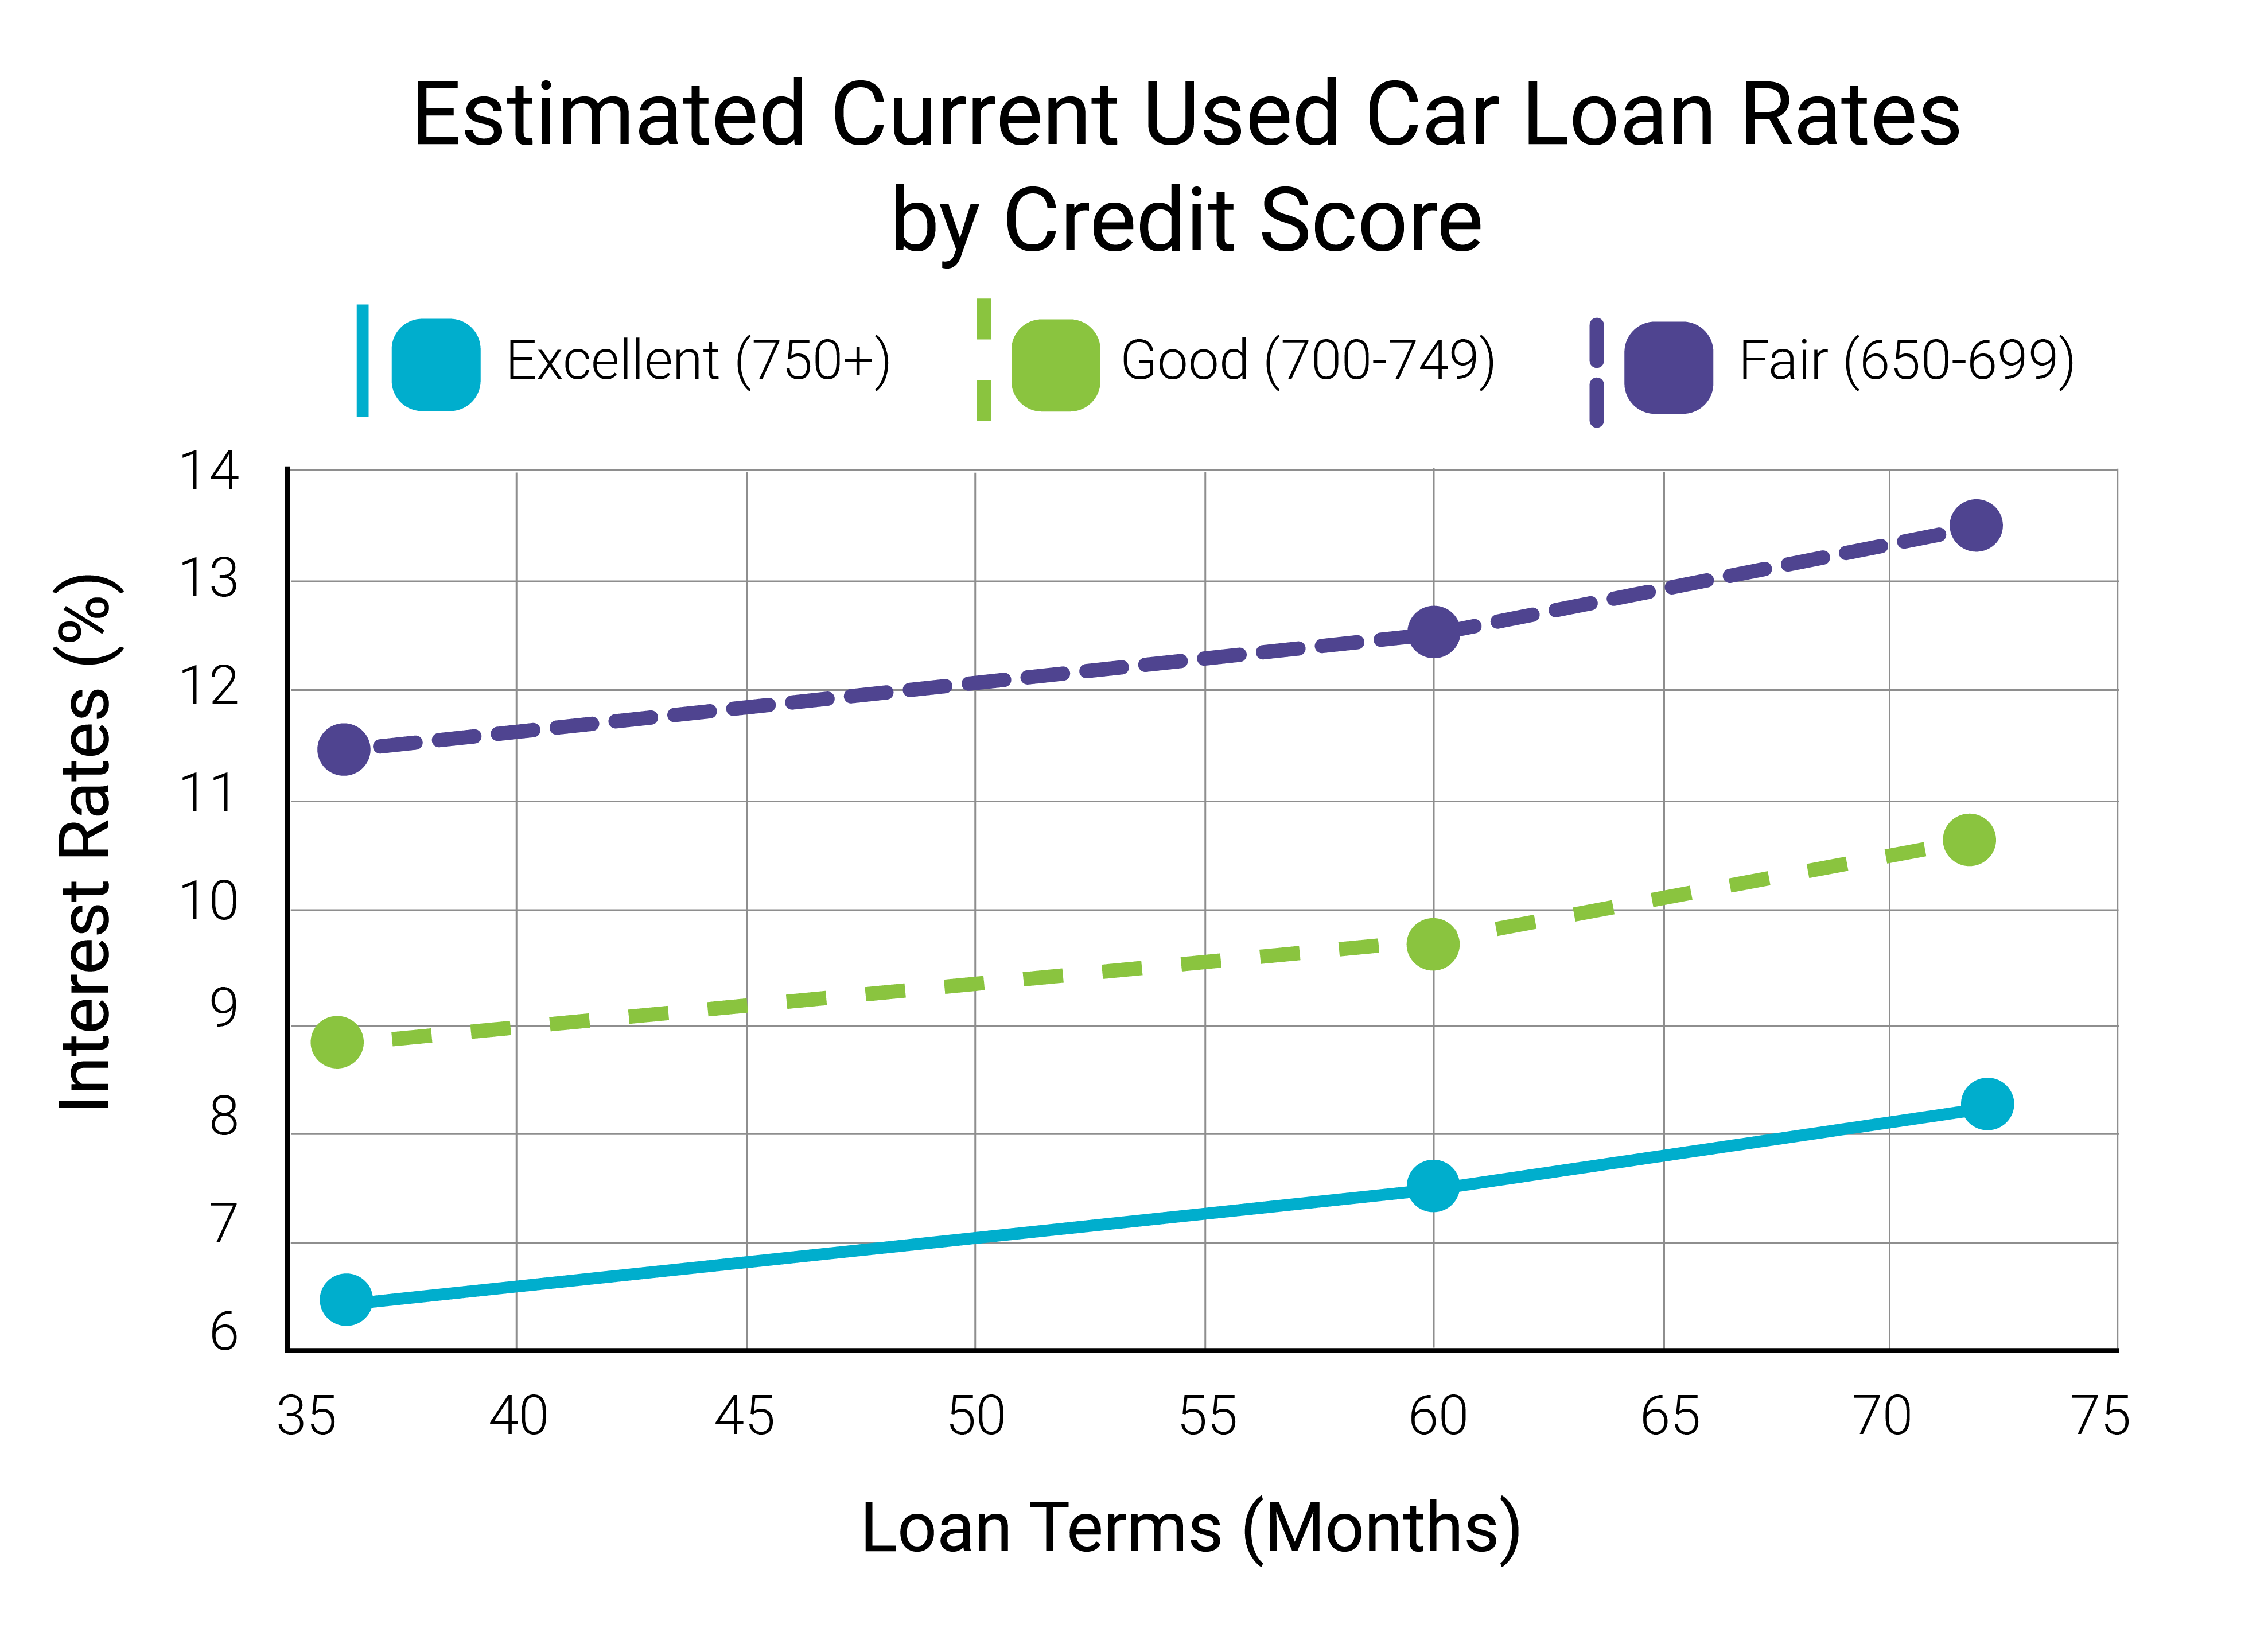
Similarly, if you need financing for a vehicle that's a salvage title or has a brand that most mainstream lenders won't touch, your options narrow considerably. Some subprime lenders handle rebuilt titles, but USA Auto Finance's underwriting guidelines tend to favor clean titles. If you're dealing with a branded title situation, you'd be better off searching specifically for lenders who advertise salvage-title auto loans rather than assuming USA Auto Finance can accommodate it. The application timeline is worth mentioning because nobody likes sitting around waiting. A complete application with all documentation ready typically gets a decision within one to three business days. Incomplete applications drag on indefinitely because the underwriter has to cycle back for missing items. Having your last two pay stubs, proof of residence, and your Social Security number ready before you start the form cuts the turnaround time substantially. One final practical note about rate locks. USA Auto Finance doesn't advertise a formal rate lock period the way mortgage lenders do, but once you receive a written rate quote, it's generally valid for about 30 days provided your financial profile hasn't changed. If you see your credit score drop or pick up a new debt between the quote and closing, the rate can be renegotiated or pulled entirely. Monitor your credit during that window if you're on the edge of a tier change.
The whole process from start to funded loan usually takes one to two weeks for straightforward cases. If you're dealing with self-employment income, multiple job changes, or vehicles near the age limit, plan on two to three weeks. Going in prepared with every document and a clear understanding of your credit profile makes the difference between a smooth close and a months-long back-and-forth.