Working with NFCU auto loan rates requires understanding how their pricing actually works
Navy Federal Credit Union is a member-owned institution with a membership structure that affects who qualifies and at what rate. Their auto loan pricing varies based on credit score, loan term, whether it is a purchase or refinance, and whether you have an existing relationship with the credit union. The rates you see advertised are usually the best-case scenario for someone with excellent credit and a short loan term. Most people do not fall into that category. The practical process starts with confirming your membership eligibility. NFCU is open to military members, veterans, Department of Defense employees, and their families. If you qualify, you need to open a share account first, which requires a minimum of $5. This is not something to overlook because the auto loan application system checks membership status in real time. I ran into this once when a friend tried to apply before opening a share account. The application stalled at the membership verification stage and he had no idea why. Took about twenty minutes to resolve once we understood what was happening. From there, the actual rate determination involves several inputs. NFCU uses a risk-based pricing model where your credit tier maps to a rate band. They do not publish their rate tables publicly. You can only see what they offer after you complete a soft inquiry on their website. The soft pull does not affect your credit score, which matters because applying at multiple lenders within a short window can temporarily lower your score by a few points. I have seen borrowers lose a quarter point on their rate between their first and second hard inquiry application because of this timing issue.
The loan term has a non-obvious effect on your rate. Shorter terms generally carry lower rates, but not linearly. A 36-month loan might be significantly cheaper per annum than a 48-month loan, while the jump from 48 to 60 months is usually smaller. Going beyond 60 months on an NFCU auto loan often means losing access to their best rate tier entirely. They tend to reprice or even decline applications above 72 months depending on credit profile. This is worth knowing if you are tempted by those lower monthly payments on a seven-year loan. Discounts are where most people leave money on the table. NFCU typically offers an automatic discount for setting up automatic payments, usually around 0.25 percent off your rate. There is sometimes a relationship discount if you already hold other products with them, like a checking account or a certificate of deposit. The relationship discount can range from 0.25 to 0.50 percent depending on what you hold and how long you have held it. I once helped someone who had been banking with NFCU for three years and simply never asked about the relationship discount. They ended up paying roughly $340 more over a 60-month loan than they needed to. Another counter-intuitive detail: NFCU sometimes offers better rates to borrowers with slightly lower credit scores than you would expect if those borrowers have a strong payment history with the credit union. Their internal scoring considers relationship behavior, not just the FICO number from the bureaus. A borrower with a 680 score and a five-year checking relationship might get quoted a better rate than a newcomer with a 700 score and no history. The tradeoff is that you have to be willing to consolidate your banking with them to benefit from this. If you are not interested in that, it is not a useful advantage.
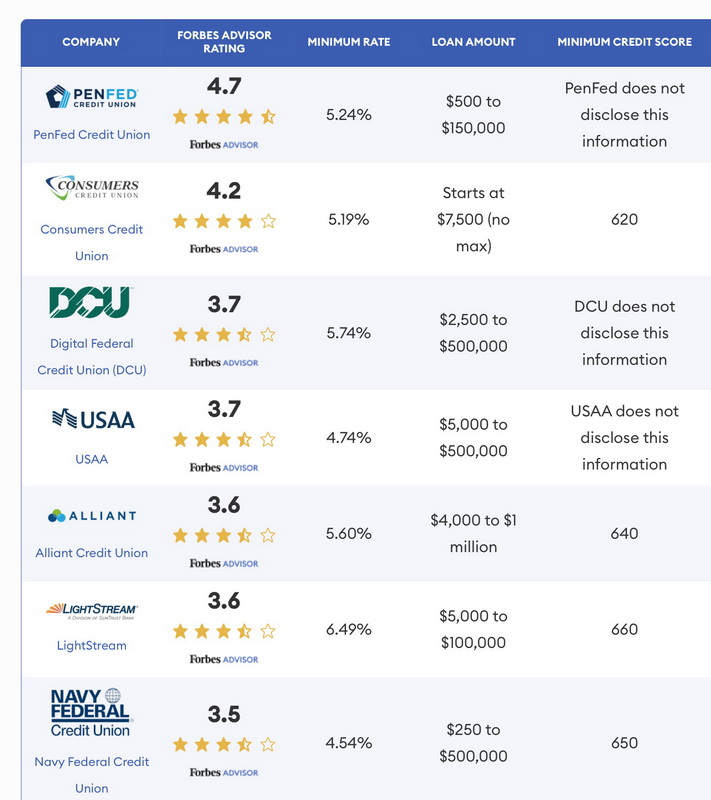
When you are ready to apply, you can do it online through their member portal or visit a branch if you have access to one. The online application takes roughly 10 to 15 minutes if your documents are organized. You will need your driver's license, proof of income, and information about the vehicle including the VIN. The VIN is important because NFCU uses it to determine the loan-to-value ratio and whether the vehicle qualifies under their age and mileage guidelines. They generally finance vehicles that are under 10 years old with fewer than 125,000 miles, though these numbers shift based on credit quality and other factors. The approval timeline is usually fast. Many applicants receive a decision within minutes during business hours. Funding typically happens within one to three business days after approval. If you are refinancing an existing auto loan, the process is similar but involves paying off the current lender directly. I have seen refinance deals stall because the payoff amount from the old lender was not requested early enough. The new lender needs that figure to structure the refinance correctly, and delays in obtaining it can push funding back by a week or more. There are limitations you should be aware of. NFCU is not a national bank in the traditional sense, so their rates are not always the lowest available on the market. Regional credit unions and online lenders like Ally or Discover sometimes undercut NFCU on rate alone, particularly for borrowers with excellent credit. The advantage of NFCU tends to show up for members who value the relationship perks, the ease of dealing with a familiar institution, and the willingness to work with non-traditional credit profiles. If your only goal is the absolute lowest number on a spreadsheet, you should shop at least two other lenders before committing.
Get the Full Details
Another practical bottleneck is that NFCU does not offer co-borrower options on auto loans in the same way some institutions do. You can have a co-applicant, but both parties must meet the membership and credit requirements. This eliminates a common workaround that people use with other lenders when one applicant has weak credit. If you are in that situation, you are better off applying individually or looking at a dealer-financed option that allows a co-signer, understanding that dealer financing often comes with higher rates to offset their risk. If you decide to proceed, start by logging into your NFCU account or creating one if you do not have it. Run the rate estimator on their website using a soft inquiry to get your personalized rate band. Compare that number against at least two other lenders before you lock anything in. Have your VIN ready. Set up automatic payments to capture the discount. And if you have a relationship with NFCU, ask explicitly about any relationship discounts that may apply to your specific profile before you accept the first quote they give you.