Buying a Kubota means looking at money before you look at specs
Most people walking into a Kubota dealer for the first time think they just need to pick a model and hand over a deposit. That is a rough way to start. The financing side of a tractor purchase quietly determines whether you will actually afford the thing you just bought, and it is where dealers make the most margin. I have sat across from loan officers at equipment shows and watched experienced farmers get handed rates that were three points higher than what was available, just because they did not ask the right questions in the right order. Here is how you actually approach this. You do not walk into a dealership and ask for a rate. You walk in with a rate already in your pocket, or at least a competitive offer from somewhere else. The process takes about twenty minutes if you are prepared, and maybe two hours if you are not.
Unlock The Best Kubota Tractor Financing Options And Rates For A Green Harvest
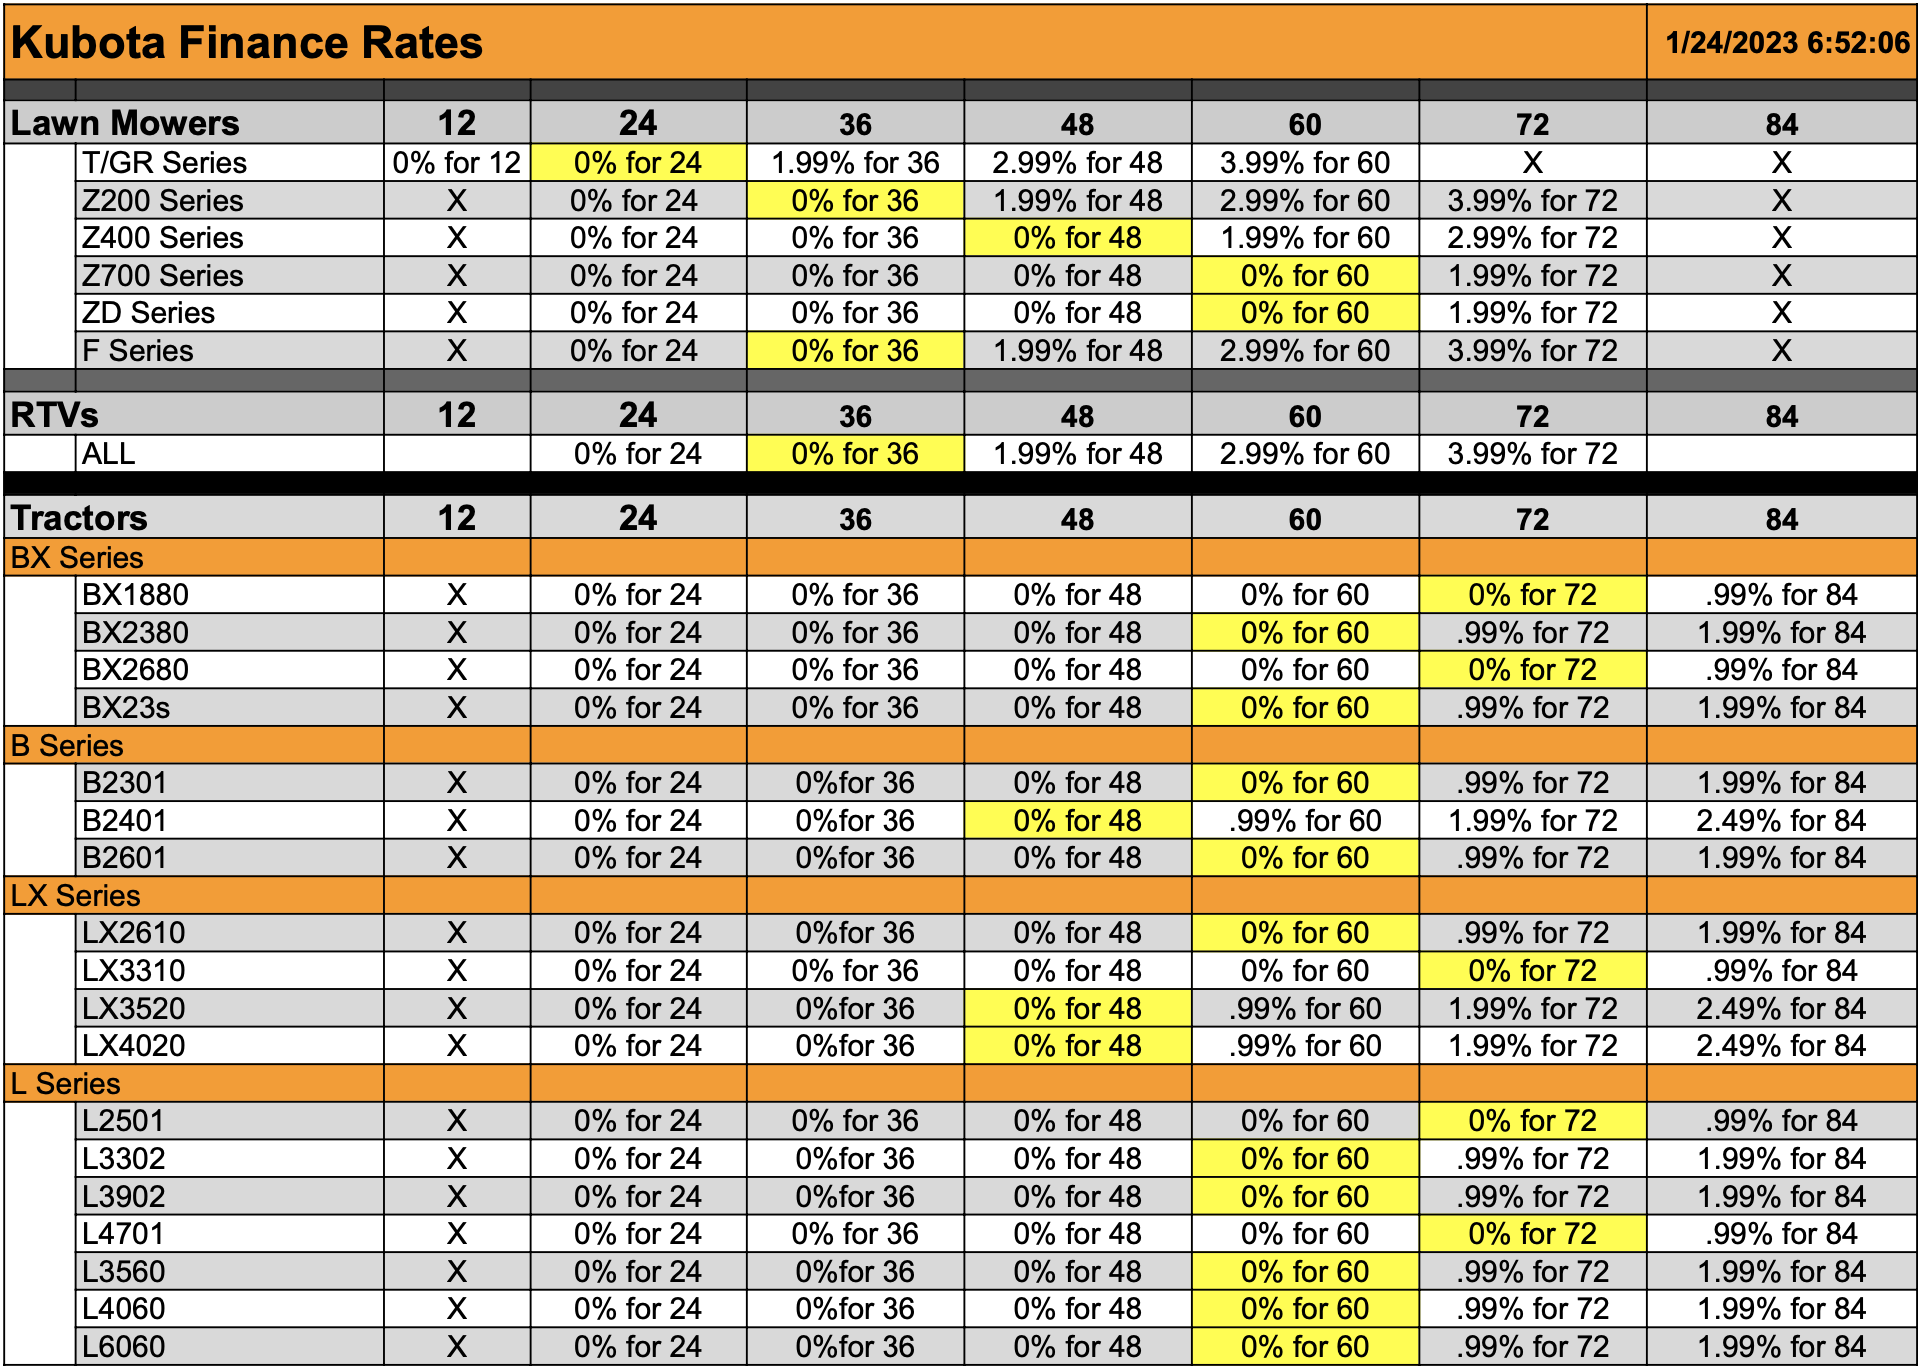
Dealer financing for Kubota equipment runs through Kubota Credit Corporation, which is the OEM lender. Their standard rates for new equipment typically land between 5.99% and 8.99% APR for qualified borrowers on terms of 36 to 72 months. That is the baseline. What most people do not know is that Kubota occasionally runs promotional rate programs that drop down to 0% or 3.9% on select models, usually during Q1 and Q4. These promotions are not advertised prominently. They are listed on the Kubota Tractor Corporation website under special offers, and they change every quarter without much fanfare. I learned this the hard way in 2022 when I was shopping a M7-172 and the sales manager told me the best rate available was 7.49%. I asked to see the current Kubota Credit promotional sheet. It turned out there was a 2.9% rate running on that exact model through the end of the month. He had not offered it because he assumed I would not know to ask. Beyond the OEM route, there are several other channels worth comparing before you commit. Agricultural credit unions in rural states like Iowa, Nebraska, and Kansas routinely offer equipment loans in the 4% to 6.5% range for members with good credit. The process is slower—expect five to seven business days for approval—but the total interest paid over a 60-month term on a $60,000 tractor can be $2,000 to $4,000 less than dealer financing. Local community banks also carry ag loan products, though their rates tend to track closer to prime plus 1.5 to 2.5 points, which usually lands around 7% to 9% depending on the Fed rate at the time. There is a specific complication with Kubota tractors that catches a lot of buyers off guard. If you finance through Kubota Credit and the tractor qualifies for a factory warranty, the warranty stays intact regardless of who services it. That is not true with every brand. With some OEM lenders, deviating from their preferred service network can void portions of the coverage. Kubota does not do this, which matters if you plan to handle your own maintenance. It also means there is no penalty for paying off early. Kubota Credit does not charge prepayment penalties on equipment loans, so if you sell the tractor in year three with a balanced payment, you save on interest without a kickback fee. This is worth confirming in writing before you sign, because loan documents sometimes bundle third-party add-on products that do carry prepayment fees.
Another detail that rarely comes up in initial conversations is the difference between a secured equipment loan and a general-purpose personal line of credit used to buy the tractor. A secured loan uses the tractor as collateral and carries a lower rate, but it also means the lender can place a lien on the VIN. If you are financing multiple pieces of equipment across different lenders, those liens stack. A commercial lender I worked with once had to jump through three months of paperwork to clear a title on a used KX080-4 because a prior owner had refinanced it through a regional bank that never released its lien properly. Secured equipment loans are cheaper, but they require disciplined record-keeping. Keep every lien release document in a single folder from day one. For buyers with weaker credit profiles, dealer financing is often the only realistic option, but the rates jump significantly. Borrowers in the 620 to 660 credit range can expect 10% to 14% APR on Kubota equipment through the dealer. If your score is below 620, you may still get approved but rates can exceed 16%, and the monthly payment on a $45,000 unit over 60 months at 16% is roughly $1,090 compared to about $820 at 8%. The difference is substantial enough that it is usually better to rebuild credit for six months before buying rather than lock into a high-rate loan that eats cash flow for the next five years. A local operator near me did exactly this. He delayed his M8-281 purchase by eight months, paid down two credit cards, and came back with a score in the 690s. His rate dropped from an estimated 13.5% to 6.99%. That single move saved him nearly $3,200 in interest over the loan term. The negotiation itself works differently than it does for consumer goods. Equipment pricing has a predictable spread. The dealer's cost on a new Kubota is roughly 15% to 20% below sticker, and the finance reserve—the kickback the dealer earns from the lender for placing the loan—is typically 1% to 2.5% of the loan amount. That means if you bring in an approved rate from a credit union at 5.5%, the dealer loses the finance reserve. They may push back. The workaround is straightforward: ask the dealer to match or beat your outside rate, and if they cannot, walk away and purchase elsewhere. Kubota dealers are accustomed to this conversation, and most will absorb a smaller margin rather than lose the sale. I have seen it happen. The dealer called their finance manager, came back with a rate 0.25% lower than my credit union offer, and closed the deal the same afternoon.
Get the Full Details

There are scenarios where none of this advice applies. If you are buying used equipment from a private seller, Kubota Credit is not an option. You are looking at a standard secured vehicle loan or an unsecured personal loan, and rates reflect that risk premium. Private-party equipment loans from banks like Farmers National Bank or AgFirst typically run 7.5% to 11% depending on the tractor's age, hours, and your credit. Another hard limit: if you are a seasonal borrower with irregular income, most conventional lenders will require a debt-service coverage ratio above 1.25x, which disqualifies many small-scale or part-time operators. In that case, a lease-through-a-dealer arrangement can sometimes work because the monthly payment is treated as an operating expense rather than a financed liability, though lease rates are generally 1% to 2% higher than equivalent loan rates over the same term. The practical takeaway is simple. Get your credit score before you shop. Pull a current report from AnnualCreditReport.com. Check that your debt-to-income ratio is under 40%. Secure a pre-approval from a credit union or agricultural lender. Then go to the dealer with that offer in hand and negotiate from there. Do not let them set the financing terms first. The numbers on the page are negotiable, but only if you know what the alternative is.