Getting through Dutch health insurance without losing your mind
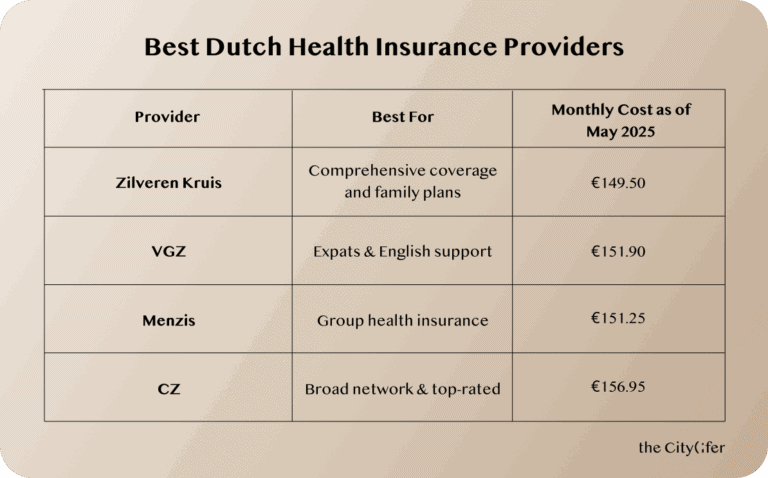
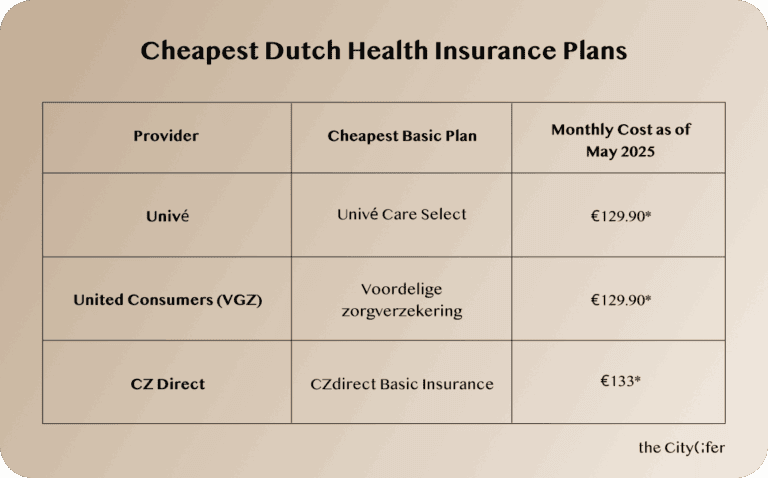
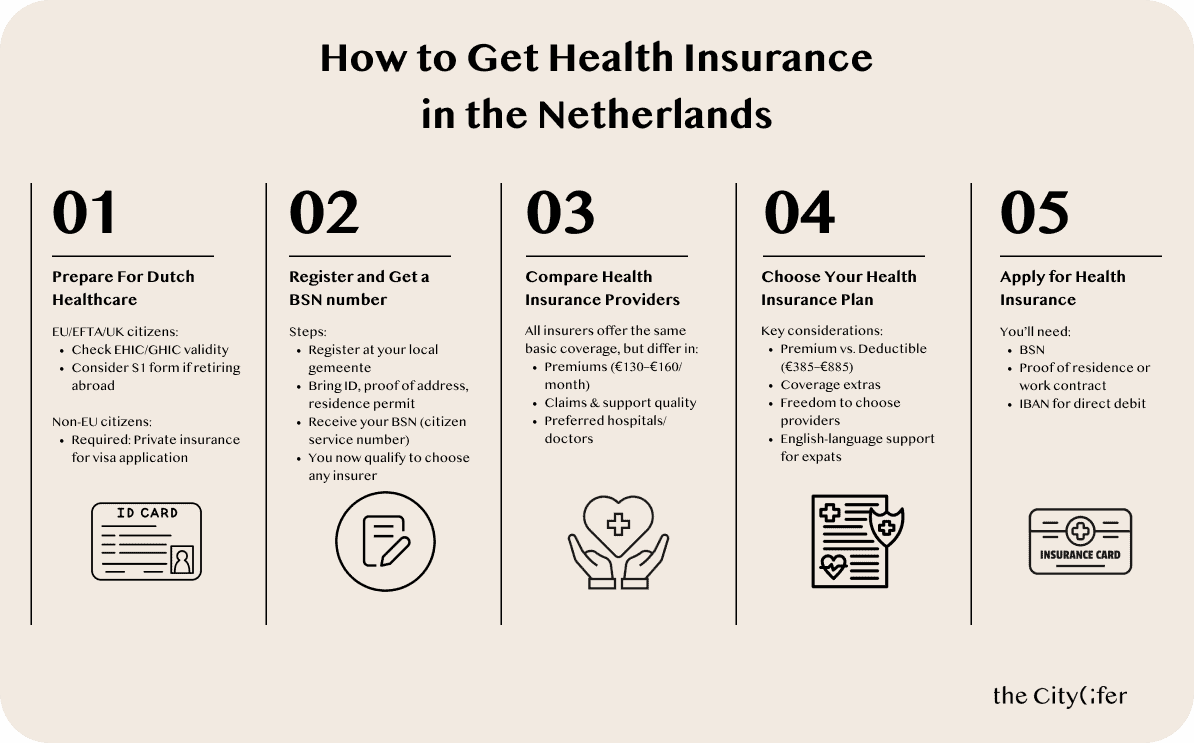
I spent about three weeks sorting out my own coverage when I moved here, and another two untangling why my wife's claims kept getting rejected. Most people treat this like it's straightforward. It isn't. The system looks simple on paper but falls apart the moment you actually try to use it. The Dutch system has two layers. The basic package, or basisverzekering, is legally required for everyone and covers the same core services no matter which insurer you pick. What changes between providers is the service layer, premium price, and the digital tools they offer. Then there's the aanvullende verzekering on top, which covers things like physiotherapy, dental check-ups, and alternative treatments. That's where most people lose money because they buy add-ons they don't actually need. The main insurers you'll run into are Menzis, Zilveren Kruis, VGZ, NHN, Zuidoog, and Ditzo. Zilveren Kruis and Menzis are the two biggest by membership. Ditzo is the cheapest but the one with the fewest physical offices. If you value walk-in support that matters. A lot of people don't realize they can switch mid-year during the open enrollment period, usually in September, and change providers for the following calendar year. Missing that window means you're locked in until next September unless you have a qualifying life event like moving house or changing income brackets below the care expense threshold.
I spent two hours on hold once trying to get a prior authorization approved for a specialist referral because the insurer's online portal kept throwing a code error. The workaround was calling the provider's office directly and having them submit the form on my behalf. It cuts through the automated queue entirely. Not something any brochure tells you. Here's what the basic package actually includes and what it doesn't. Covered: GP visits, hospital care, prescription medication, maternity care, mental health services up to a certain limit, and ambulance transport. Not covered: routine dental care for adults over twelve, physiotherapy outside of specific conditions, glasses and contacts beyond the standard allowance, and most alternative medicine. The dental part trips people up constantly. You pay out of pocket for cleanings and fillings unless you have a supplementary plan, and those can run three to eight hundred euros a year depending on the level. Premiums vary by provider but also by age, region, and whether you choose a reimbursement or indemnity model. The indemnity model, known as naturaris, means the insurer pays the provider directly. Reimbursement, or restitutie, requires you to pay upfront and claim it back. Naturaris typically costs fifty to a hundred euros less per year. The catch is that some specialists and hospitals only work under the naturaris contract, which limits your choice slightly. For most routine care it doesn't matter. For specialist referrals it can slow things down by a week or two while paperwork gets sorted.
The deductible, or eigen risico, is currently seven fifty euros per year for most people. This is mandatory and applies to non-essential services within the basic package. Some services bypass this entirely, including GP visits and maternity care. I learned this the hard way when I expected my physical therapy session to be covered and got a bill for seventy-five euros. The therapist was in-network but the specific treatment protocol wasn't flagged as exempt from the deductible. Always confirm with the provider before the first appointment whether the service falls under the deductible waiver list. There's a government scheme called zorgtoeslag that subsidizes premiums for lower and middle-income earners. If you qualify, it can knock two hundred to four hundred euros off your annual cost. You apply through the tax authority, and it's automatic if you already file Dutch taxes. Don't skip this step. I've seen people pay full premium for years because they didn't know they were eligible. When comparing providers, look past the headline premium. Check the bonus programs. Some insurers offer discounts if you don't make claims, get annual health screenings, or use their digital platforms for prescriptions. Zilveren Kruis and Menzis both have meaningful loyalty bonuses that can reduce your effective cost by a hundred euros or more over three years. Ditzo and other budget brands rarely match these programs because their margins are already thin.
Get the Full Details

The one area where the system genuinely breaks down is cross-border care. If you need treatment in Germany or Belgium under EU coordination rules, the reimbursement process is slower and more paperwork-heavy than domestic claims. I had a colleague who spent four months chasing a hundred-euro reimbursement for a routine blood test because the German lab didn't have the right billing code registered with her Dutch insurer. The fix was to email the insurer's international department with the original invoice, a translation, and a form they'd never mentioned on their website. Takes about twenty minutes if you have the documents. Could take six weeks if you don't know the form exists. Bottom line: pick a provider based on whether you want the lowest premium or the most comprehensive supplemental coverage, not the brand name. Check the exclusions in the supplemental plan before you sign. Call your current insurer to confirm the deductible status of any planned procedure. Apply for zorgtoeslag. And keep all receipts for at least five years because audits do happen, even for ordinary claims.