Paying Your JCPenney Credit Card Without Losing Your Mind
JCPenney stopped issuing new credit cards in 2019. The card that exists today is a closed loop at this point, and most people holding one don't even realize how limited it is anymore. If you have the card sitting in your wallet and you're trying to figure out whether it's worth keeping, or how exactly you pay it off each month without getting burned, this guide covers what actually happens when you use it. The JCPenney Credit Card is a store card issued by Synchrony Bank. That means it works exclusively at JCPenney stores and on jcp.com. It is not a general-purpose Visa or Mastercard. You cannot use it at grocery stores, gas stations, or anywhere outside the JCPenney ecosystem. This limitation is the single most important fact about this card, and it is also the reason most people quietly stop using it after the first year.
Unlock The Benefits Of Pay Jcpenney Credit A Comprehensive Guide
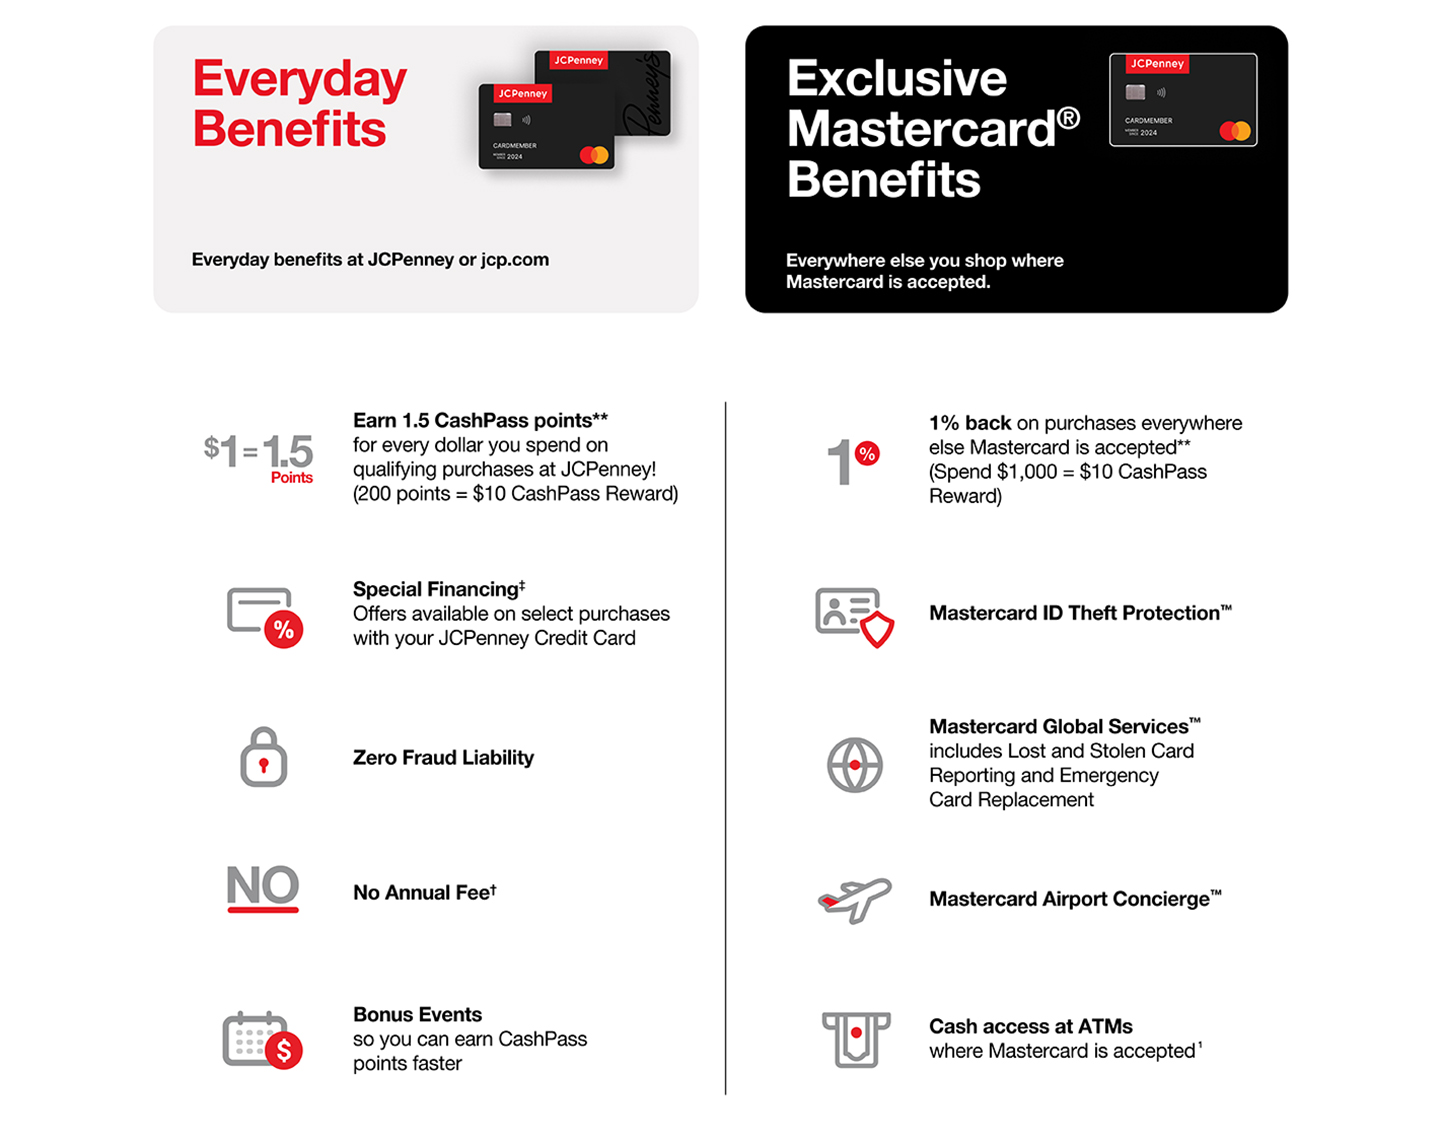
Since the card is from Synchrony, you manage everything online through the Synchrony Bank portal or their mobile app. You can make payments, check your balance, view statements, and set up autopay from there. There is no phone number for customer service that actually connects you to a human quickly — the automated system will ask you to pay online first, then offer you a callback if you insist. I found myself calling three times just to confirm a payment posted correctly, and on the third attempt, a real person told me payments typically post within one business day but sometimes take up to two depending on when you submit them. That detail matters when you are trying to avoid a late payment during a billing cycle transition. The rewards structure is simple enough: you earn 5 percent back in rewards certificates on every dollar spent at JCPenney with the card. That is not points. It is not cashback deposited into a bank account. It is a store certificate you can only use on future JCPenney purchases. The certificate usually arrives within a few days of posting to your account, and it has an expiration date printed right on it. I learned the hard way that these certificates do not carry over to the next calendar year, even if you forget to spend them. One January, I had about $47 in unused certificates that vanished after the company ran an end-of-year purge. The terms say they expire 12 months from issuance, but the actual enforcement window is tighter than most people expect. There is a second tier called the JCPenney Rewards program that used to give you additional percentages when you shopped with the card during promotional windows. These promotions rotate frequently — sometimes you get 10 percent back, sometimes 15 percent on specific categories like home goods or cosmetics. The promotions are not advertised clearly on your statement. You have to log into the rewards dashboard inside the Synchrony portal and manually opt in each time. I spent a full week tracking down why I wasn't earning the advertised bonus rates until I realized I had never clicked the enrollment button for the Spring 2024 promotion. The system does not auto-enroll you. It expects you to know about it, check your account regularly, and click the right button before your purchase posts.
The interest rate on this card is standard for store cards — around 25 to 30 percent variable APR. That is steep. If you carry a balance from month to month, the rewards you earn are completely wiped out by the interest charges within the first billing cycle. I calculated this once for a friend who had been carrying a $600 balance for six months. She had earned roughly $75 in rewards certificates over that period. The interest she paid totaled about $112. She was losing money on the card by staying with it. This is not theoretical. It is the math that plays out for anyone who does not pay in full every single month. One thing people miss about this card is the credit-building angle. Because Synchrony reports to all three major credit bureaus, using the card responsibly can actually help your score if you keep utilization low and pay on time. But here is the catch: the credit limit on these cards is usually very low — often between $200 and $500 for new holders. That means even a modest purchase of $150 puts you at 30 to 75 percent utilization, which tanking your score faster than you might expect. Utilization is the most heavily weighted factor in most scoring models, so maxing out a low-limit card is worse for your credit than having a higher-limit card with the same balance. There is also a nuance with statement credits and returns. If you buy something with the card, earn a rewards certificate, and then return the item, Synchrony will reverse the rewards certificate. This is standard practice, but the timing is annoying. The reversal often happens weeks after the return is processed, and the certificate may have already expired by the time they deduct it. I encountered this with a $30 home decor item I returned in March. The reward certificate for that purchase was still active in my account through April, and by the time Synchrony reversed it in early May, I had already used it on a different purchase. They ended up charging back $4.50 to my account anyway because the system could not track the certificate depletion accurately. This is an edge case, but it happens more often than the fine print admits.
Get the Full Details

Another practical detail: the JCPenney card does not have an annual fee. That is one of the few genuinely positive things about it. You lose nothing for keeping it open, assuming you do not carry a balance. If you only use it during big sales events — Black Friday, Memorial Day, July 4th — and you pay it off immediately, the card can be marginally useful. The 5 percent back plus any promotional boosts can add up during those windows. But if you are shopping at JCPenney regularly throughout the year, you are better off comparing it against a general-purpose rewards card that gives you cashback at any retailer. I would recommend keeping the card only if you have a clear plan to use it during promotional periods and pay it off in full every month. If you tend to carry balances, close it. The interest rate will eat any benefit you get from the rewards, and the low credit limit will hurt your score more than it helps. The card serves a very narrow purpose, and outside of that narrow purpose, it is just another account you have to manage for no real gain.