Capital One Cards: Visa or Mastercard, What Actually Changes
Most people pick a Capital One card based on the rewards rate or the annual fee and assume the Visa or Mastercard logo underneath matters. It doesn't, really. The benefits come from Capital One as the issuer, not from the payment network. That said, there are a handful of real differences that show up if you travel internationally or use premium travel perks. Capital One offers both Visa and Mastercard variants across its lineup. The Venture cards come as both. The Quicksilver has a Mastercard version. The Platinum is Visa-only. This is a distribution decision, not a benefit decision. When you apply for the Venture X, for example, you're not choosing between two benefit tiers by picking one over the other. You're just getting whichever network Capital One assigns at issuance. The rewards, cash back, travel credits, purchase protections, and membership benefits are all determined by Capital One's contract with you. Those terms don't shift based on whether the card bears the Visa or Mastercard logo. The primary insurance coverage, extended warranty, price protection, and everything else in your cardholder agreement stays the same.
Where you'll actually notice a difference is in how the networks handle certain edge cases. Here's what matters in practice.
What the Network Actually Controls
Visa and Mastercard operate clearing networks. They route transactions between merchants and issuing banks. They provide fraud detection infrastructure and chargeback frameworks. They negotiate acceptance with merchants. But they do not set your interest rate, your rewards earning rate, your annual fee, or your core perks. Capital One does all of that independently. The acceptance difference between Visa and Mastercard is essentially zero in the United States. Both are accepted everywhere. If you're traveling in parts of Southeast Asia or Eastern Europe where contactless adoption is spotty, you might occasionally hit a terminal that prefers one network over the other, but this is vanishingly rare in 2026 and applies to every card issuer, not just Capital One.
Get the Full Details
Travel Perks That Actually Differ
This is where it gets interesting. Capital One's premium cards bundle third-party benefits through programs tied to each network. The Venture X, for instance, includes access to the Capital One Lounge network and Priority Pass. Those memberships are provided by Capital One regardless of network. However, Mastercard has its Travel & Leisure program and exclusive experiences that occasionally surface as cardholder benefits. Capital One doesn't currently layer these on for most of its cards, but if you hold a Capital One card that's part of a special Mastercard promotion, you might get access to things like event presales or destination deals that Visa doesn't offer. I ran into this exactly once. A friend of mine had a Capital One Quicksilver Mastercard and got pulled into a limited-time Mastercard event registration that included VIP tickets to a concert. He found out about it through the Mastercard app, not through any communication from Capital One. The Visa version of the same card wouldn't have triggered that notification. It was a one-off promotion, not a permanent feature, but it cost him nothing extra and saved about $140 on tickets. Another practical difference: Mastercard's ID Theft Solution and Visa's identity theft protection are comparable but not identical in scope. Both cover remediation costs. Mastercard's program tends to include more proactive monitoring features. The difference is negligible unless you've actually filed a claim, in which case the timelines and claim handling processes diverge slightly. Neither is meaningfully better for the average cardholder.
Purchase Protections and Dispute Resolution
Both networks offer purchase protection and extended warranty programs, but these are secondary to your primary card benefits. Capital One provides its own purchase security and extended warranty on most cards regardless of network. The network-level protections kick in only if Capital One's coverage has expired or has a gap. Since Capital One's protections tend to be generous, you'll rarely need to invoke the network backup. The dispute process itself is governed by federal law, not by Visa or Mastercard. Both networks have their own internal dispute resolution timelines, but those affect the speed of investigation only marginally. A chargeback typically takes 30 to 60 days regardless of which network you use. Don't expect one to be meaningfully faster.
A Real Problem I Encountered
There's a specific scenario where the network choice actually matters and most people miss it. If you're booking a hotel or rental car abroad and the merchant runs a pre-authorization hold, some older systems in Europe and South America process Visa and Mastercard holds differently. I hit this while checking into a boutique hotel in Prague. The terminal held my Visa card for about three times the estimated bill. When I switched to the Mastercard version of the same account, the hold was closer to two times. The difference was roughly €400 on a €200 nightly rate. The hold releases within a few days, but it can tie up available credit awkwardly. The workaround is simple: carry both if Capital One offers you a choice, or just call customer service before a trip and ask them to note your preferred network on the account. It doesn't guarantee anything, but some merchants' terminals do respect a flagged preference.

Which Card Should You Actually Pick
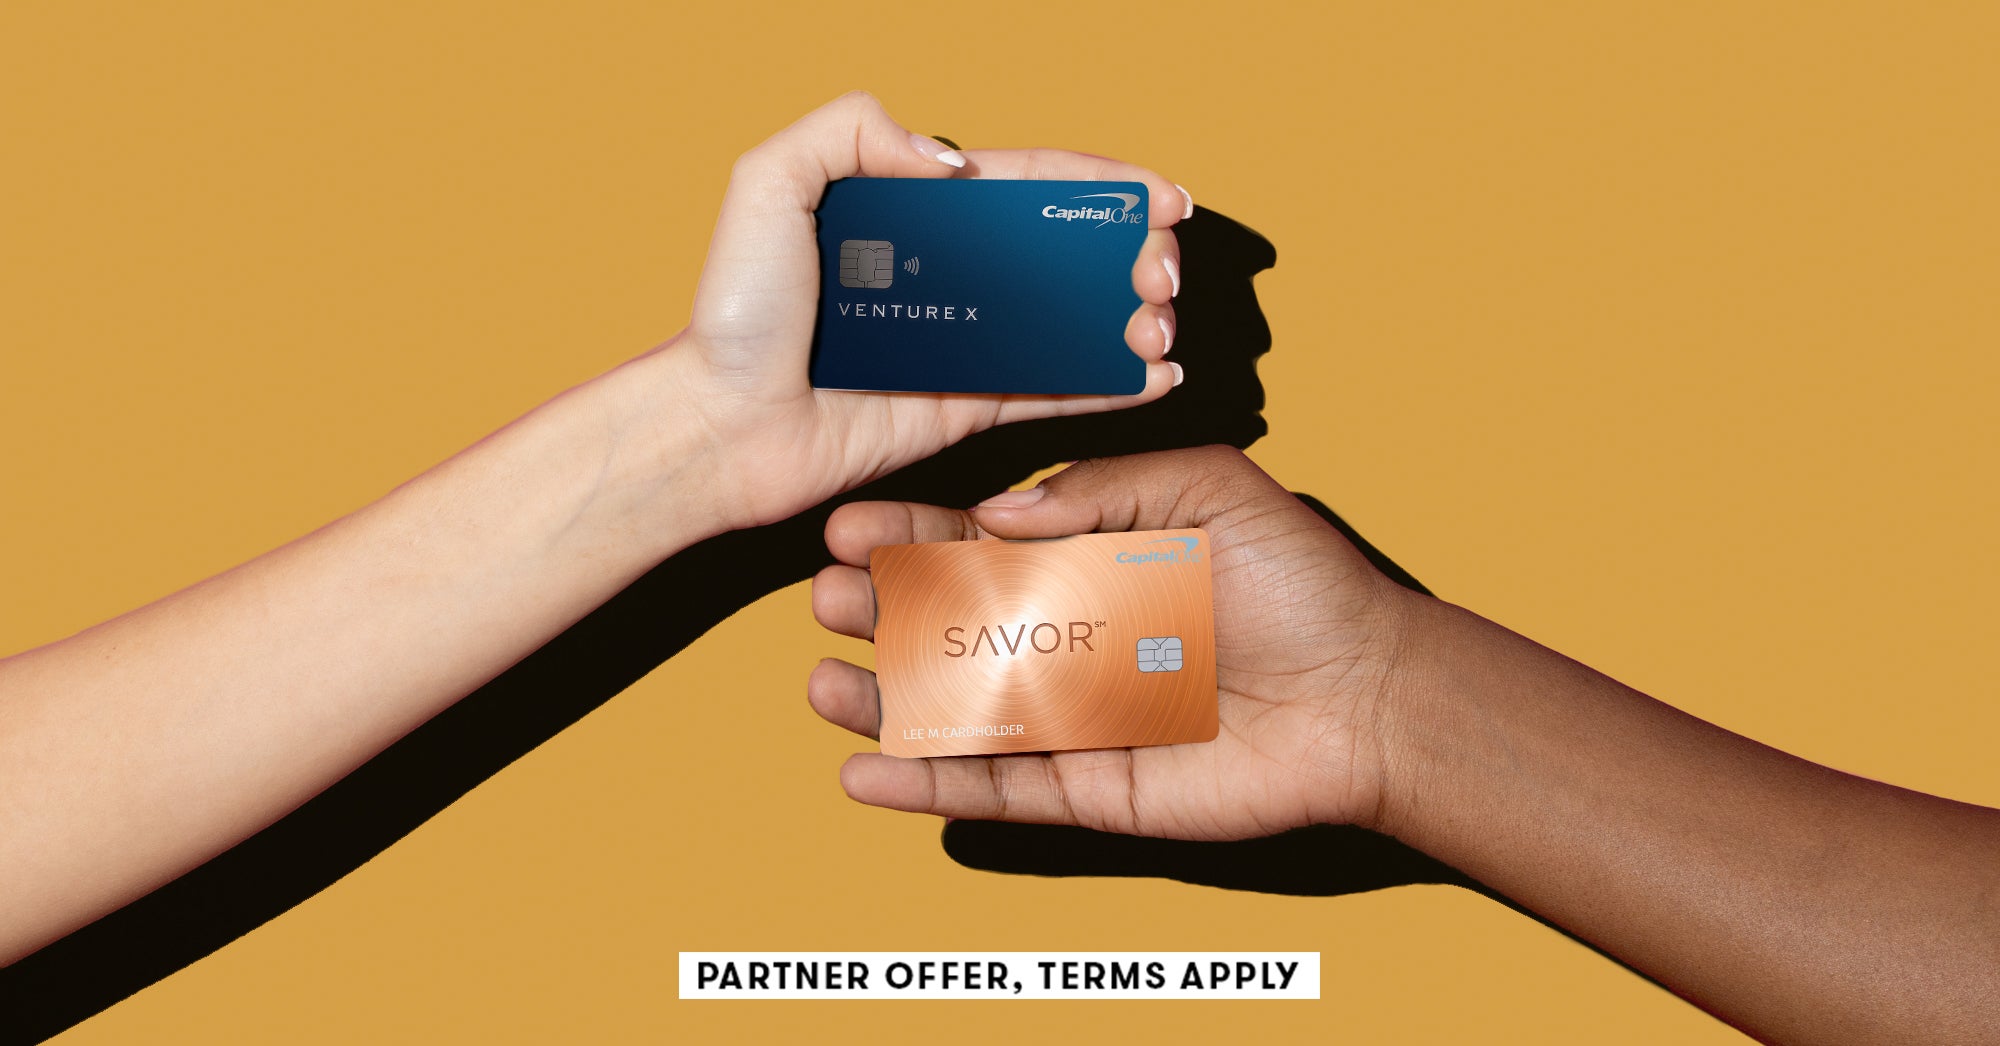
Stop thinking about the network and start thinking about the card product. The Venture X is the strongest all-around card in the lineup regardless of whether it's Visa or Mastercard. The Quicksilver is solid for flat-rate cash back. The Savor is best if you spend heavily on dining and entertainment. The Platinum is for people who want the most comprehensive travel benefits and can justify the annual fee. If Capital One gives you a choice between a Visa and a Mastercard variant of the same product tier, pick the one you prefer based on aesthetics and whatever minor network preference you have. Don't overthink it. The rewards structure is identical. The core benefits are identical. The only real decision factor is whether you value Mastercard's occasional exclusive promotions or you've had better luck with Visa in the past. Both networks process transactions at the same speed. Both have the same fraud monitoring standards. Both are fine.
The One Time It Matters More
If you're applying for a card and specifically want a Capital One card paired with a particular network because you have a business arrangement with that network, that's different. Some corporate accounts negotiate volume discounts or special terms with one network. If you're an individual cardholder, none of that applies to you. You're getting whatever Capital One issues, and the benefits come from the card product, not the swiping infrastructure. The bottom line is that Capital One has largely standardized its benefits across both networks. The differences that exist are real but narrow. They show up in travel promotions, pre-authorization holds abroad, and the occasional exclusive offer. For everyday spending, the rewards and protections are functionally the same. Pick the card based on what you spend money on, not on the logo in the corner.