Getting Into Your Truist Account Without Losing Your Mind
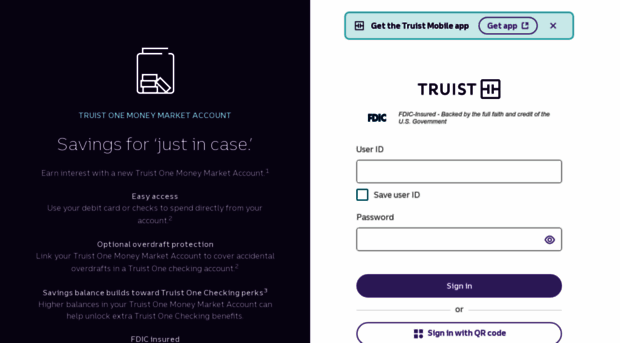
Logging into Truist used to be a headache that would have me calling support before my second cup of coffee. The process has settled down quite a bit since they merged BB&T and SunTrust, but there are still enough gotchas that writing this guide felt necessary. I have been using their online platform for about eight years now, through the merger, two major UI overhauls, and the occasional outage that leaves you wondering if your money actually exists. The core login flow is straightforward. You go to truist.com, click sign in, enter your username and password, and then deal with whatever multi-factor authentication method they decide to push on you that day. I use the text message code most of the time because it is faster than digging for my authenticator app, though I admit the authenticator is more secure. Their system has gotten better about recognizing my browser and device, which means I skip the extra verification step about 70 percent of the time after the initial setup.
Unlock Secure Access With Truist Bank Login A Comprehensive Guide
The real complications start when you try to do anything beyond checking your balance. The Truist portal is not particularly intuitive about letting you set up bill pay for a new vendor, initiate a wire transfer, or update your beneficiary information without jumping through several hoops. I learned this the hard way during a move when I needed to update my address on a mortgage account. The online form kept failing at the identity verification step because my old address was still on file from the SunTrust days and the new one was only on my driver's license for three months. The workaround was to call them, but here is the counter-intuitive part: calling them during business hours meant a forty-five minute hold. I found out that requesting a callback through the chat function at 11:47 PM on a Tuesday resulted in a call at 6:15 AM with a wait time of about four minutes. Nobody seems to advertise this option well. The chat bot will try to solve everything with scripted responses until you type "agent" or "representative" repeatedly, and then it eventually offers the callback request. Use it. Another thing that trips people up is the mobile app versus the desktop site. They do not always stay perfectly in sync. I had a situation where I approved a credit card transaction on the app, but the fraud department had already flagged it on their end based on the desktop alert system. The app showed the transaction as cleared, but the desktop showed it as under review. It turned out the fraud team processes desktop alerts with higher priority than in-app notifications. If you want to see the real status of any flagged activity, check the desktop version. The app is fine for routine banking, but it is not the authoritative source.
Password resets are another area where the process is unnecessarily painful. They send a code to your registered email, but if you do not check that email regularly, the code expires in fifteen minutes. I set up a dedicated email folder for Truist communications and a filter that highlights them in orange, which sounds extreme until you have tried to reset your password while sitting in a bank branch with a teller waiting for you to hand over your account number. Here is something they do not tell you about the mobile check deposit feature. The limit is listed as $25,000 per day, but that is actually split between two windows. There is a per-deposit limit and a per-day aggregate limit, and they interact in ways that are not clearly explained. I once deposited two checks totaling $20,000 in a single morning, and one of them was put on hold for five business days even though it was under the individual deposit limit. The issue was that the second deposit pushed me past a secondary threshold that only triggers when multiple deposits occur within the same calendar day. If you are doing large deposits, space them across different days to avoid the hold trap. The two-step verification setup is also worth getting right from the beginning. You can use the Truist Secure ID app, text messages, or email, and each method has different reliability. The app is the most dependable because it does not depend on cellular coverage or email delivery times. I switched from SMS to the app after a weekend where my phone was in the shop and I could not access any codes. The app generated codes fine from my laptop while I waited for the repair. It took about ten minutes to set up and saved me from a potentially disastrous situation.
Get the Full Details

One more thing that deserves mention is the automatic logout behavior. Truist logs you out after twenty minutes of inactivity, which is reasonable security practice. But if you are filling out a lengthy form and the tab expires, you lose everything. I learned to copy and paste my information into a notepad document before starting any multi-step process. It adds a step, but it prevents the frustration of restarting a thirty-minute form because you went to check an email notification and the session died. The Truist platform works well once you understand its quirks. The merge created some legacy confusion that still shows up in edge cases, but the core functionality is solid. Customer service is accessible if you know how to bypass the automated phone tree. The mobile app handles most everyday needs without issues. And the security measures, while occasionally inconvenient, are generally appropriate for a bank of this size. I will not claim this guide covers every possible scenario. Banking systems are large and constantly updated. But the points about callback scheduling, desktop versus app discrepancy, deposit hold thresholds, and session management should save you some time. These are the things that matter most when you actually need to get something done quickly.