Managing Your Lane Bryant Credit Card Payments
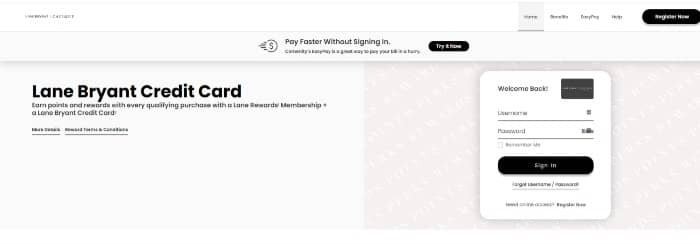
The Lane Bryant credit card is issued by Comenity Bank, which means everything you do online goes through their portal, not a generic store system. I've spent years helping people navigate these retail credit accounts, and the lanebryant.com login page is one of the smoother ones I've seen. Still, there are enough quirks that people get stuck regularly. To log in, go to lanebryant.com and click Sign In at the top right corner. You'll see options for your Lane Bryant account and your credit card account. Pick the credit card one. If you already have an online profile set up, enter your username and password. First-time users need to register with their card number, which you can find on the front of the physical card or on your monthly statement.
Unlock Seamless Payments Everything You Need To Know About Lanebryant Credit Card Log In And Payment Management
Once you're logged into the Comenity Bank portal, the dashboard gives you a few key things: your current balance, minimum payment due, payment due date, and available credit. There's also a transaction history section that can be useful but doesn't always update in real time. Transactions from the store might show up the next business day, sometimes two days out during peak seasons like back-to-school or holidays. The payment management side is straightforward enough. You can set up automatic payments through a linked checking or savings account, make one-time payments from that same source, or pay by check if you mail it in. The automatic payment feature has a couple of settings you should know about. You can choose to pay the full statement balance or just the minimum due. Most people who carry a balance month to month pick minimum payments and end up paying significantly more over time because of the interest. The APR on the Lane Bryant card runs high compared to most general-use credit cards, so carrying a balance is expensive. I had a situation last year where someone called me frustrated because their payment showed up as late even though they submitted it three days before the due date. The issue was that they selected the minimum payment option in their auto-pay settings instead of the full balance, and the remaining amount was treated as a past-due balance. Once we changed the auto-pay setting to full statement balance and manually covered the leftover, the late notice stopped. That's something worth checking if you ever get a surprise late fee.
Another thing that trips people up is the phone number registration. When you create your online account, you have to verify your identity, and Comenity Bank sometimes asks for the phone number on file with them. If you moved recently or used a different number when you first applied, that verification step can fail. I've worked through this with several people by calling customer service to update the phone number before attempting online registration again. It takes about ten minutes on the phone and saves a lot of headaches. Here's what I'd suggest doing each month:
Get the Full Details
- Log in around the same week your statement closes so you know exactly what you owe.
- Check your transaction history for any charges you don't recognize. Disputes are easier to handle within sixty days of the charge appearing.
- Verify that your auto-pay is set correctly, especially after any life changes like moving or switching banks.
- Review your available credit. If you're near your limit, consider making a mid-cycle payment to lower your utilization ratio before the statement closes.
The mobile app for Comenity Bank is available on iOS and Android. It handles most of the same functions as the website. I prefer using the app for quick balance checks but the website for anything involving payment setup or dispute filing. The app's interface changes occasionally, and some features move around without much notice. One counter-intuitive thing about retail credit cards like this one: they often report your payment history to all three major credit bureaus, but they tend to be less forgiving of late payments than a standard bank-issued card. A single late payment on a Comenity account can drop your credit score by more points than a similar late payment on a Chase or Capital One card. The reason comes down to how retail cards are categorized in credit scoring models. They're treated as higher risk, so delinquencies weigh heavier. Paying on time consistently matters more here than it might on a regular credit card. There are limitations you should be aware of. Comenity Bank's online system doesn't support third-party payment apps like Zelle or PayPal. You're stuck with their portal, a bank transfer, or mailing a check. If you're trying to consolidate all your payments through a single app, this one won't fit that workflow. Also, the statement dispute process is entirely manual. You can't file a dispute and track it in real time the way you might with a major bank. You submit the dispute form online or by phone and wait. Expect a response within thirty to forty-five business days.
If you find yourself dealing with this card frequently, the most practical thing you can do is set a calendar reminder for your payment due date. Not the statement closing date, the actual due date. I've seen too many people miss it because they assumed the due date was the same as the statement date. They're almost never the same. The gap between statement closing and payment due is usually twenty-one to twenty-five days, but it varies by account. You can call Comenity Bank customer service at the number listed on the back of your card if you run into issues that the website doesn't resolve. Wait times vary, but calling mid-week during morning hours tends to be faster than weekends. Have your account number and a valid ID ready before you call. It cuts the verification step from several minutes down to under a minute. For most people, keeping track of this card comes down to logging in once a month, confirming the balance, setting up or verifying auto-pay, and scanning for unfamiliar charges. That's it. It's not complex, but the details matter if you want to avoid fees and keep your credit in decent shape.