Pep Boys Credit Card: What Actually Happens When You Use It
The Pep Boys credit card is a store-branded revolving account. It works like most retail cards you will find at auto parts and service chains. You get a credit limit, you make purchases, and you pay a monthly minimum. The card only works at Pep Boys locations and their website, which immediately narrows its usefulness compared to a Visa or Mastercard. Most people apply on a Tuesday afternoon because they just needed a set of brakes done and wanted to split the cost. It takes about three minutes to get a decision. If you have decent credit, you are usually approved instantly. If your score is lower, you might get a reduced limit or a second-chance product with higher rates. There are two distinct paths when you use this card, and confusing them is the #1 reason people end up paying extra interest they did not expect. The standard purchase path: You charge regular items like oil, filters, wiper blades, or routine brake service. The card carries a variable APR that typically runs between 26.99% and 29.99%. This is standard for store cards. You carry a balance month to month and pay interest on the remaining amount. No promotions apply here unless a sale is running.
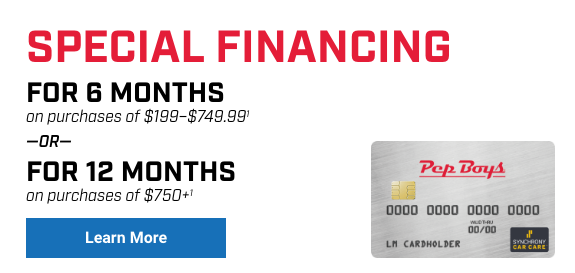
The promotional financing path: Pep Boys periodically offers deferred interest deals on larger purchases. Common terms are 6 months, 12 months, or 24 months no interest if paid in full by the end of the promotional period. The catch is deferred interest, not zero interest. If you do not pay the entire balance before the promotion expires, interest is backdated to the original purchase date at a higher rate, sometimes 29.99% or more. This is the detail almost nobody reads carefully. I learned this the hard way a few years ago. I put a complete suspension repair on the card under a 12-month promo deal. I was confident I would clear it. Life happened, a paycheck got delayed, and I paid off the remaining $412 on day 137 of the promotion. I thought I owed interest for 137 days. I did not. Pep Boys charged retroactive interest on the full original purchase price of $2,180 for the entire 12-month period. The additional charge was $783. That surprised me more than anything else in my personal finance experience. The workaround was straightforward once I understood it: set a calendar reminder for 28 days before the promo end date, and pay the balance two weeks early to avoid any mail-processing delays or system holdups. Never wait until the final day. Another benefit that actually matters is the cardholder discount structure. Pep Boys offers card members a 10% discount on many in-store parts purchases during promotional windows. This is not automatic on every transaction. You have to look for the offer. Some service labor charges are excluded. The discount applies to items like motor oil, air filters, and battery sales more often than it applies to specialized components or imported car parts.
Free tire installation and rotation promotions come up frequently for card members. These are legitimate perks if you buy tires from Pep Boys. The fine print limits them to standard installations. If you need specialty mounting or balancing for run-flat tires or certain performance wheels, those fees may not be covered. Always ask before the work starts. The application process happens online or in-store. You will need a Social Security number, proof of income, and your address. The instant decision pulls a hard credit inquiry, which drops your score by a few points temporarily. If you are shopping around for the card while also applying for an auto loan or mortgage, space them apart by at least 30 days. Multiple hard inquiries in a short window add up and lenders notice. Here is something most guides skip: the deferred interest promo is not always the best deal even when it looks attractive. Run the numbers against a 0% APR credit card from a major issuer. A 24-month promo at Pep Boys with deferred interest is risky. A 0% APR card from Capital One or Discover usually has no retroactive trap and the same payment schedule. The Pep Boys card makes sense when you are already buying from them regularly and want the discount layer on top. It does not make sense if you are only using it for one big repair and planning to carry a balance.
Get the Full Details
Credit tier expectations matter more than most people realize. Pep Boys typically targets applicants with fair to good credit, roughly a 640 to 720 FICO range. If you fall below that, you may receive a secured version or a prepaid card instead of a traditional revolving account. The secured option still gives you the promotional financing access, but your credit limit is tied to your deposit amount. That is not a failure. It is just the actual product you get, and it works the same way otherwise. Monthly statements arrive by email unless you opt for paper. Checking your statement every month is not optional if you are on a promo. You need to see exactly how much remains and whether your payment posted on time. Missing a single payment resets the promotion clock and voids any deferred interest benefit. Late fees kick in after 15 days past due, and the card may be frozen until the balance is brought current. The mobile app handles payments, balance checks, and promotional tracking. It is basic but functional. I recommend downloading it immediately after approval so you can set up autopay for the minimum amount at minimum. Autopay prevents accidental late payments and keeps the account in good standing even when you forget. You can still pay extra manually to accelerate payoff, which is important during a promo period.
Customer service calls run through a dedicated line for Pep Boys cardholders. Wait times vary but peak on Monday mornings and right after a billing cycle closes. The best time to call is mid-afternoon on a Wednesday. Bring your account number and a written summary of the issue. Agents have more context and can resolve things faster when you present the facts clearly instead of going in circular. If you are on the fence about applying, ask yourself two questions first. Do you buy from Pep Boys more than twice a year? Are you disciplined enough to track promo end dates and pay off balances early? If the answer to either is no, a general-purpose rewards card with low APR and transparent terms is the better move. The Pep Boys card is a tactical tool, not a primary credit product. It has a specific use case, and it works well within that lane. One more thing worth noting: some Pep Boys locations participate differently in the cardholder discount program. A corporate-owned store and a franchised location may run separate promotions or exclude different services. The discount that appears on the website does not always match what your local shop applies at the register. Call ahead and confirm which promo is active for your visit before you schedule the service. It saves an argument at checkout and prevents the frustration of expecting a discount that never showed up.
The card itself has no annual fee. That is straightforward and honest. Rewards do not come in points or cash back in the traditional sense. The value comes from discounts and financing terms. You are not building a rewards balance. You are accessing conditional savings. That distinction matters when you decide whether the card earns its place in your wallet.