Managing Your Amazon Credit Card Without Losing Your Mind
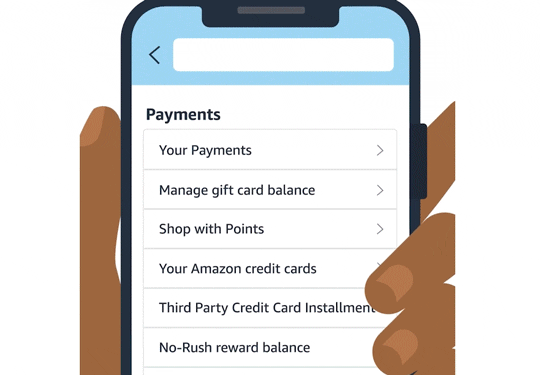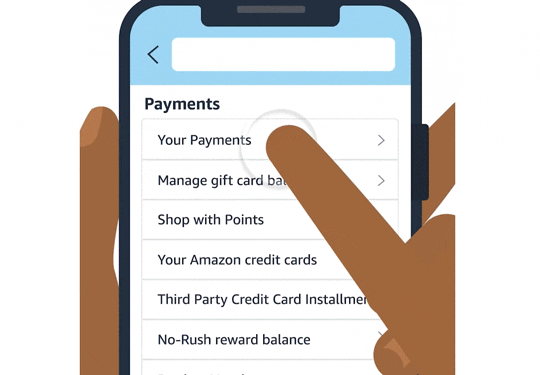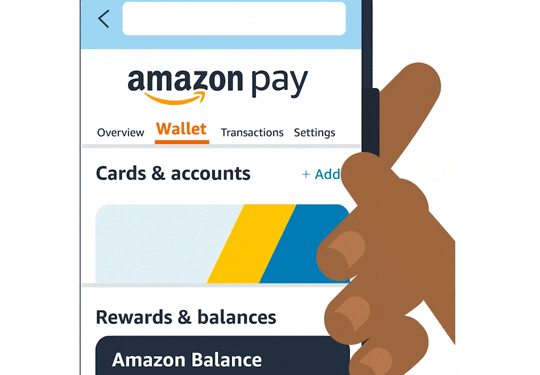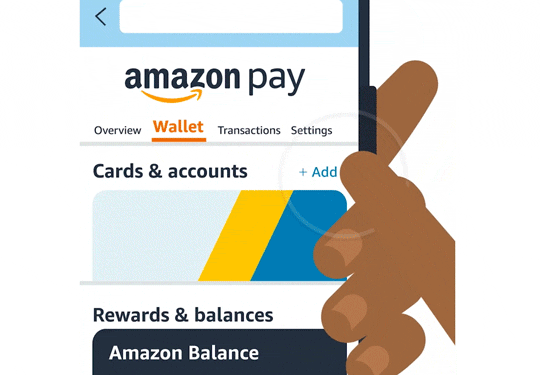
The Amazon Store Card is one of those retail credit cards that feels straightforward until you're actually sitting there at checkout or staring at your monthly statement. You get 5% back on Amazon purchases, which sounds great, but the devil lives in the details of how you pay it, when you pay it, and what happens if you miss a beat. Paying your Amazon card is done through the Amazon website or the Alexa app. You log in, go to your account settings, navigate to the payment options for your store card, and set up a recurring payment or make a one-time payment. The system pulls from whatever bank account or card you link. That's the basic mechanics. Nobody needs a tutorial for that part. What people don't think about is the timing. If you have auto-pay turned on with the minimum due, you're going to carry a balance. Carrying a balance on the Amazon card means interest rates that can push into the 20 to 29 percent range depending on your credit profile. I learned this the hard way back in 2019 when I had auto-pay set to minimum and basically forgot about the card for three months. When I finally looked at the statement, I owed about $840 including over $200 in accumulated interest. The trick is setting up full balance autopay, not minimum. It took me about 30 seconds to change in the portal.
There's another angle people miss entirely. The 5% discount isn't always as valuable as it looks. When Amazon runs promotions where they effectively give you discount points or bundle deals, paying with the card on top of those promotions can stack in weird ways. I remember buying a ring light and doorbell camera combo during a promotional window. The bundle already had a built-in discount, and then the card cashback hit on top. It saved me roughly $35 on a $120 purchase. That's real money, but only if you pay the card off in full before the statement closes. The statement closing date matters more than the due date. Most people watch the due date and forget about when their billing cycle actually resets. If you make a large purchase five days before the statement closes, it shows up on that statement and you owe it within 21 to 25 days. If you make the same purchase five days after the statement closes, you essentially get a 50-day interest-free window. I structure all my big Amazon buys around this calendar now. It costs nothing and it's genuinely useful if you ever need a short cash flow buffer. Here's the problem nobody warns you about. Once you start using the Amazon card regularly, Amazon's algorithm notices. Your offers, your prices, and your recommendations shift. I noticed my Prime pricing disappeared from certain categories after I started charging larger purchases to the store card. The discount wasn't gone, but it stopped appearing as prominently. I suspect this is some kind of behavioral pricing thing, but I never got a straight answer from customer service. Worth mentioning because you shouldn't assume your cart prices stay static no matter how you pay.
If you're the type who forgets things, set up two reminders. One for the statement closing date and one for the due date. Your phone calendar works fine. You don't need a fancy budgeting app for this. The whole process of managing this card should take you maybe two minutes a month if you're organized. Anyone spending more time than that is overcomplicating it. The biggest pitfall with the Amazon card is treating it like a general-purpose rewards card. It isn't. It only gives you the 5% on Amazon purchases, and sometimes on Whole Foods depending on the specific card product you hold. The Cash Back Revolution Card from American Express or a basic no-annual-fee Visa from Chase usually outperforms it for everyday spending outside Amazon. Use the Amazon card only for Amazon. Everything else goes on a different card. I've been doing this for years and it keeps my rewards tracking simple enough that I don't need to think about it at all. If you're carrying a balance right now and the interest is eating you alive, stop using the card immediately and call the number on the back of your card. Ask for a hardship adjustment or a rate reduction. It's worth a try. I've had two different people lower my rate by a few percentage points just by asking politely. They'd rather keep you as a customer than let you max out and default. There's no script that guarantees success, but it's faster than trying to figure out a debt snowball on your own.
Get the Full Details