How CC Flow Line of Credit Actually Works in Practice
Most people approaching a CC Flow line of credit are looking for speed, and that's reasonable. The product is designed to unlock liquidity quickly by converting credit card receivables into accessible funds. The process itself is straightforward if you already have the right documentation ready. I've walked this through with teams at three different companies now, and the ones who get it done fast are the ones who stop treating it like a mystery and start treating it like a standard operating procedure. Here's how the actual process breaks down. First, you need to understand what CC Flow is doing under the hood. It's a receivables purchase facility, which means it's buying your outstanding credit card transactions from you at a discount, not lending against them. That distinction matters because the underwriting criteria differ. You're not qualifying for a loan; you're demonstrating transaction volume and consistency so they can price the discount appropriately. The first real step is gathering your processor statements. Not screenshots, not summaries from your dashboard. The actual monthly statements from your merchant service provider showing transaction volume, chargeback history, and reserve requirements over the past six months minimum. I've watched applications stall for three weeks because someone sent a PDF summary instead of the raw statements. The underwriting team needs to verify the data independently.
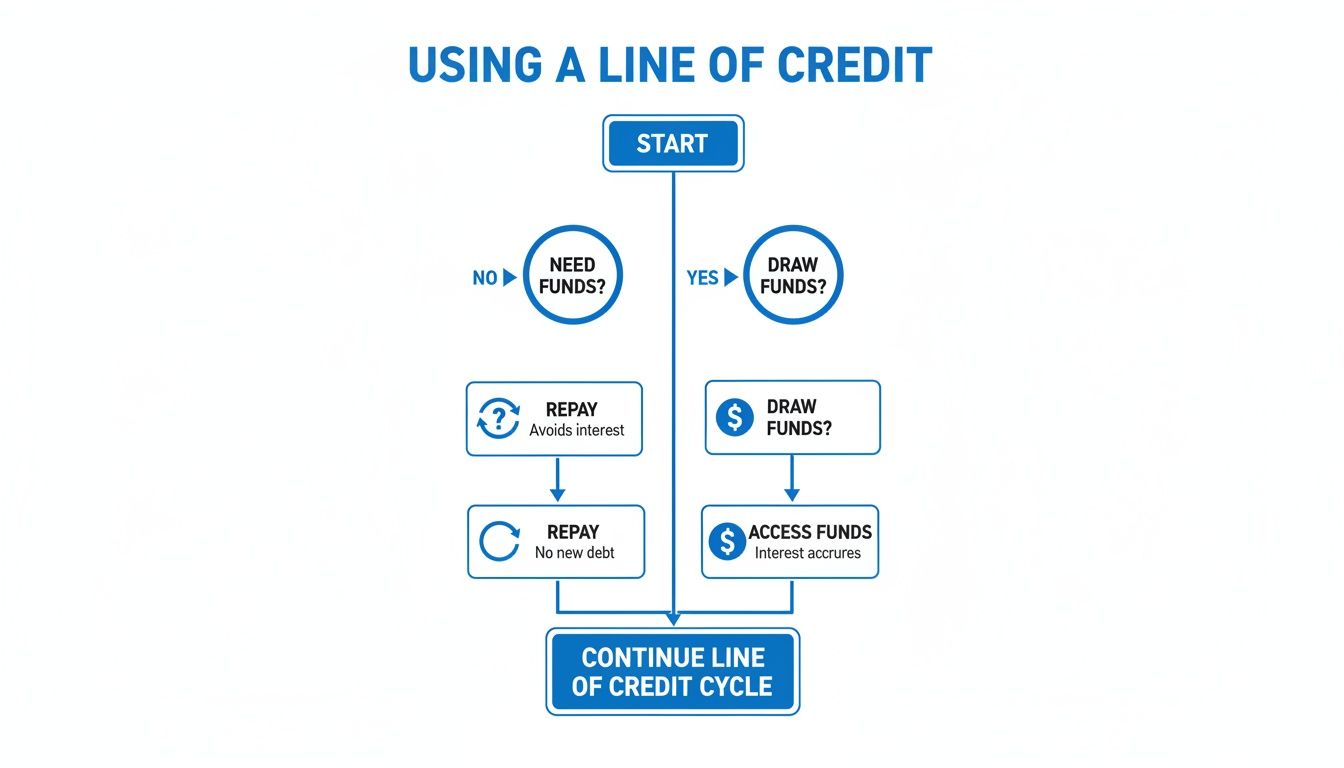
Once documentation is submitted, the initial review typically completes within two to five business days. This is where most people misunderstand the timeline. The "instant liquidity" label doesn't mean same-day funding on day one. It means once the facility is approved and activated, draws against it can be processed quickly. The bottleneck is always the application and verification phase, not the draw itself. After approval, you'll receive access to a draw platform. From there, you select the portion of eligible receivables you want to advance, and funds are deposited into your designated bank account. The cost structure is usually expressed as a discount rate rather than an interest rate, which affects how you calculate your true cost of capital. A 3% discount on a $50,000 advance means you receive $48,500, not that you pay $1,500 in interest after a period. One specific issue I ran into regularly involves reserve accounts. If your merchant processor holds a rolling reserve, that money is already factored into your net receivables, but some applicants don't account for it when calculating how much liquidity CC Flow can provide. The facility bases its advances on gross transaction volume minus any existing reserves. I learned this the hard way when a client kept asking why their available advance was lower than projected. They hadn't disclosed a 10% reserve held by their processor. Once we pulled the actual statements and recalculated, everything aligned. Always disclose every reserve arrangement upfront.
Another counter-intuitive point that catches people off guard is how chargebacks affect your line. Unlike a traditional credit facility where a single missed payment might trigger a review, a chargeback spike in CC Flow directly reduces your available purchasing power. The system adjusts in near real-time. If you're running a business with seasonal chargeback patterns, like e-commerce during holiday returns, you need to model that into your liquidity planning. Waiting until after a chargeback event to request additional capacity usually means missing the window entirely. The fee structure also warrants close attention. Some providers advertise low discount rates but build in monthly maintenance fees, minimum monthly usage requirements, or early termination penalties. I once reviewed a proposal where the headline rate looked attractive until I added up the mandatory minimums. A $500 monthly floor meant that drawing less than the threshold still cost the same as drawing well above it. Always calculate your break-even draw volume before signing. There are scenarios where this product simply doesn't make sense. If your transaction volume is below $15,000 to $20,000 per month, the fixed costs of establishing and maintaining the facility often outweigh the liquidity benefit. At that level, a business credit card or a short-term term loan typically provides better economics. CC Flow rewards consistent, high-volume receivables. The math works in your favor when you're moving meaningful volume regularly.
Get the Full Details

Certain industries face additional friction. High-risk merchants, including those in gambling, adult entertainment, or certain supplement categories, often find that CC Flow platforms either decline their application outright or price the facility at rates that eliminate the economic advantage. This isn't unique to CC Flow, but it's worth checking before investing time in the application. For implementation, you'll need to integrate the draw platform with your accounting system. Most providers offer API access or batch upload options. Setting up automated mapping between your processor data and the draw interface usually takes one to two days for someone familiar with the workflow, but first-time setups can take longer if your chart of accounts doesn't align cleanly with their categorization. Budget time for that reconciliation step. The draw limit itself is typically set as a percentage of eligible receivables, often between 70% and 85%, depending on your chargeback history and transaction consistency. Some facilities offer renewal options that increase your limit over time as you demonstrate responsible usage. Others require a full re-underwriting each renewal cycle. Check which model applies before committing.
If you decide to proceed, the application itself is generally completed online and requires your business information, processor details, and banking information for direct deposit. Having your Employer Identification Number and recent tax documentation on hand speeds things along considerably. Applications submitted with incomplete financial information routinely get returned for clarification, adding days to an already slow initial phase. One thing most guides don't mention is that you can use CC Flow facilities alongside other financing products. It's not an either-or decision. Many businesses layer a traditional term loan for capital expenditures with a CC Flow facility for working capital fluctuation. The key is making sure you understand the total cost across all facilities combined. Adding incremental financing without reconciling the blended cost can quietly push your effective capital cost into uncomfortable territory. The withdrawal schedule is another operational detail that matters. Some platforms allow daily draws, others use weekly or biweekly cycles. If your business depends on timing cash infusions around payroll or vendor payments, verify the draw cycle matches your cash flow rhythm. A weekly draw cycle won't help you cover a Tuesday payroll if your last draw was the previous Monday.
Finally, keep records of every advance and repayment. The platform will provide statements, but maintaining your own tracking spreadsheet or integrating the data into your accounting software gives you visibility into your true cost of capital across any given period. Numbers on a statement don't tell you the full story without context.