How PNC's High Yield Savings Actually Works
PNC Bank offers a high yield savings account that pays competitive rates for a traditional brick-and-mortar bank. The current APY floats with the federal funds rate, so when the Fed cuts rates, your earnings drop with them. That is the basic reality most people miss when they first open one. The straightforward path to maximizing what you earn with PNC's offering involves understanding the rate structure and your deposit habits. PNC does not pay tiered rates the way some online-only banks do. Your entire balance earns the same APY at any given time. That makes it simpler but also means you cannot stage your money across tiers to chase different rates. I opened a PNC high yield savings account in early 2024 when the APY was sitting around 4.25 percent. By mid-2024, after two rate cuts, it had dropped to roughly 3.50 percent. The difference mattered on a six-figure balance. I was losing about $1,200 a year in potential earnings compared to what I had locked in six months earlier. That is when I started looking at the actual mechanics more closely instead of just watching the rate slide.
One thing PNC does allow is their One Money Market Sweep. When you link a money market account, excess funds can sweep automatically into a higher-yielding vehicle within the PNC ecosystem. It is not the highest rate available nationally, but it keeps your money inside one institution, which matters if you value simplicity over squeezing out another ten basis points. Another overlooked detail is the statement savings option. PNC sometimes offers promotional rates on statement savings accounts that are slightly higher than the standard high yield product. These promos are not advertised on the main page and tend to last anywhere from 30 to 90 days. I found one by accident while reviewing my account dashboard during a routine check. The rate was 0.30 percent higher than the high yield savings rate at the time. I moved funds over immediately and set a calendar reminder for when the promo window closed.
The Real Constraints You Need to Know
PNC's high yield savings account is subject to the standard six-withdrawal limitation per month under Regulation D, even though the Fed suspended the enforcement of that rule in 2020. Banks can still impose their own limits, and PNC has been known to monitor transaction activity closely. If you hit the limit, they will typically notify you and may charge a fee or close the account entirely. I learned this the hard way after scheduling three automatic transfers out and two bill payments through the account in a single cycle. The system flagged it as excessive activity. It took about two weeks of back-and-forth with customer service to get the fees reversed and the account re-flagged as compliant. After that, I switched to using a separate checking account for all outgoing transfers and kept the savings account strictly for deposits and occasional intentional withdrawals. There is also noCD certificate alternative that often beats the savings rate. If you have a lump sum you do not need liquid for six to twelve months, a no-penalty certificate of deposit from PNC will usually pay 0.50 to 1.00 percent more than the high yield savings account. The tradeoff is that you lock the money in, but you can withdraw it once without a penalty during the CD term. For money you want truly accessible, the savings account still makes sense. For money you know you will not touch, the CD is the better move.
Get the Full Details

What the Numbers Actually Look Like
Let me give you a concrete example. Say you have $50,000 in the PNC high yield savings account at a 3.50 percent APY. Over one year, that earns you roughly $1,750 before taxes. If you moved the same amount into a 12-month no-penalty CD at 4.25 percent, you would earn about $2,125. The difference is $375. On a smaller balance, say $10,000, the gap shrinks to about $75. It is still real, but it changes how you think about whether the extra step is worth it. Interest compounds daily and pays monthly in both products. That means you are not waiting until the end of the term to benefit from compounding. If you leave the interest in the account, it starts earning its own interest right away. I recommend turning on auto-compound so you do not have to think about it.
Practical Steps to Get Started
You can open a PNC high yield savings account online or at any branch. You will need your Social Security number, a valid photo ID, and an existing bank account for funding. The minimum opening deposit is typically $0, which is unusual for a traditional bank and makes it easy to start with whatever you have available. Once the account is open, link it to your primary checking account for automated transfers. I set up a weekly transfer of $500 from my checking into the savings account. That approach removes the temptation to spend the money and builds your balance consistently without requiring constant attention. The PNC mobile app shows your projected interest earnings in real time, which is useful for tracking whether you are on pace to meet your savings goals. If you want to explore the promo statement savings route, check the account dashboard every quarter. Set a reminder on the first Monday of January, April, July, and October. These promos do not last long, and they tend to pop up between rate cycles when the bank is trying to retain deposits.
When PNC Is Not the Right Choice
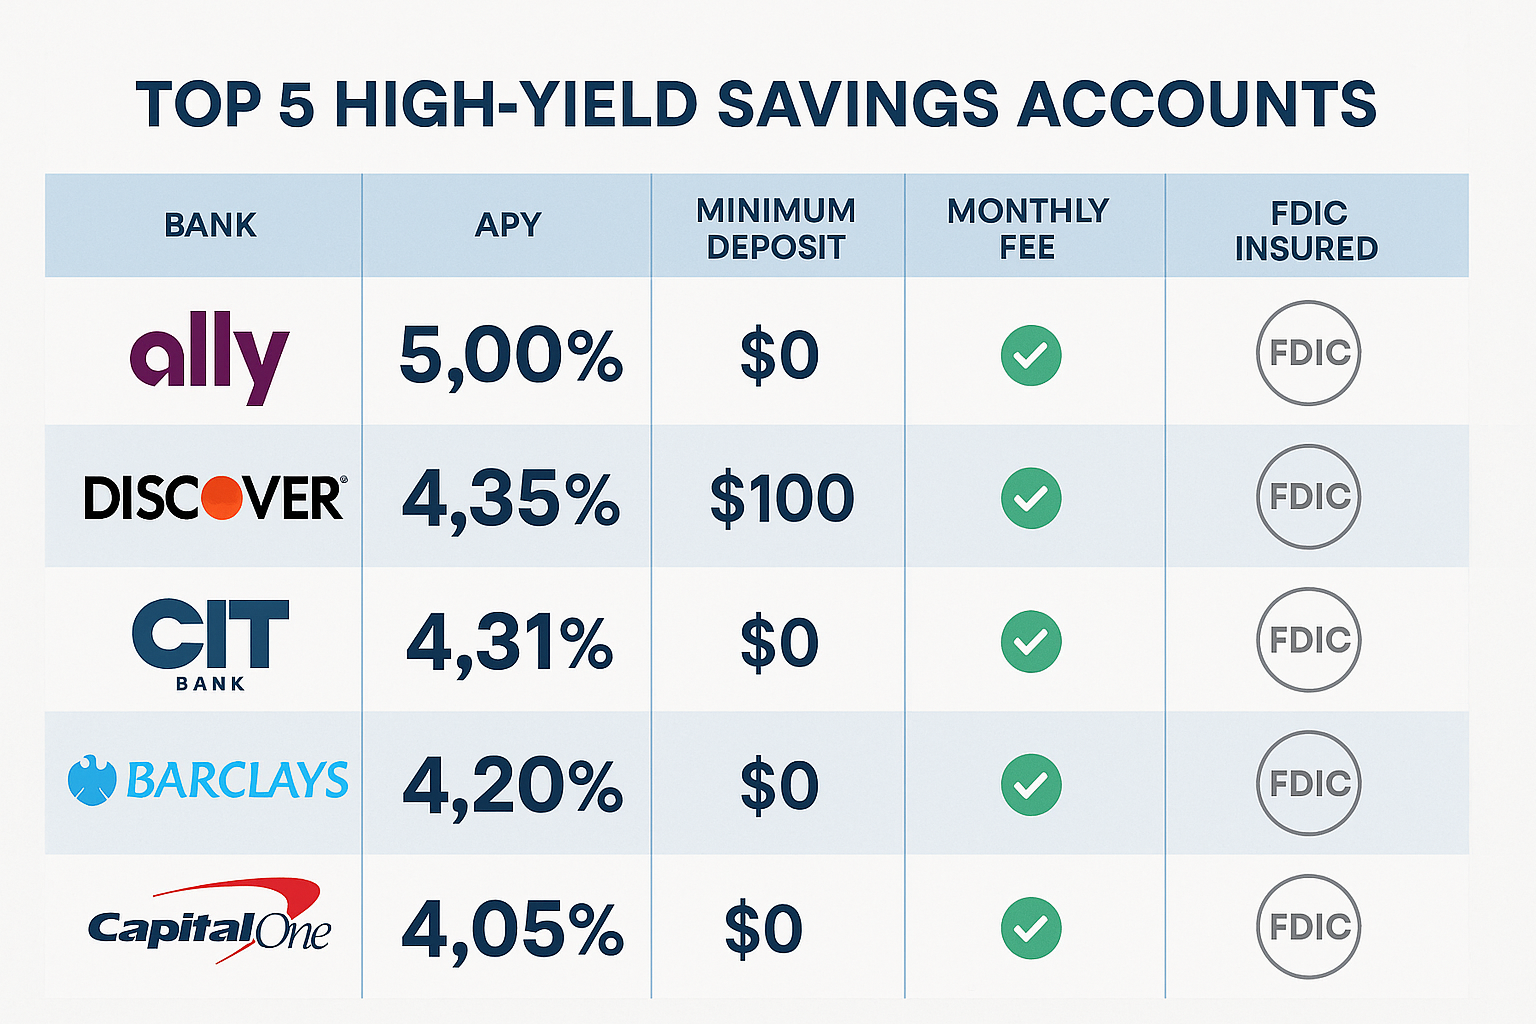
Online banks like Ally, Marcus, and Discover consistently offer rates that are 0.50 to 1.50 percent higher than PNC's high yield savings product. If your sole priority is maximum yield and you do not need a physical branch, those accounts are the better option. PNC's strength is convenience and integration with your existing banking relationship. You are paying a slight yield premium for that convenience. Whether that premium is worth it depends on how often you actually use branches and whether having everything under one roof saves you time. For most people, I would suggest opening the PNC account if you already bank there, filling it with an emergency fund or short-term savings goal, and then redirecting any additional savings to a higher-yielding online account. You do not have to choose one or the other. Keeping a portion at PNC for ease of access and the rest elsewhere for yield is a common and effective strategy. The account can be funded through direct deposit, wire transfer, or internal transfer from another PNC account. External transfers from other banks typically take one to three business days to clear. If you need the money quickly, use a direct transfer instead of a check deposit. Check deposits at PNC are held longer than electronic transfers, and holding periods can eat into your available balance when timing matters.

PNC does not charge a monthly maintenance fee on the high yield savings account. That is one advantage over some of their other product lines. The only fees to watch for are the excessive withdrawal fee, which runs around $10 per occurrence, and out-of-network ATM fees if you use their network incorrectly. Both are avoidable with basic discipline.