The Zillow Affordability Calculator Isn't As Simple As It Looks
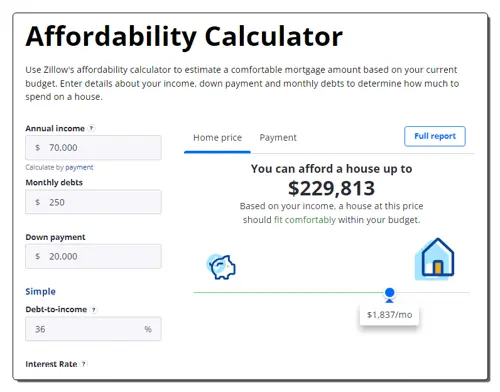
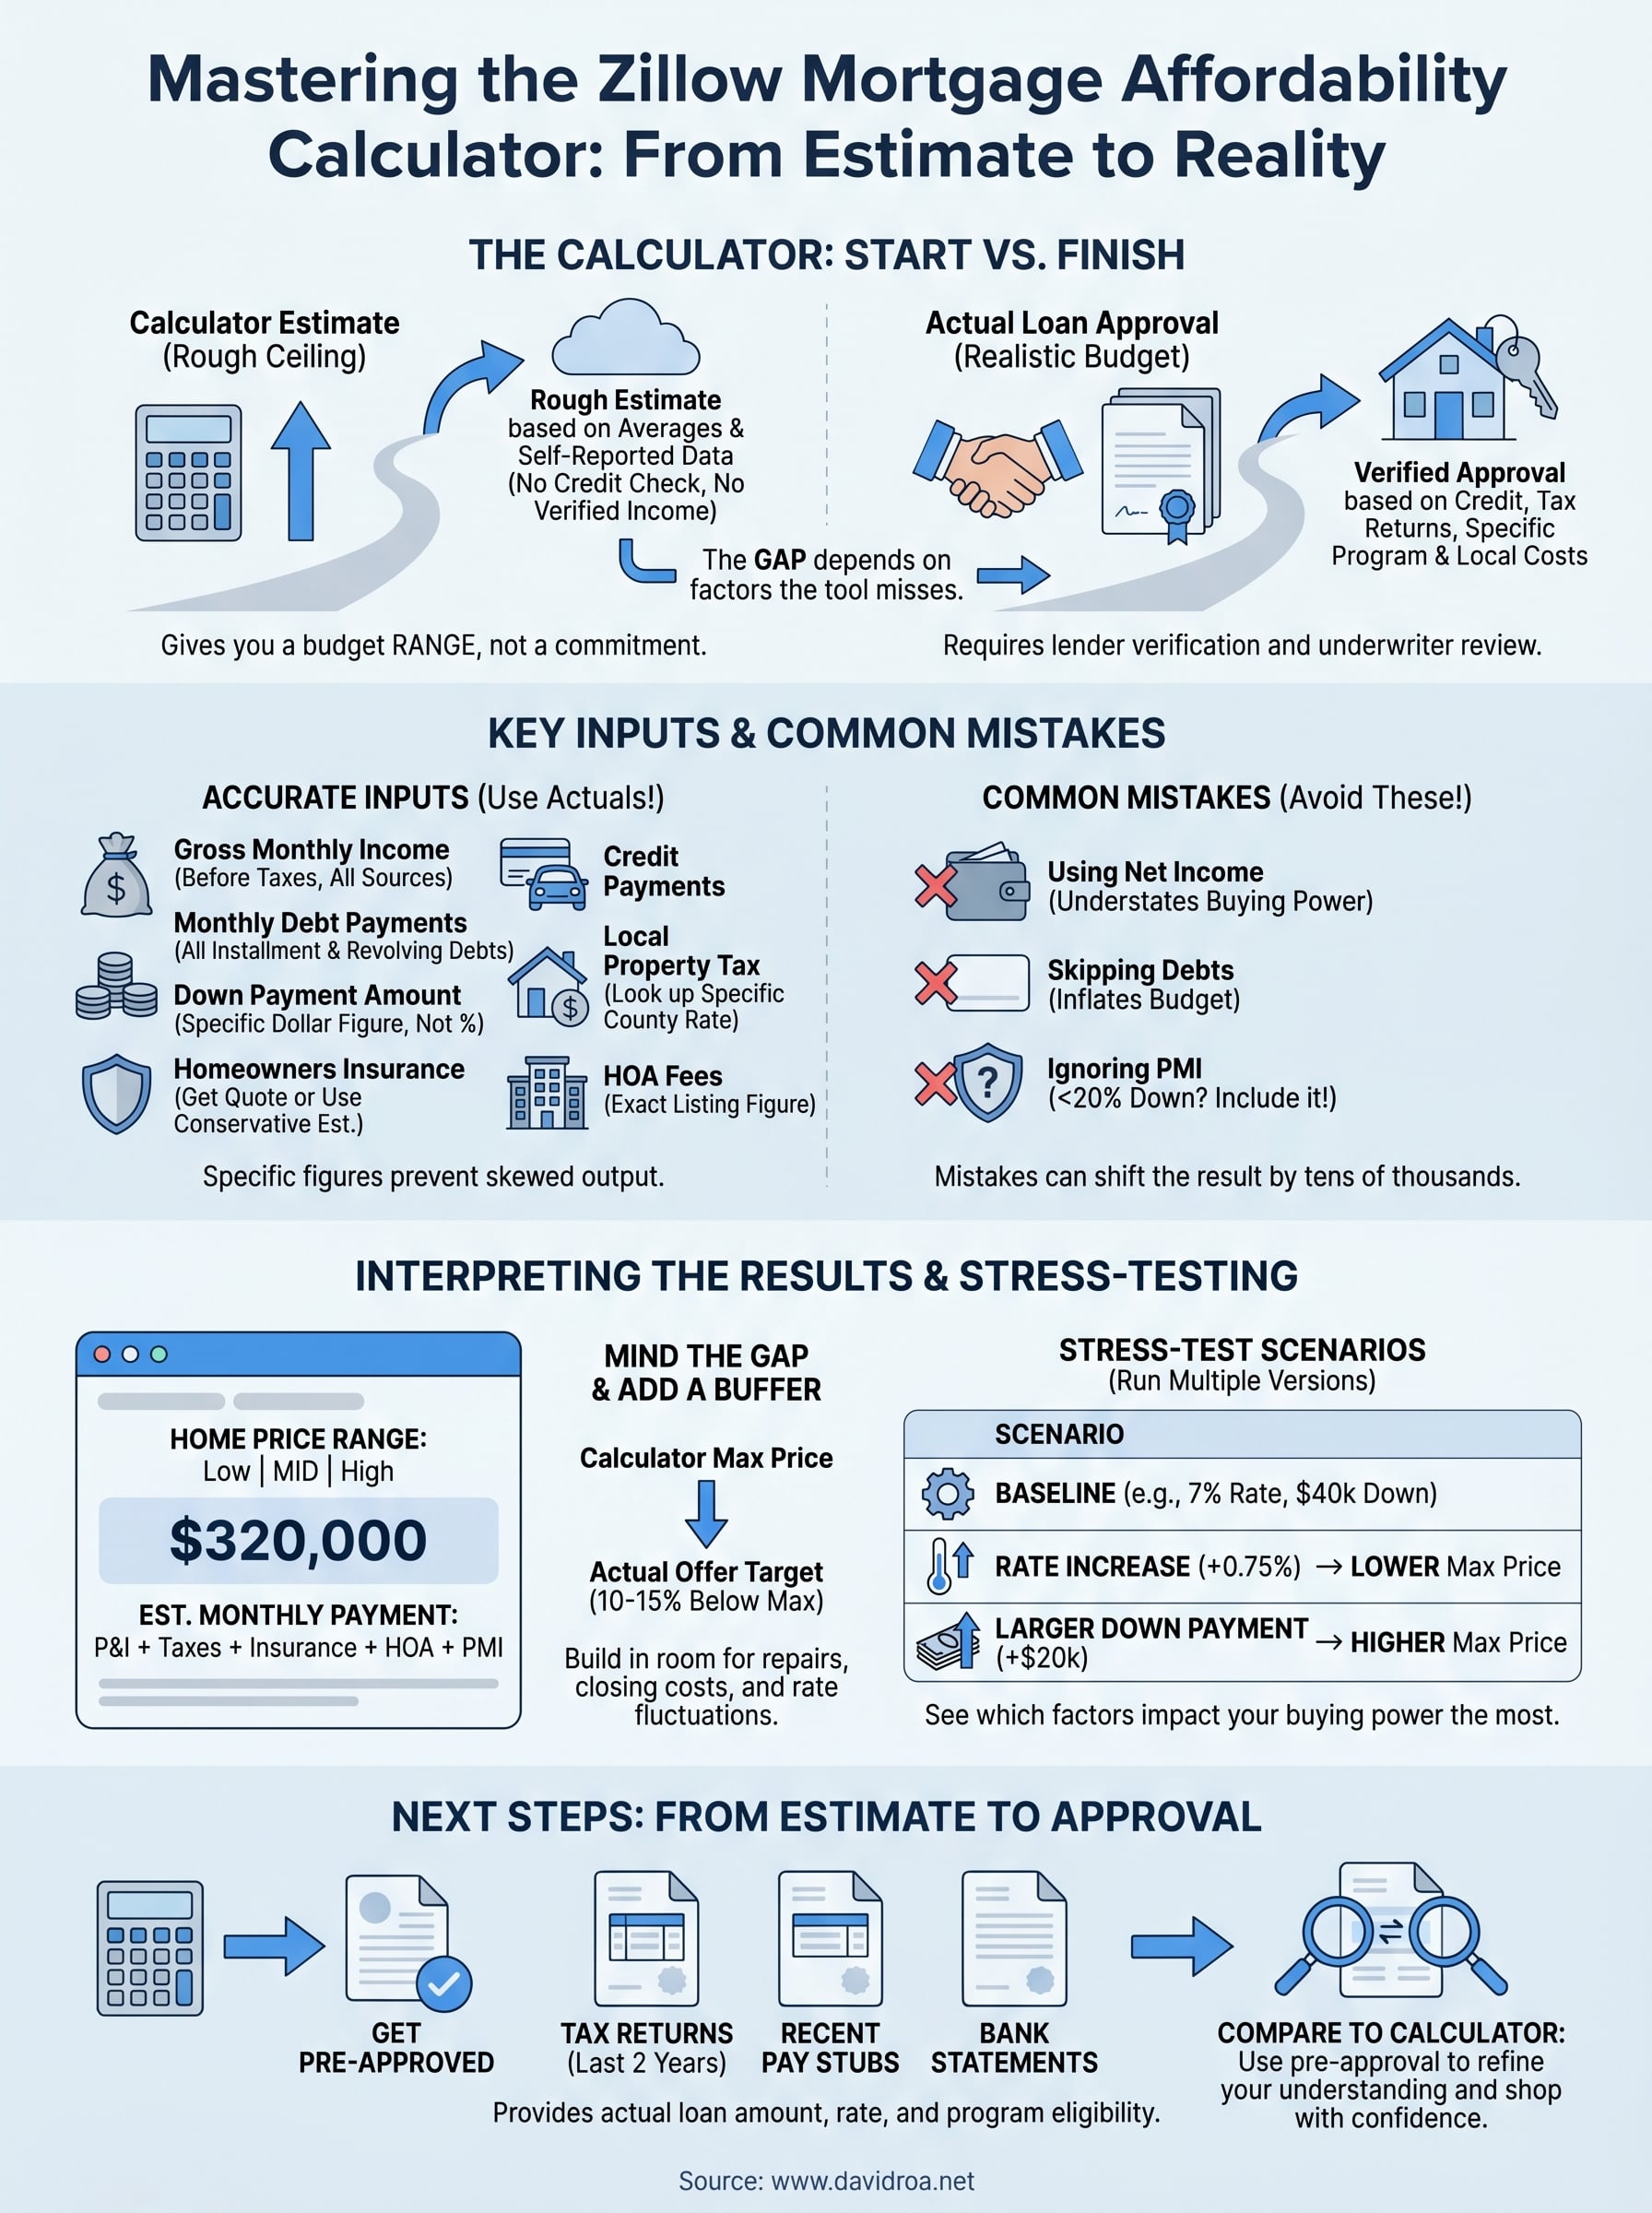
I used the Zillow Affordability Calculator every single time I sat down with a first-time buyer. It is fast, it gives you a starting number in under a minute, and that number will almost certainly be wrong by the time your real offer lands. I have seen buyers get excited about a $520,000 price range and then hit a wall at $448,000 because the calculator does not account for the local tax millage rate on the one street they were looking at. That is the first thing you need to understand before you treat this tool as anything other than a rough screening instrument. The calculator asks for gross annual income, monthly debt obligations, expected home price, down payment percentage, interest rate, and a few property-specific inputs. It then spits out an estimated monthly mortgage payment and tells you whether it fits inside your 28 percent front-end ratio or 36 percent back-end ratio. The mechanics are standard. The problem is the default assumptions baked into every field. By default Zillow assumes property taxes equal 1.2 percent of the home value per year, homeowners insurance at roughly 0.35 percent, and no HOA fees. If you live in Texas, New Jersey, or Illinois those property tax numbers are wrong by a factor of two or three. I learned this the hard way in 2022 when a client was pre-approved for $610,000 based on the Zillow output and then lost the bidding war at $535,000 because the lender recalculated the debt-to-income using the actual escrow amount from the county recorder's office. The gap was $92 a month, which translated into about a $75,000 difference in purchasing power. The workaround is manual adjustment before you trust any number. Take the Zillow result and rebuild the monthly payment in a spreadsheet with the actual tax rate for that county, the real homeowners insurance quote if you have one, and any HOA dues. When I do this for clients it usually takes eight to twelve minutes and cuts their apparent budget down by 8 to 15 percent in high-tax areas. That adjustment alone prevents three or four useless house tours per weekend.
What Most People Miss About How This Tool Actually Works
Zillow uses a simplified version of the standard mortgage amortization formula. It calculates the principal and interest portion using the Loan Amount divided by the present value of an annuity factor based on the monthly interest rate and total number of payments. Then it adds the estimated tax, insurance, and HOA line items. The tool does not include private mortgage insurance unless you select a down payment below 20 percent, and even then the PMI estimate is a generic calculation that does not reflect your actual credit tier or lender pricing. Lenders use Fannie Mae or Freddie Mac guidelines that vary by loan program, so the Zillow PMI guess can be off by 0.10 to 0.25 percent of the loan amount annually compared to what a real underwriter will quote. Another nuance that trips people up is the interest rate field. Zillow shows a national average for the rate you select, not the rate you qualify for. A borrower with a 740 credit score and 25 percent down in the same zip code can easily see a 0.375 percent difference compared to someone at 660 credit with 5 percent down. That spread changes the monthly payment by roughly $75 to $110 on a $400,000 loan over thirty years. When I have clients use this calculator I always tell them to plug in the rate their loan officer gave them during the pre-approval conversation, not the national average sitting in the dropdown.
When The Calculator Fails Completely
The affordability model breaks down in several predictable scenarios. It does not handle jumbo loans correctly because the rate and underwriting standards differ significantly from conforming loans. It does not account for special assessment districts, Mello-Roos taxes, or transfer taxes that some municipalities tack onto closing. It ignores closing cost assistance programs that can free up cash for a higher price. It also cannot process non-traditional income situations like self-employed borrowers with Schedule C deductions, commission-heavy earners, or recent immigration status where the lender requires two years of documented history but the borrower only has one. If any of those conditions apply to you, the Zillow number is essentially decorative. You should take your numbers to a licensed mortgage broker or lender who can run a full preliminary qualification using the Actual Documentation method. The broker quote typically arrives within 24 to 48 hours and gives you a hard number that actually holds up under underwriting review. I recommend treating the Zillow output as a conversation starter with that professional rather than a final answer.
Get the Full Details

Practical Steps To Get Something Useful Out Of It
Start by entering your real gross income, not your take-home pay. Put in every recurring debt payment you have including car loans, student loans, minimum credit card balances, and any child support obligations. Leave the down payment at your actual target percentage. Change the interest rate to your loan officer's current quote. Then immediately go into a spreadsheet and adjust the property tax rate to the exact percentage for the county you are targeting. Add the HOA fee if the neighborhood has one. Subtract the Zillow result and you will see where the divergence sits. Once you have that adjusted number you can use it to filter listings more intelligently. I set my search parameter at 95 percent of the recalculated budget rather than the full amount. Markets move fast and having a small cushion prevents you from making an offer on a property that is already stretched beyond your actual capacity. This habit alone has kept my clients from getting into bidding wars they could not financially sustain.
A Real Edge Case That Changed How I Use This Tool
There was a transaction in Riverside County where the property sat in a very specific tax zone with an above-average mill levy but the seller had just completed a property tax refinance that lowered the assessed value retroactively. Zillow pulled the tax data from public records at face value and calculated an annual property tax that was 40 percent higher than what the buyer would actually pay after the refinance closed. The calculator showed the monthly payment as unaffordable, but the real payment would have been within budget. I caught this by cross-referencing the seller's disclosure document and the latest county assessor notice before relying on the tool. It took me about six minutes to verify and saved a deal that would otherwise have died on the spreadsheet. This kind of situation is rare but it happens enough that blind reliance on any single online calculator is risky. Always verify the key line items against current local data before you let the output dictate your strategy.
Bottom Line
The Zillow Affordability Calculator is useful for initial screening and rough budget estimation. It gives you a number in under sixty seconds that is close enough to make it worth using. It is not accurate enough to serve as your final purchasing decision without manual adjustments and professional verification. Treat it as a starting point, not an endpoint, and spend fifteen minutes rebuilding the calculation with real local data before you share that number with anyone who matters in the transaction.