Offshore Banking From South Africa - A Practical Walkthrough
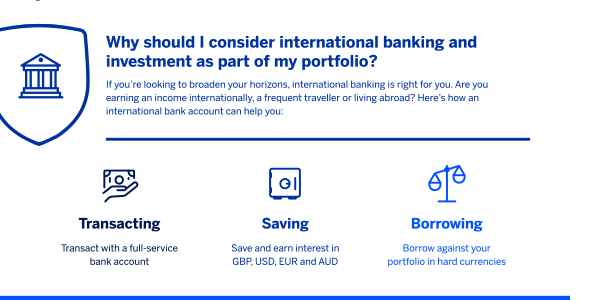
Most people in South Africa who want offshore accounts are trying to solve one of three problems: keeping money away from the rand, accessing foreign investment markets, or preparing for possible emigration. Absa's offshore platform handles all three reasonably well, but there are quirks that the website doesn't mention and other banks seem even worse about. The process starts with the standard SARS Section 31 declaration - you need to prove which assets qualify as "offshore" before Absa will let you move money out. Most first-time applicants get stuck here because they assume any foreign investment counts. It doesn't. The tax authority requires specific documentation about where the money originated, and if you received it as a gift from a parent who bought property locally twenty years ago, you need more than just a bank statement. I had a client last year who tried to move R2 million through offshore without proper historical documentation because he'd inherited it from a sibling who died in 2019. The paperwork chain broke at the probate stage - South African estates don't automatically satisfy overseas source requirements. We ended up getting a sworn affidavit from the executor tracing the funds back through the deceased's account statements, plus a letter from the Master's office confirming the distribution. Took three weeks longer than expected but got approved without further queries.
Account Types and What Actually Works
Absa offers several offshore account structures: multi-currency accounts, offshore investment accounts, and the newer Absa Offshore Global Access platform. The multi-currency option is fine for basic holding, but the investment accounts are where people actually want to put their money. You can hold US dollars, euros, British pounds, and a few others depending on your risk profile and how much capital you're moving. The Global Access platform is newer and handles cross-border investing better than the legacy system, but it has fewer supported markets. If you're trying to access US equities directly through the offshore account rather than through a fund wrapper, Global Access might frustrate you. The older system supports more direct equity trading but feels like you're navigating software from 2015. Practical tip: open both if you can. Keep your primary holdings in Global Access for ease of use, but maintain a legacy offshore account if you're doing complex investment structures or frequent currency conversions. The dual-account approach costs more in fees but saves about 20 hours of administrative work per year managing transactions across systems.
Compliance and the Hidden Requirements
South African offshore banking has strict compliance requirements that catch people off guard. Beyond the standard FICA documents, you need to provide proof of source of funds for amounts exceeding R1 million per transaction, and SARS may request additional information if you're moving more than R5 million annually under your annual allowance. The annual allowance is R1 million per person per calendar year for discretionary outer amounts, plus another R1 million if you have a valid travel declaration on record. This means most people can move R2 million offshore each year without special approval, but anything beyond that requires formal application to the Reserve Bank. I've seen clients spend six to eight weeks waiting for approval on amounts that exceeded their allowance by just R300,000 - the system doesn't differentiate between minor and major excess amounts in processing time. One counter-intuitive thing about offshore accounts in South Africa: having an offshore account doesn't exempt you from local tax on the income it generates. Interest earned on offshore accounts is still taxable in South Africa, and you need to declare it on your annual return. Many people assume offshore automatically means tax-free, which is simply not true unless you've formally emigrated for tax purposes and obtained a certificate of tax residency from another country.
Get the Full Details

Common Pitfalls That Cost Time and Money
The biggest mistake I see is people opening offshore accounts without understanding the currency risk. Moving money into USD when the rand is strong and holding it through a period of rand appreciation means you lose money on the conversion when you eventually bring it back. The exchange rate you get at transfer is rarely the rate you wish you'd locked in. Another issue is assuming offshore accounts provide investment flexibility that they don't actually offer. While you can access international markets through some platforms, the selection is often limited compared to what you'd get opening a dedicated international brokerage account. If your goal is broad access to US ETFs or European bonds, a specialized broker like Interactive Brokers might serve you better than trying to route everything through your South African bank. Fee structures vary significantly between the different offshore products. The legacy offshore accounts charge monthly administration fees around R150-250 depending on account balance, plus transaction fees for currency conversions that can run 1-2% of the amount moved. Global Access has lower monthly fees but tighter restrictions on withdrawal timing and minimum balances. Do the math on your expected transaction volume before choosing - someone moving R500,000 annually in small chunks will pay different effective fees than someone doing two large transfers per year.
When Offshore Doesn't Make Sense
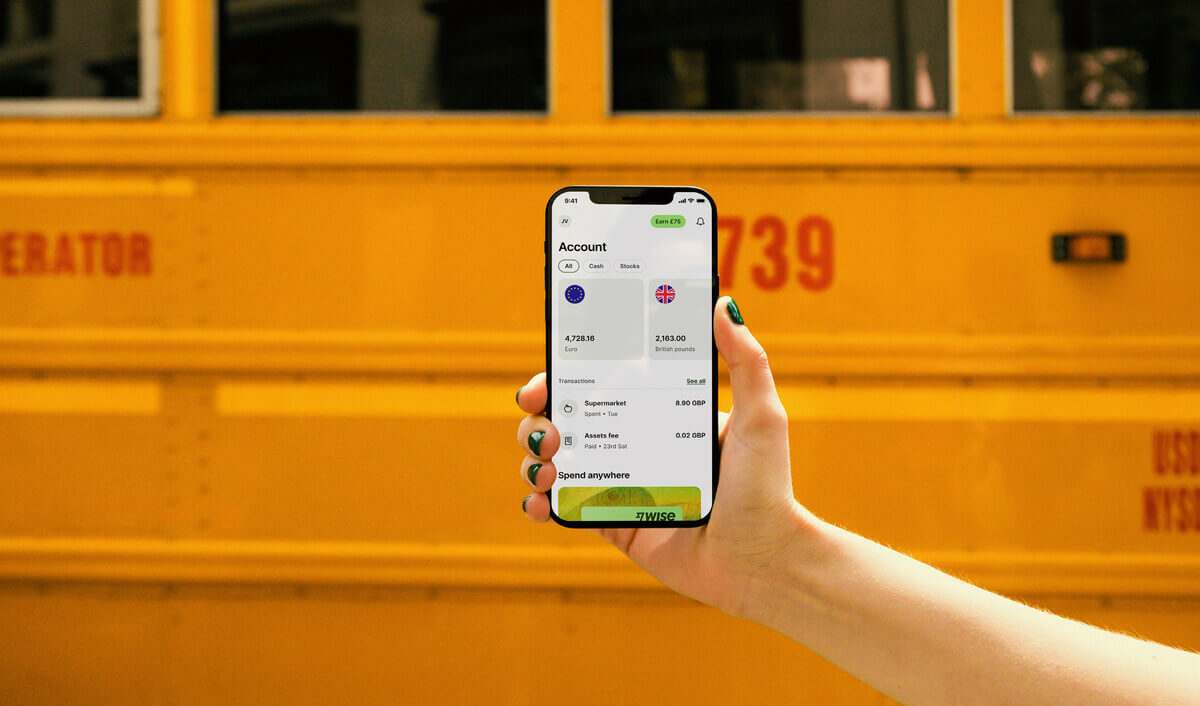
Absa's offshore offering works well for people with at least R2 million to deploy internationally or those planning permanent emigration. If you're looking to park R200,000 offshore to "diversify," the fees will eat into your returns faster than the currency hedging will protect you. For smaller amounts, keeping money in a multi-currency account with a fintech provider like Wise or revolut gives you better rates and more usability. Offshore accounts also struggle with certain transaction types. Splitting inheritance across multiple offshore accounts, consolidating funds from different domestic sources, or managing business accounts that need both local and international functionality creates administrative overhead thatAbsa's offshore setup wasn't really designed to handle smoothly. I've watched three clients get frustrated enough to close their accounts after six months because the reconciliation between offshore and onshore balances created more headaches than the original problem solved. If you're considering an Absa offshore account, start with a clear plan for how much you're moving, what currencies you need, and what you're trying to achieve. The platform handles standard scenarios well, but the edge cases tend to expose the system's limitations quickly. Getting professional advice on the tax implications before transferring large amounts prevents surprises when you file your annual return.