How Chase Visa Cards Actually Work
Chase offers several Visa cards with different rewards structures, and the application process is straightforward if you know what to expect. Most people get confused about which card fits their spending habits, then apply for the wrong one and waste time getting rejected. I've been watching the credit card space for years, and Chase remains one of the more predictable issuers when it comes to approval odds. Their algorithm checks your credit score, income, debt-to-income ratio, and recent hard inquiries. That's it. Nothing dramatic happens behind the scenes.
Unlock Financial Flexibility The Complete Guide To Chase Visa Cards Rewards And How To Apply
Here's the thing most guides skip. Chase has five cards in their Visa lineup that matter for everyday rewards. The Chase Sapphire Preferred earns 5x on travel booked through their portal, 3x on dining, and 2x on other travel. The regular Chase Sapphire card bumps that to 6x travel and 6x dining. The Chase Freedom Unlimited gives you 5x on travel through Chase, 3x on dining and drugstores, and 1.5% back everywhere else. The Chase Freedom Flex works similarly but adds rotating 5% categories each quarter. Then there's the basic Chase Visa Signature with no frills and no annual fee. I applied for my first Chase card in 2018. Got declined on the Sapphire Preferred. Turned out I had two hard inquiries from the previous three months and a utilization rate of 41% on my existing cards. Chase requires below 40% utilization at the point of application, and they count inquiries heavily. I waited six weeks, paid down my balances, and applied again. Approved same day.
The Application Process
You can apply online at chase.com in about four minutes if your information is ready. Have your social security number, annual income, and monthly housing payment handy. Chase verifies employment, so if your income doesn't match what shows up on credit bureaus, expect a manual review that takes three to five business days instead of instant approval. Some people don't realize Chase counts related accounts together. If you already have a Chase Sapphire card, you generally only qualify for one Chase Rewards card. Their terms state you can only earn the sign-up bonus once per card per lifetime. This trips up people who already have a Sapphire Preferred and try to apply for a new Sapphire card hoping for a second bonus. It doesn't work.
Get the Full Details
Rewards That Actually Matter
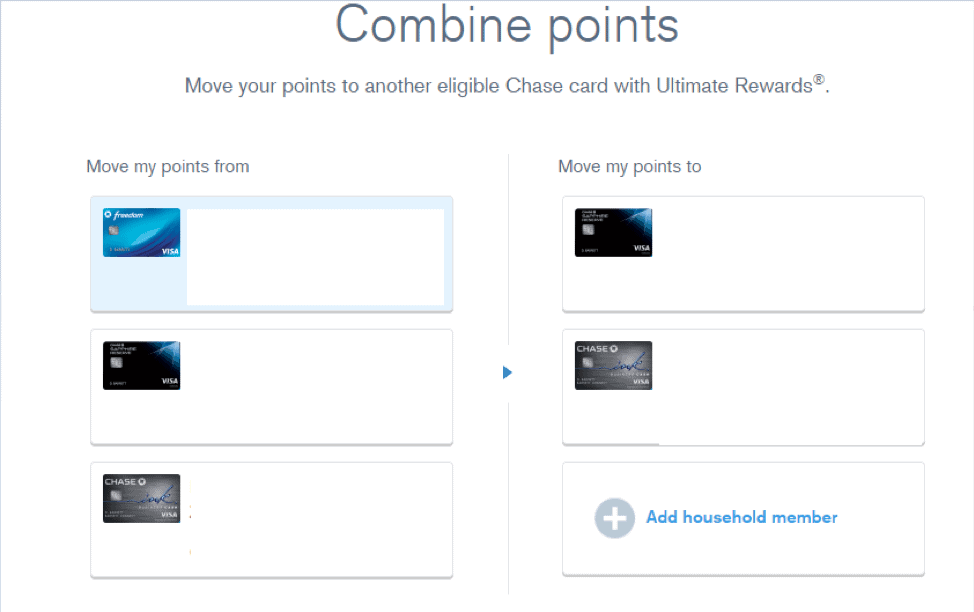
The Chase Ultimate Rewards program transfers points to airline and hotel partners at a 1:1 ratio. This is where the real value lives. Transferring to United MileagePlus or Southwest Rapid Rewards typically yields 1.5 to 2 cents per point when redeemed for flights, compared to about 0.8 cents per point if you just book travel through the Chase portal. I transferred 40,000 points to Southwest last year and booked a roundtrip flight between Chicago and Denver. Paid 28,000 points plus about $110 in taxes. Same flight would have cost roughly $380 cash. That's a redemption rate of about 2.2 cents per point after accounting for the cash portion. The catch is transfer times. Chase processes point transfers instantly in most cases, but I've seen them take up to 48 hours during peak travel seasons. If you're booking a last-minute flight, do not wait until the day of travel to transfer. Transfer three days ahead minimum.
Common Mistakes People Make
Most applicants mess up the annual fee calculation. The Sapphire Preferred charges $95 annually. The regular Sapphire card costs $200 but includes a $200 annual travel credit that auto-applies. If you spend less than $200 on travel per year, the cheaper card is mathematically better. Simple arithmetic, but people ignore it. Another issue is chasing sign-up bonuses without understanding the spending requirement. The current Sapphire Preferred offer asks for 60,000 points after spending $4,000 in three months. That's $1,333 per month. If your monthly spend is around $800, you'll either miss the deadline and lose the bonus, or you'll inflate your spending artificially, which defeats the purpose entirely. I had a friend who did exactly that. Spent an extra $2,000 on home goods she didn't need just to hit the threshold. She got the bonus, sure, but she spent $2,000 to earn maybe $900 in value from the points. Net loss of $1,100. Not how this works.
When Chase Cards Don't Make Sense
Chase isn't the right move if you travel internationally frequently and want a card with no foreign transaction fees alongside strong lounge access. Their rewards cards have no foreign transaction fees, which is good, but they don't come with Priority Pass lounge memberships or similar perks. If lounge access matters to you, look at Amex or Capital One instead. They also aren't ideal if you have poor credit. Chase is stricter than most issuers. A score below 670 makes approval unlikely on any of their rewards cards. The Chase Secured Visa exists as an alternative, but it earns zero rewards and functions more like a regular debit card with a credit report attached. There's also the Chase 5/24 rule to consider. If you've opened five or more personal credit cards from any issuer in the past 24 months, Chase will automatically decline your application. This rule applies regardless of your credit score or income. I've seen people with 800 FICO scores get denied because they hit 5/24. There's no workaround other than waiting out the 24-month window.

If you're already close to that limit, focus on maintaining existing accounts rather than opening new ones. The value of keeping your credit history intact usually outweighs whatever sign-up bonus a new Chase card would offer.