How I Found Out About My Amex Pre-Approval — And What Actually Happened After
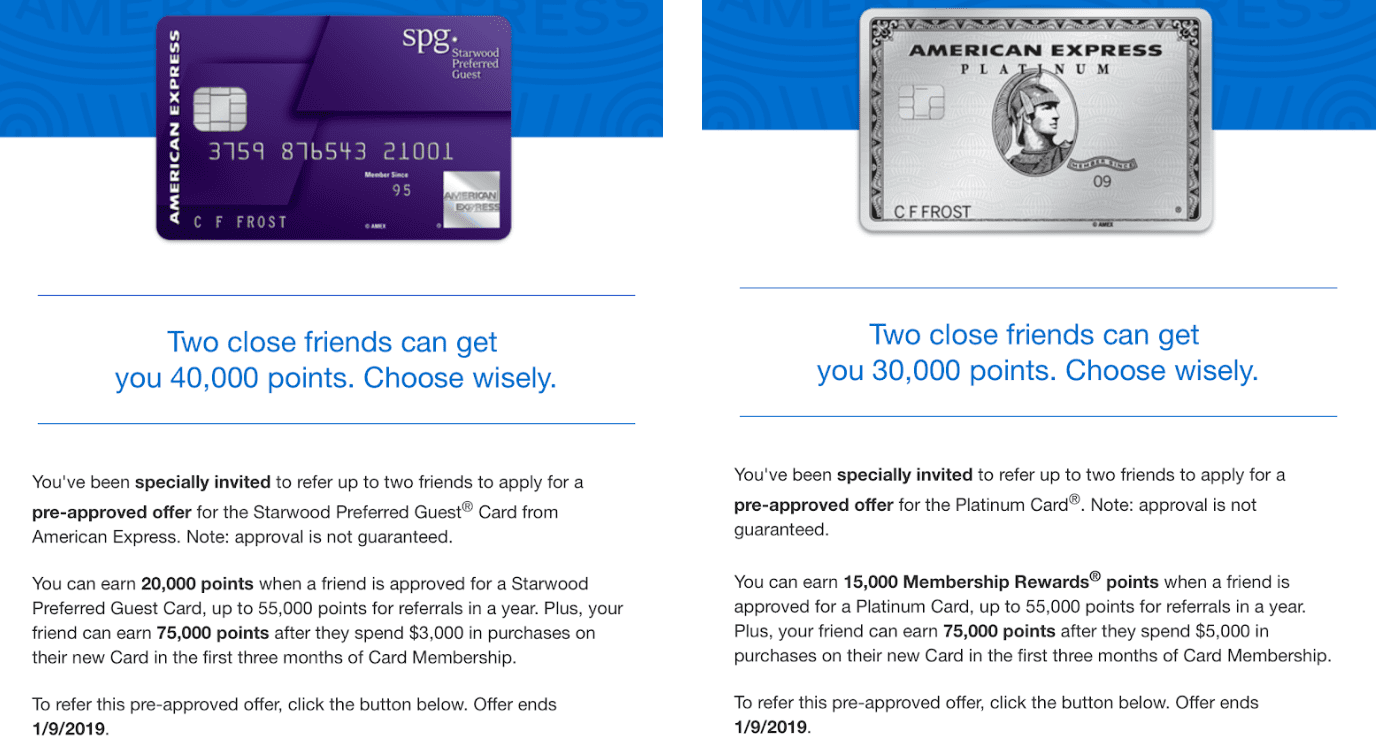
I was cleaning out my mailbox one Tuesday and noticed a thick envelope from American Express with my name already on it. Not a generic mailing label, not a digital ad, not a sweepstakes. It had my exact address, my real name, and a reference number that looked important. I didn't open it right away because I've learned over the years that these things usually have fine print nobody reads until they're already on the phone with someone. The subject line said something about being "pre-selected" for a new card. I should have just thrown it in recycling, but I had been thinking about getting a card with better travel benefits for a while. The card in question was the Platinum Card, and the offer claimed I could get pre-approved for a credit limit between $10,000 and $15,000 if I applied within 30 days. Here's the thing nobody tells you about these pre-approval offers: they're not guaranteed. American Express calls them pre-selected, not pre-approved, and the difference matters more than the marketing copy suggests. What the offer actually means is that based on your existing relationship with Amex and your current credit profile, you meet their internal screening criteria well enough that they want you to apply. But the final decision still depends on a full credit review, and I learned that the hard way.
Understanding What the Pre-Approval Offer Actually Means
A pre-approval from American Express uses what they call a soft pull for the initial selection. That means when they pick you as a candidate, it doesn't show up on your credit report in a way that hurts your score. But once you actually submit the application, they run a hard inquiry, and that shows up as a legitimate credit pull. I wish I'd known this before, because I got a bit smug about the whole thing and then got rejected anyway, which stung more than a straightforward decline would have. The whole concept here is that Amex has data on you already. If you've had a Green Card or a Gold Card for a few years and you've been paying on time, they can see that. They use that history, along with your broader credit profile from the bureaus, to identify people who are likely to qualify. The pre-approval offer is basically them saying we think you'll pass our initial checks. It's not a promise. It's a probability weighted in your favor. What most people don't realize is that the pre-approval process also works the other way around. Sometimes you'll see an offer for a card you already have, like being "pre-approved" for an upgrade to the Platinum from your existing Green. This is actually more useful than a cold offer because Amex already knows your payment behavior. I got pre-approved for a limit increase on my Gold Card last year, and it went through in under three minutes with zero additional documentation. That's the real power of the pre-approval system, not the fancy cards that flash on your screen.
How to Check If You Have a Pre-Approval Offer
You can find out if Amex is offering you a pre-approval without waiting for mail. Go to their website and click on the apply button for whatever card interests you. Before you fill in anything, there's usually a link that says check your rate or see if you pre-qualify. This runs a soft inquiry and tells you whether you meet their preliminary criteria. I used to skip this step and just apply directly, which meant every time I wanted to try a new card I'd take a hard pull on my credit. That added up fast. Once I started checking first, I saved myself three unnecessary inquiries over a two-year period. The only downside is that sometimes the online pre-qualification doesn't match the mail offer. I once saw an offer in my mailbox for the Platinum Card but the online check said I wasn't eligible. The mail version was correct, so I went with that. Mail offers seem to use a slightly different screening threshold.
Get the Full Details
My Actual Experience Applying Through the Pre-Approval
When I finally decided to go through with it, I had the mail offer in front of me. The reference number on the envelope was important. I entered it on the application page, and it pre-filled some information based on my existing account history. That saved maybe five minutes and probably didn't affect the decision at all, but it felt smooth, which matters when you're sitting there hoping for a yes. The application itself took about eight minutes. I had my Social Security number ready, my annual income, and my housing payment. Nothing exotic. The moment of truth came when I clicked submit, and I got the automated decline screen within twenty seconds. Not a phone call, not an email, just a gray box telling me I didn't qualify at that time. I found out later that the rejection wasn't about my credit score, which was solid. It was about my debt-to-income ratio. I had a small car loan payment that I'd been neglecting to include when I estimated my monthly obligations. I listed a lower number than I should have, and the automated system flagged the discrepancy. This is the kind of edge case that catches people off guard, especially if they're applying fast and not double-checking their numbers.
What to Do After a Pre-Approval Decline
Getting declined after a pre-approval hurts in a specific way because you feel like you already qualified. You didn't. The pre-selection was just an invitation to apply, and the application itself is where the real review happens. I waited about six months before applying again, and by then I'd paid down the car loan entirely and made sure my credit utilization was under ten percent on all revolving accounts. The second application went through. Got the Platinum, six thousand dollars in sign-up bonus points, and a $650 annual fee that I've found worth it for the lounge access and travel credits alone. One thing I noticed that almost nobody mentions: Amex pre-approvals tend to run on a rolling cycle, not a fixed schedule. Some people get offers every quarter. Others get nothing for a year and then three in a month. I can't explain the pattern, but if you're not seeing anything, it might just be your turn hasn't come around yet. Don't spam applications trying to force the system to notice you. That backfires.
The Real Limitation of Pre-Approval Offers
The biggest limitation is that pre-approvals don't work well if you have recent negative marks. A late payment in the last twelve months, a collections account, or even a recent bankruptcy can void the pre-selection entirely, even if your overall score looks fine. Amex is stricter than Chase or Capital One on this. They don't just look at the FICO number, they look at the internal timeline of your payment history, and that goes back further than most people realize. Another limitation I ran into is that pre-approvals are card-specific. Being pre-approved for the Gold Card doesn't mean anything when you're applying for the Platinum. I learned this the hard way after seeing a Gold Card pre-approval and thinking it gave me some leverage for the Platinum. It didn't. Each card has its own threshold, and the Platinum one is notably higher than the Gold or Green. If you're aiming for Platinum, check the Platinum pre-approval specifically, not a lower-tier one. There's also a geographic component. Some pre-approval offers only apply in certain states due to regulatory differences. I had a friend in New York who kept getting pre-approvals, while his sister in California with an almost identical credit profile never saw one. This isn't a bug, it's just how the offer distribution works, and there's nothing you can do about it except apply when something lands in your inbox and hope it's valid for your state.