The JCPenney Credit Card: What It Actually Is Right Now
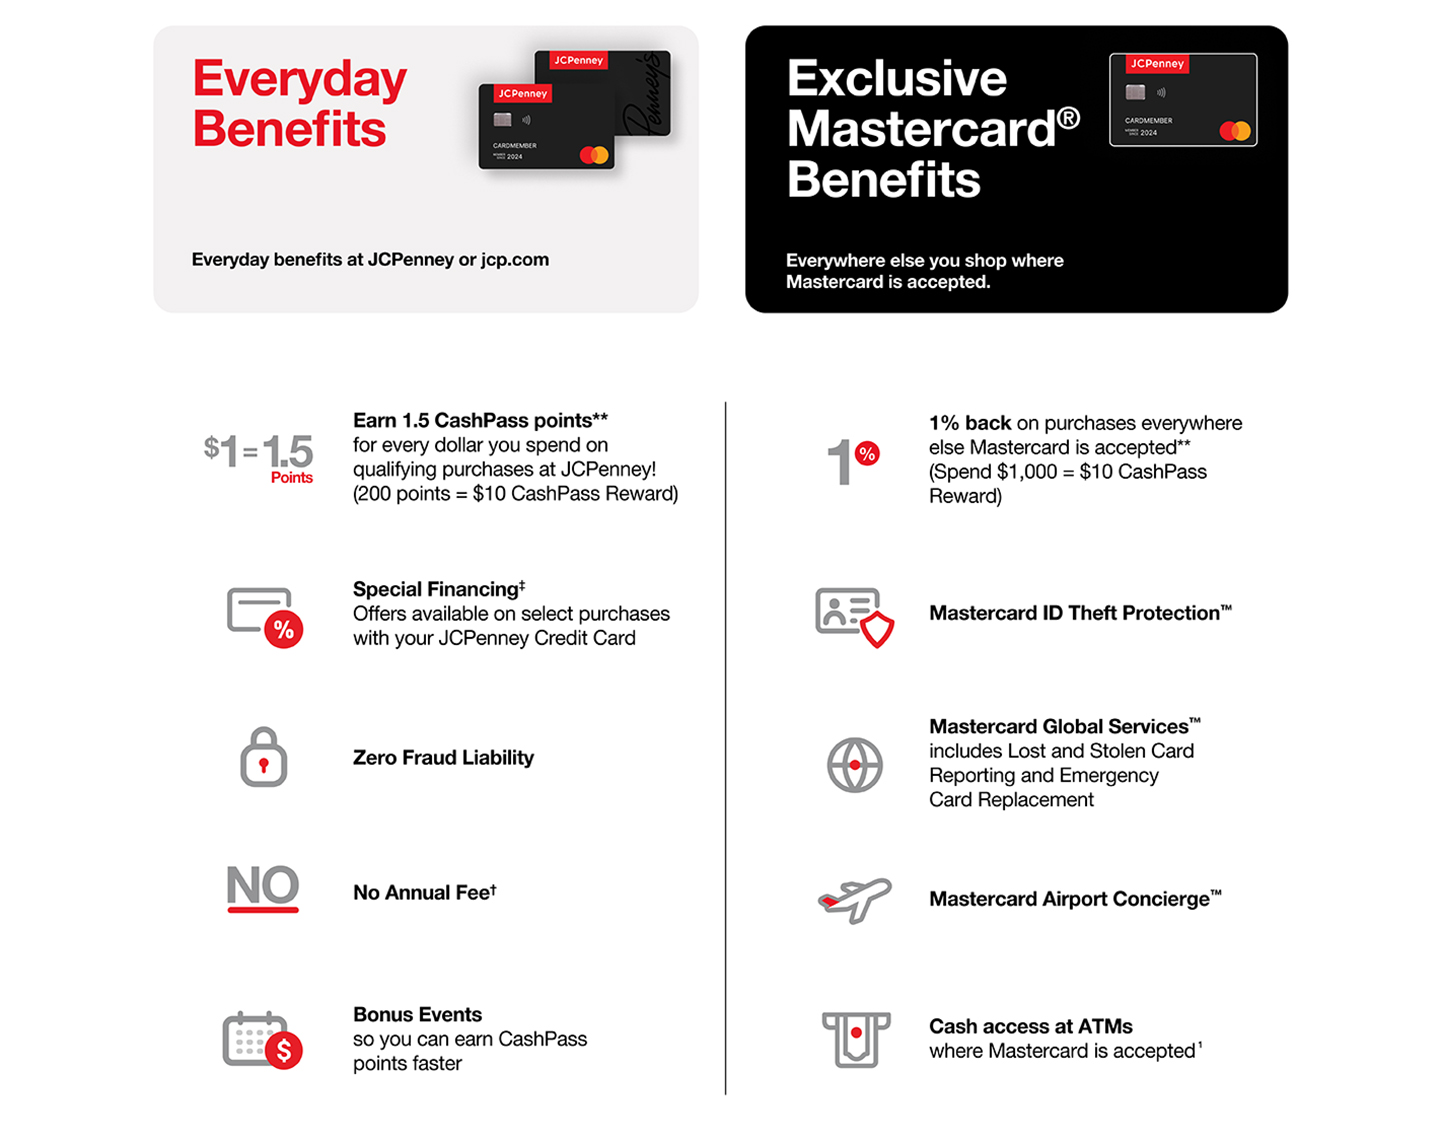
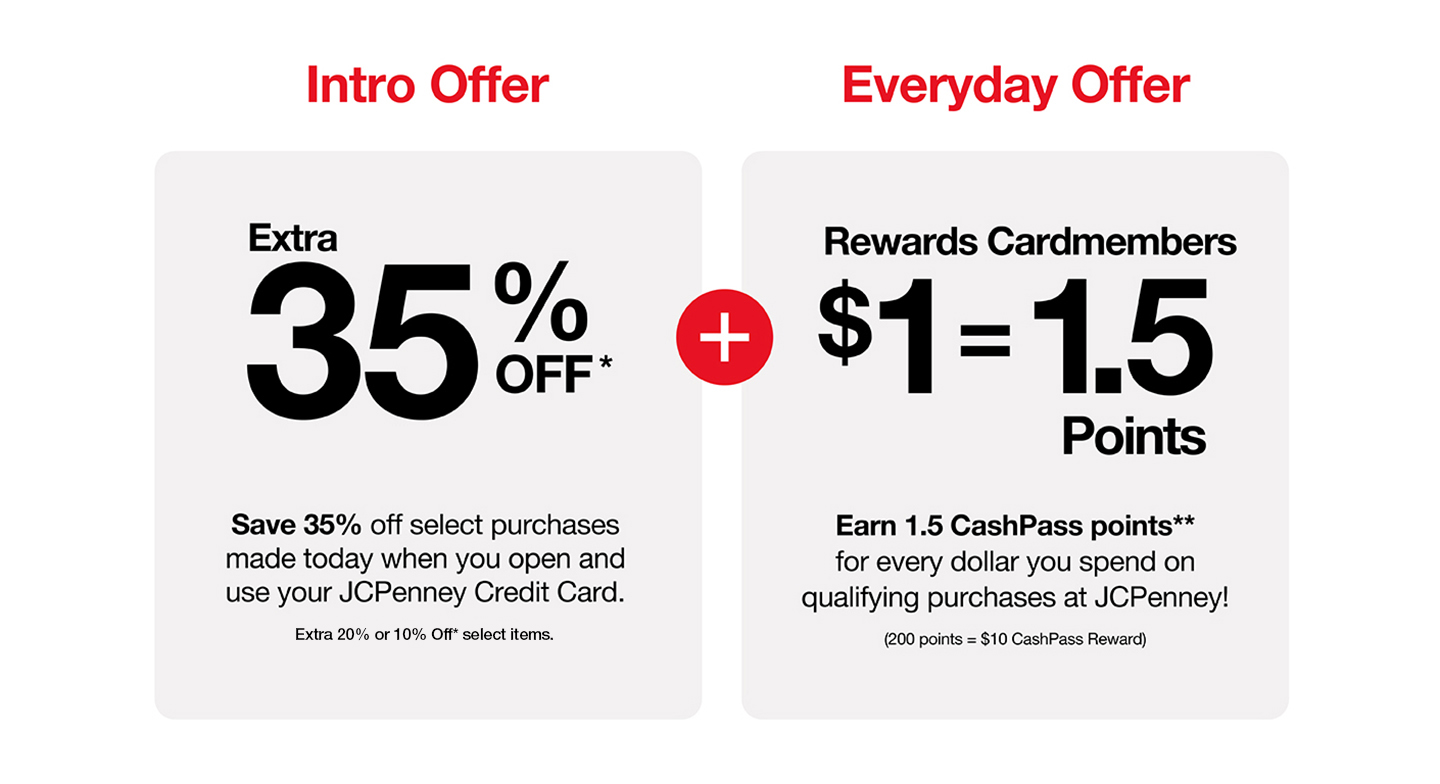
The JCPenney credit card is issued by Synchrony Bank and comes in two flavors: a store card you can only use at JCPenney and a Visa version that works basically anywhere. Both fall under their Rewards Program, which has gone through a few structural changes over the last several years. If you are looking at applying, the first thing you need to know is that JCPenney has not been openly accepting new store card applications in some periods. They have opened and closed that window based on internal decisions. So check whether the application portal is actually live before you go down that road. Getting value from this card comes down to understanding how the reward tiers and promotions layer on top of each other. Here is how it actually works in practice. You earn points on purchases. The base rate for most tier members sits around one point per dollar at JCPenney. Preferred tier members get a higher rate. There have also been periodic boosts where certain categories or specific promo periods multiply your earnings. The real savings come from the promotional financing and event sales. JCPenney regularly runs credit cardholder-exclusive sales. These are not always advertised on the main site. You often find them in your account dashboard or in email communications. A typical example is an early access window where cardholders can shop a sale a day before the general public. That alone can shift your total savings significantly if you were planning to buy something anyway.
I spent a fair amount of time tracking these events over the years. One thing that caught me off guard early on was how the points expiration policy worked. Points used to have a threshold minimum before they could be redeemed for rewards. If you were sitting just below that threshold near the end of the year, those points could disappear. My workaround was simple: I set a calendar reminder for the first week of December every year. I would check my balance and either apply points toward an upcoming purchase or combine them with a small qualifying spend to lock them in. It takes about ten minutes and prevents losing whatever you have accumulated.
Applying and Getting Started
If applications are open, you apply directly on the JCPenney website or through the Synchrony Bank portal. You will need a Social Security number, income information, and a checking account or banking reference in some cases. The approval decision is usually instant or within a few business days. Once approved, you receive a card and your account is activated. You can then link it to your online profile and check your current reward tier. The Visa version of the card operates slightly differently. It is a network card with its own terms. Sometimes the rewards structure differs from the store card. Make sure you know which one you signed up for. Mixing them up can lead to confusion when you are trying to figure out why a purchase did or did not earn points as expected.
Get the Full Details
Common Pitfalls and What to Watch For
One counter-intuitive thing about this card is that the highest stated rewards rate is not always the best deal for you. If you are a casual shopper, the base tier may already give you enough value compared to other store cards. Chasing Preferred status requires consistent spending. You need to do the math on whether the extra points per dollar outweigh any annual fees or promotional rates you might miss because you are concentrated at one retailer. Another issue is deferred interest promotional financing. JCPenney has offered zero-percent financing windows on larger purchases. The fine print matters here. If you do not pay off the full balance before the promo period ends, interest charges are applied retroactively to the original purchase date. This is not a soft penalty. It is full deferred interest. I learned this the hard way when a friend of mine bought a mattress set during a promotion and assumed monthly payments would clear it. They missed the final payment by a few days and got hit with months of accrued interest. The workaround is straightforward: set up automatic payments for at least the minimum, and then manually pay down the balance each month until it is cleared. There is also the question of whether this card is worth it if you do not shop at JCPenney regularly. The store card is limited to JCPenney purchases. That is a significant constraint. If your nearest JCPenney is far or you rarely shop there, the card offers limited utility. In that case, a general cash-back card like the Capital One Quicksilver or the Citi Double Cash would likely serve you better. Those cards give you rewards everywhere, and the annual percentage rates are often competitive.
Maximizing Rewards Without Overcomplicating It
The most practical approach is to treat the card as a supplementary payment method for planned purchases, not as a primary card for everyday spending. Use it when you are already buying at JCPenney. Stack it with catalog coupons, mail-in rebates, and cardholder-only sale events. That is where the compounding effect happens. The points themselves are useful but they are secondary to the promotional pricing. Keep an eye on your account for personalized offers. Synchrony occasionally sends targeted promotions like bonus points for a specific product category or a matching discount on your next purchase. These are not guaranteed and they rotate, but they show up in your account rewards section or via email. Checking once a week takes less than a minute and can surface a legitimate extra saving. Finally, be aware that credit card programs change. Terms shift. Reward rates adjust. An offer that looked good last year may be different today. The most reliable method is to read the current cardholder agreement each time you consider using the card, not just when you apply. The details matter more than the headlines on promotional pages.