How to Sign Up and Use the Ultabeautyrewards Mastercard Through Comenity
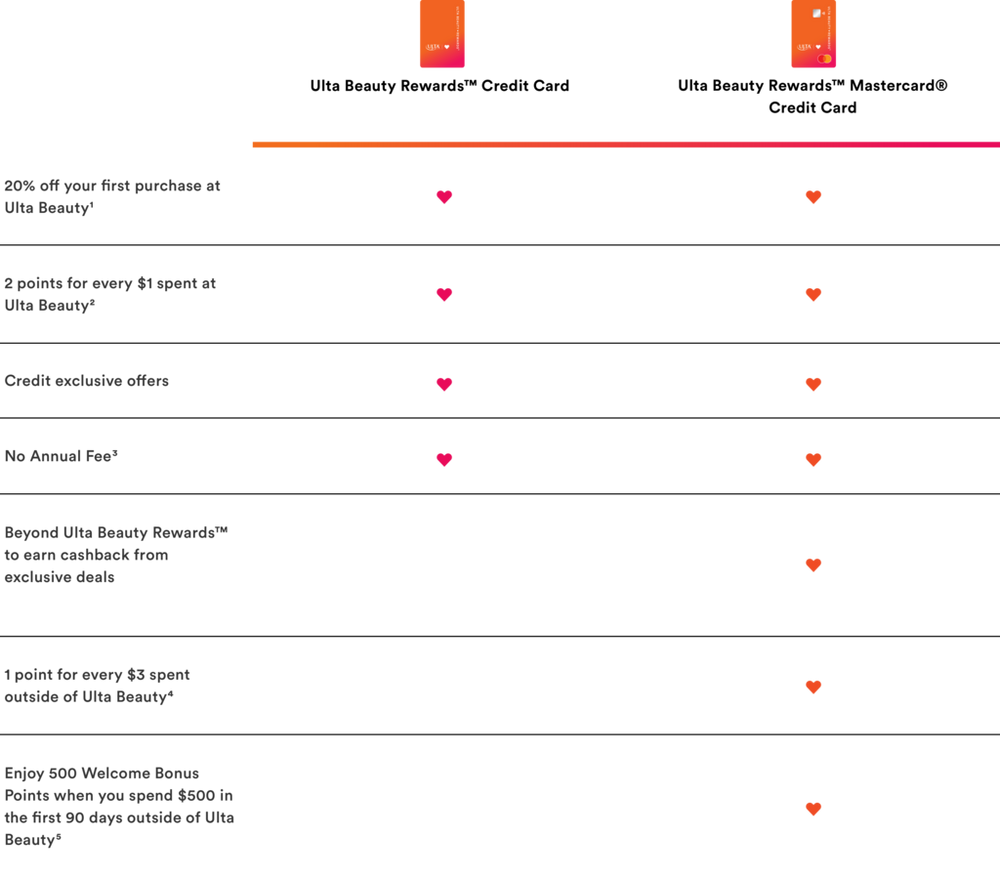
Getting your hands on this card is straightforward if you know what you're doing, but there are a few steps that trip people up. The card is issued by Comenity Bank, which means your account portal lives at comenity.net, not some branded portal on the Ulta website. You'll need a Social Security number, a government-issued ID, and proof of income ready during the application. Most people get a decision in under a minute, but it's not guaranteed. The approval threshold tends to sit around 670-700 credit score territory, though that shifts depending on how much existing debt you carry and what your credit utilization looks like right now. Here's the part most people skip reading: the rewards structure is split into tiers. You earn 2X points on every dollar at Ulta on regular purchases, and 1X everywhere else. But the real value comes from the tiered benefits — 10X points during birthday month, occasional promo codes that boost earnings to 5X for limited windows, and those "points multipliers" that run during seasonal events like the Sephora birthday club equivalent, except on Sephora, which you can't use at Sephora. Yeah, don't mix them up. I've seen people apply for this thinking it works at every beauty retailer. It doesn't. The sign-up bonus changes periodically. At the time of this writing, it's been sitting around 10,000 points after spending $250 within the first 90 days. That converts to roughly $50 off your next Ulta purchase. It's not the most aggressive bonus on the market, but for someone who shops at Ulta regularly, it pays for itself in two or three visits.
Setting up your account requires you to go to Comenity's portal directly. Once approved, you'll get an email with a link to register. Don't click a link from the Ulta confirmation page — they sometimes redirect to outdated portals. Go straight to comenity.net and create your login from scratch. I lost access to my account for about four business days once because I signed up through a third-party link that pointed to a deprecated staging environment. Comenity's support team couldn't even help because my account didn't exist in their production database yet. Took a follow-up call to get it resolved. Now let's talk about the points. They expire after 18 months of account inactivity. This is where people get hit. You might earn a big chunk of points during a sale, forget about the card for a year, and come back to find half your balance gone. I had about 4,200 points sit there for 14 months until a random $30 purchase kicked the account back to active status. If you don't shop at Ulta at least once every six months, these points will evaporate. Consider that when you're deciding whether this card makes sense for you. There are a couple of things beginners miss. First, the card does not stack with Ulta's standard Rewards program for the base earning rate. You already get 1 point per dollar at Ulta just by being a member. The Mastercard gives you the extra point on top, so effectively you're earning 2X total at Ulta, but the promotional multipliers from Ulta's own sales do apply on top of that. Second, the card can be used online, in-store, and for phone orders at Ulta. It cannot be used for third-party purchases or gift cards bought at Ulta. Some people try to load up points by buying gift cards and then using them — that gets flagged and the points get clawed back.
Another edge case: if you upgrade from the standard Ultabeauty Mastercard to the Platinum version, you need to reapply. The upgrade isn't automatic, and you go through the full underwriting process again. A hard inquiry lands on your credit report both times. Don't apply for both on a whim. I watched a friend tank his score by applying for the standard card, getting declined, then immediately applying for the Platinum version thinking the rejection would count differently. It didn't. Two hard pulls in the same week, both resulting in no card. Payment options are standard. You can set up autopay for the minimum due or full balance. Late payments trigger a $40 fee and an APR increase to the penalty rate, which has historically sat around 29.99% variable. That rate jumps the moment you miss a payment by 30 days. If you carry a balance on this card, treat it like an emergency, not a normal financing tool. The rewards earnings do not offset the interest cost unless you're paying in full every month. The biggest mistake I see is treating this as a general-purpose cash-back card. It isn't. The 2X rate only applies at Ulta. Everything else earns 1X, which is worse than most flat-rate cards. If you shop at Ulta more than three times a year, it's worth keeping. If you occasionally grab mascara and forget the card exists for eight months, the inactivity expiration will eat your points and the card becomes dead weight. Canceling is an option if you can't justify it, but don't cancel impulsively either — you lose the account age benefit on your credit report, and that matters more than people realize.
Get the Full Details

The annual fee is zero. No surprise there. The interest rate range for new accounts typically runs from 18.99% to 29.99% variable, and again, that's why you pay it off every month. If you have the discipline to do that, the card is a reasonable tool for frequent Ulta shoppers. If you're the type who carries a balance, walk away from it.