Getting Real Value From Your Wells Fargo Online Account
I have been managing my own banking through Wells Fargo's portal for about eight years now. The interface is not pretty, but it does what it says. Most people log in, check their balance, maybe pay a bill or two, and then close the tab. That leaves a lot of money on the table without anyone noticing. The platform has a whole section buried under the main dashboard that most users never explore. Once you figure out where things live, it actually saves you time and occasionally drops cash in your lap. Here is how I actually use it beyond the basics.
Unlock Exclusive Perks Mastering Wellsfargo On Line For Savvy Banking
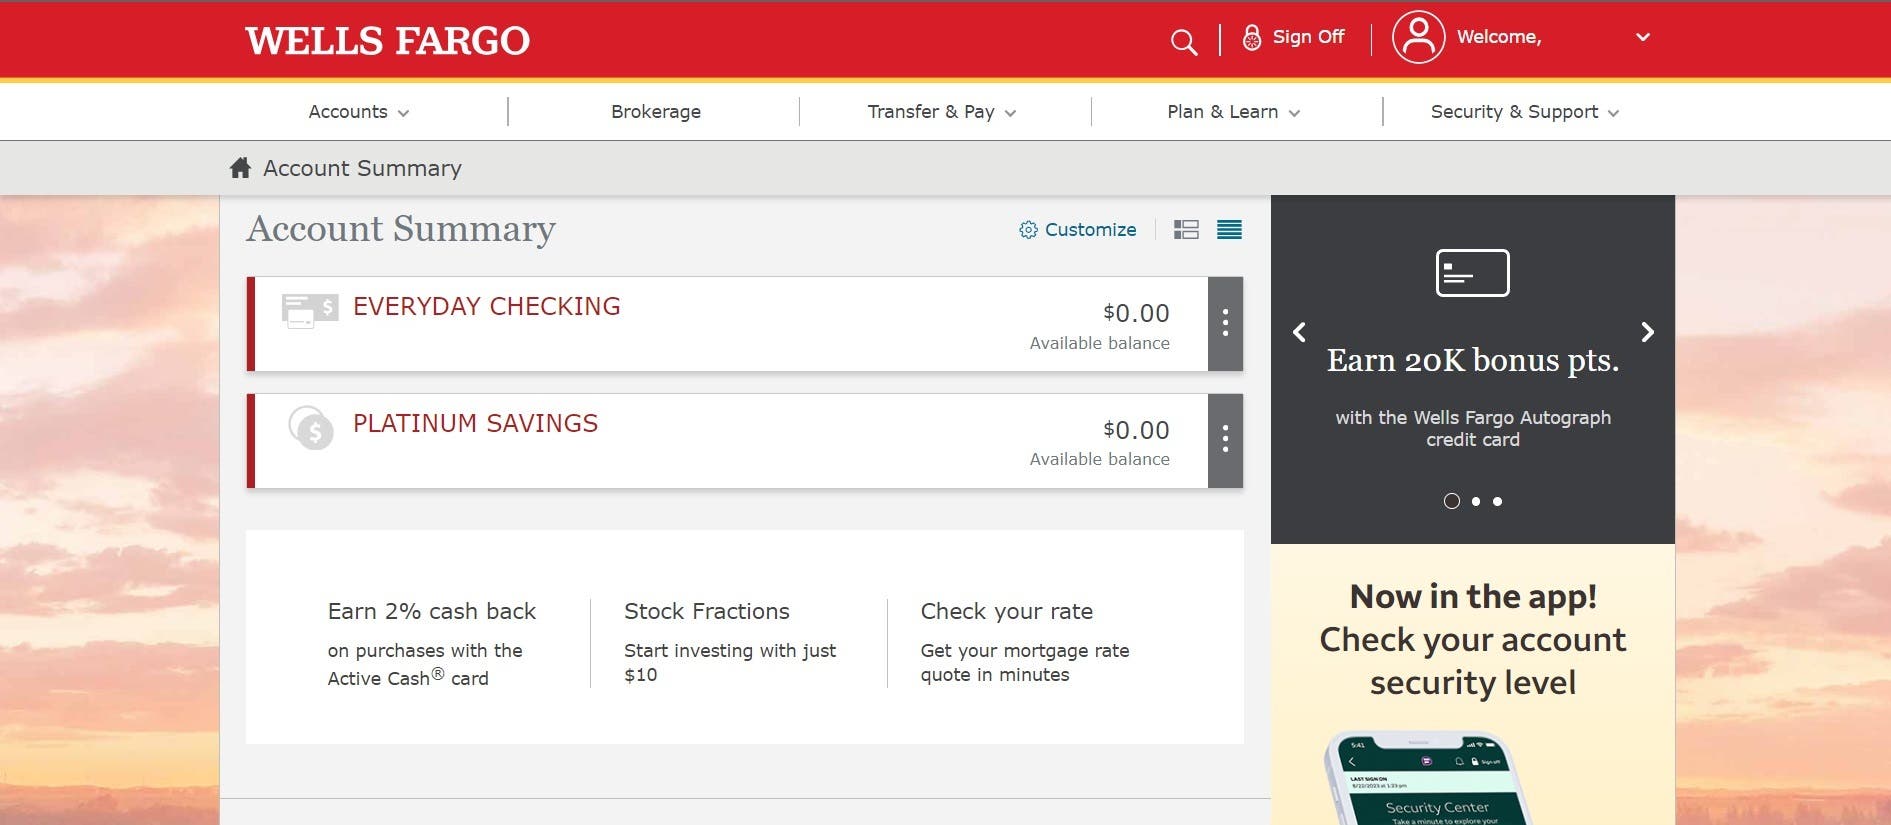
The perks section does not advertise itself loudly. You will find it if you navigate to the accounts overview, then look for a small "Perks & Offers" or "Rewards" tab that appears depending on which type of checking account you hold. It is not always visible on the main landing page. Sometimes you need to click through to your specific checking product page first before the offers panel loads. I spent about ten minutes staring at a blank screen before I realized I had to select my individual checking account from the dropdown rather than staying on the general dashboard. The types of perks available vary significantly by account tier. If you have a standard Everyday Checking, you are looking at occasional cashback offers from merchants like Shell or Target. If you have a Benefit Checking account, the offers expand to include higher value merchant discounts and sometimes fee rebates. The key thing nobody mentions is that these offers are not automatic. You have to actively click "Enroll" on each one before you make a purchase, and the enrollment usually expires after 30 days if you do not complete the qualifying transaction. I learned this the hard way after missing out on a $50 cashback offer from a coffee chain because the enrollment window closed while I was traveling. Another thing that is not obvious: the rewards credits that come with certain checking accounts do not always post to your account on the same cycle as your regular statements. They can take 30 to 45 days to appear, and sometimes they show up as a separate line item rather than folded into your statement total. If you are tracking your net income against expected rewards, factor in that delay or you will think the money disappeared.
The mobile app version of Wells Fargo Online has its own quirks. The app tends to cache old data, which means your displayed balance can lag behind real-time transactions by several hours during busy periods. I noticed this after a large purchase went through on my card but the app still showed me as having sufficient funds, which would have triggered an overdraft if I had tried to spend the difference. The workaround is to refresh the account view manually rather than trusting whatever sits on your screen. Pull down to refresh and wait for the green checkmark before making any decisions based on that balance number. There is a budgeting tool inside the platform called My Wells Fargo Deals combined with the spending analytics feature. It categorizes your transactions automatically, but the categorization is notoriously sloppy with certain merchants. A purchase at a grocery store that includes pharmacy items might get split incorrectly between dining and healthcare, throwing off your monthly averages. I spent an afternoon manually recategorizing about forty transactions across three months to get accurate numbers. It takes effort upfront, but once the categories are corrected, the monthly trends become actually useful for spotting where your money is going. One advanced feature that most people miss is the ability to set up internal transfer rules between your own accounts. You can automate moves from checking to savings on a recurring basis, but you can also set up conditional rules like "if my checking balance drops below $500, move $200 from savings to cover it." This is not a built-in feature through the web interface alone, but you can achieve similar results by linking external accounts and setting up overflow transfers through the bill pay section. I have my extra checking account pulling from my savings every time the balance hits a threshold, and it has saved me from overdraft fees more times than I can count.
Get the Full Details

The customer service side of things is where the platform really shows its age. Calling them puts you through a maze of options, and the chat feature sometimes drops your session if you are navigating multiple pages at once. I once had a chat session terminate while I was trying to verify a suspicious charge, and I had to start from scratch and wait another twenty minutes on hold. The best workaround is to screenshot everything before you close any page, keep your account numbers handy in a password manager, and preferably call during off-peak hours between 2 and 4 PM on weekdays when the wait times drop significantly. Security is handled reasonably well. They use multi-factor authentication through their WF Secure Code system, which sends a code to your registered phone number or generates one through their app. Enable biometric login on the mobile app as well, because it cuts down on the friction of logging in daily without sacrificing meaningful security. The one gap I have noticed is that the desktop portal does not support passkeys or hardware security keys for login, which feels outdated compared to what most other major banks offer now. If security is a top concern for you, use the mobile app for routine checks and reserve the desktop for larger transfers where you want the extra step of the Secure Code verification. The direct deposit setup is straightforward if you know where to look. It is under the accounts menu, then "Set Up Direct Deposit," but the form only accepts information in a specific format. If your employer uses a different routing number format like a 9-digit ABA mixed with a branch code, you may need to call them to get the exact composite routing number for electronic deposits. I wasted about fifteen minutes trying to submit a direct deposit form with the wrong routing number before calling the support line and getting the correct one read to me over the phone.
Statement preferences can be changed to go paperless, which saves you mail and gives you instant access to records. However, if you need statements for a loan application or rental agreement, you should download and save PDF copies immediately after they post rather than relying on the portal to retain them indefinitely. I had a landlord who required three months of consecutive statements, and I realized too late that the portal only kept the last six months viewable without a formal request. Making that request involved filling out a form and waiting five business days for the statements to be compiled and mailed to me. Save your PDFs locally and you avoid that headache entirely. The Zelle integration is convenient but it operates on a different timeline than regular transfers. Money sent via Zelle typically arrives within minutes during business hours, but if you send it late on a Friday or over a holiday weekend, it can sit in pending status until the next business day. I learned this when I sent rent to my landlord on a Saturday and she did not see the funds until Monday morning, which caused an awkward conversation about whether she should consider it received. The timing is usually fast enough, but do not treat Zelle as an instant settlement method for time-sensitive payments near weekends or holidays. Overall, Wells Fargo Online is functional but it demands that you actually explore its features rather than treating it like a balance checker. The perks exist, the tools work, and the security is adequate. What it lacks is intuitive design and proactive guidance about features that could save you money. You have to be the one to dig into the settings, enroll in offers, set up automation, and understand the limitations before they bite you. That is the reality of it.