The Ulta Credit Card Is Not What Most Shoppers Think It Is
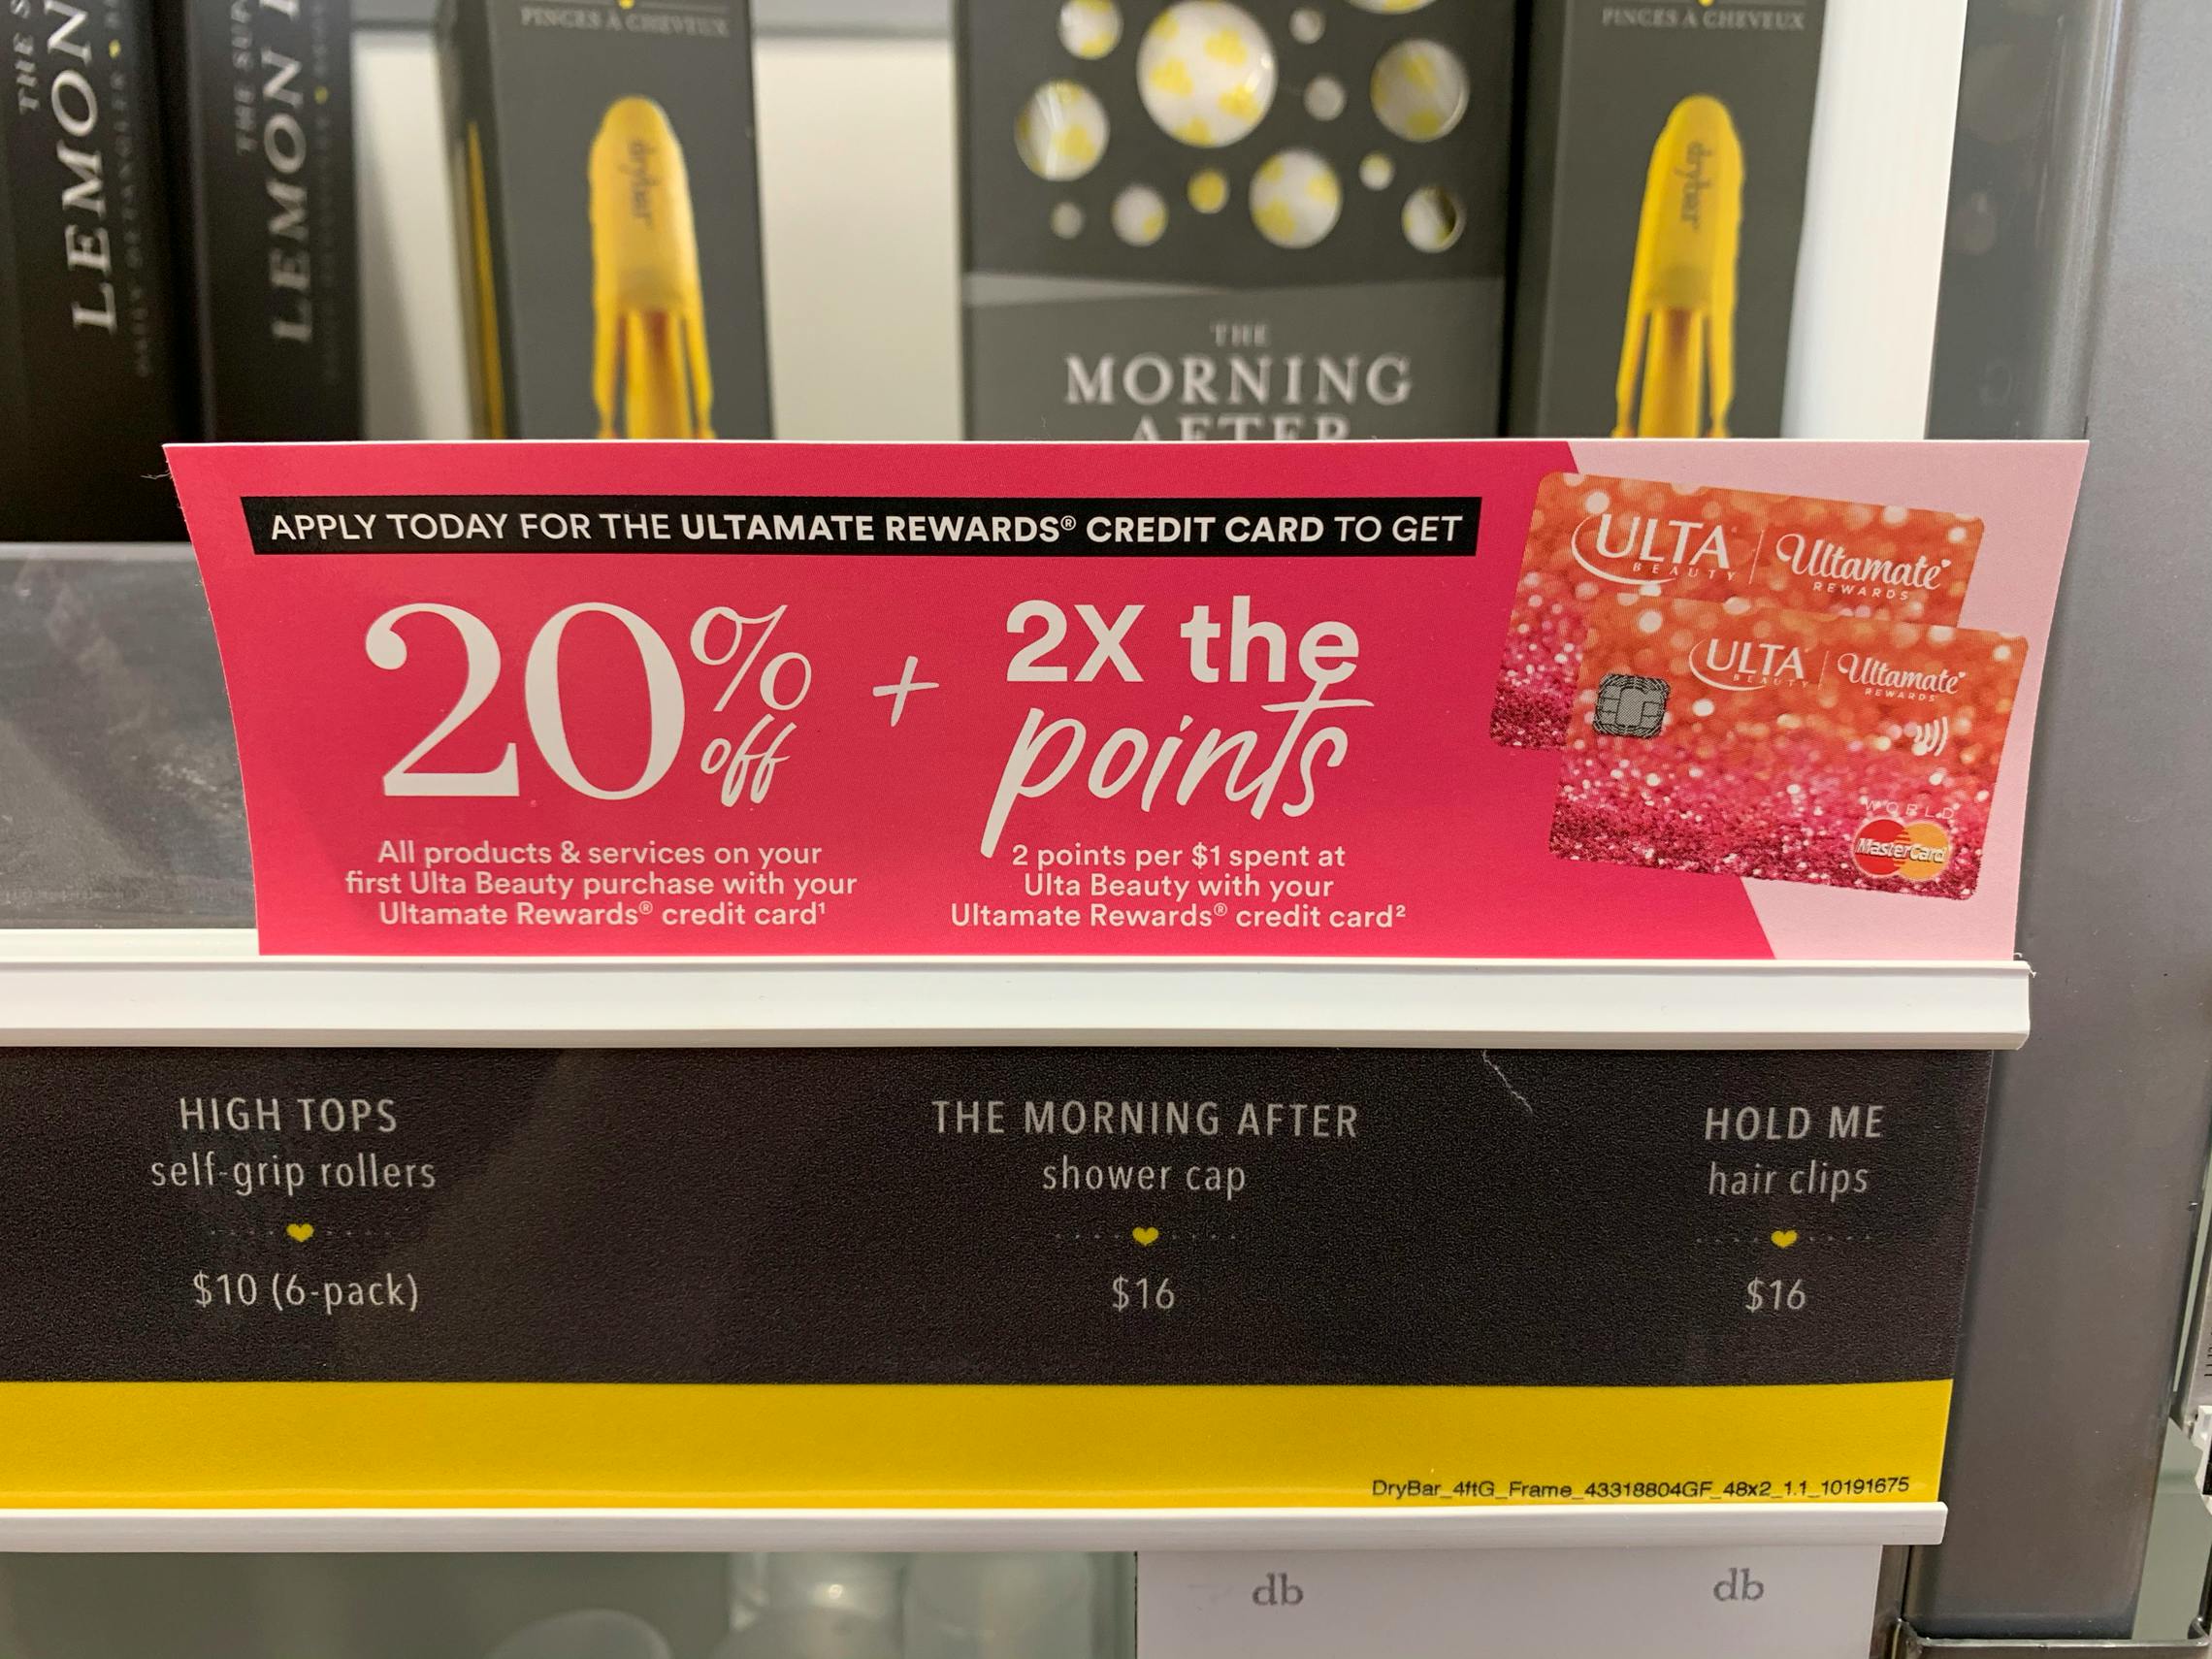
I opened the Ultamate Rewards Credit Card during a Sephora sale and immediately regretted it. The approval came fast, the rewards structure looked generous on paper, and I was three orders into a skincare haul before I realized the math was working against me. Not because the card is bad, but because nobody tells you how to actually use it profitably. Here is what I learned after 18 months and roughly $4,200 in Ulta purchases, plus the edge cases that nearly cost me money. Ulta issues two distinct cards through Comenity Bank: the Ultamate Rewards Credit Card and the Ultamate Rewards Premium Credit Card. They are not interchangeable. The Standard card gives you 1 point per dollar on all Ulta purchases, while the Premium tier raises that to 2 points per dollar. Both cards earn 1 point per dollar on non-Ulta purchases, but only when you have an active Ulta Rewards account to attach them to. You cannot earn points without the loyalty account. That is the first thing most people miss when they apply. The real value sits in the tier system. Elite members get 20% off every day, free standard shipping on online orders, and a birthday gift. The credit card bumps your spending thresholds faster. Without the card, you need to spend $750 annually to reach Ultra/Elite status. With the card's 2x earning at Ulta, that $750 threshold becomes functionally lower because you accumulate points faster and your spending history reflects the card transactions more prominently. You still hit the same $750 mark, but the card makes the path less awkward if you were already planning to shop there regularly.
The points themselves expire after 24 months of account inactivity, not after 12 months like some loyalty programs. If you stop shopping at Ulta for two years, your balance disappears. I learned this when I checked my account in January 2025 and found about 3,400 points gone from my last activity window. The workaround is simple: make a $1 purchase every 18 months to reset the clock. Nothing elaborate. A lip balm. A travel-size hand sanitizer. Whatever sits at the register.
The 20% Off Benefit: How It Actually Works
Elite and Ultra members receive 20% off one regular-price item per month. This sounds straightforward until you encounter the exclusions. Fragrance, electronics, and certain limited-edition collaborations do not qualify. I once tried to apply my 20% to a $68 La Mer moisturizer during a half-off sale event and the system rejected it outright because sale items are excluded from the monthly 20% benefit. The discount only applies to regular-priced merchandise. You can combine the monthly 20% with a 20% off coupon from Ulta's email campaigns on regular-price items, but not with existing promotions on that same product. Here is the counter-intuitive part: the 20% off your monthly item is often worth more than the points you would earn by paying full price. A $50 regular-price item gives you 50 points at the Standard card rate or 100 points at Premium. Those 100 points convert to roughly $3.50 in rewards certificates. A 20% discount on $50 saves you $10. The math favors the discount every time unless you are chasing a specific point threshold to trigger a status bump. Most people are not tracking that closely enough to optimize around it.
Get the Full Details

The Premium Card Upgrade: Who Actually Needs It
The Premium card costs $0 annual fee and requires a higher credit limit approval. It doubles your in-store earning rate to 2x points per dollar. After spending about $1,500 at Ulta annually, the Premium card starts outperforming the Standard card purely on point accumulation. Before that threshold, the Standard card is economically neutral to slightly better because you are not gaining enough volume to justify the application friction. I kept the Standard card for the first year, upgraded to Premium in month 14, and only then saw a material difference in my end-of-year certificate totals. There is a catch nobody mentions publicly. When you upgrade from Standard to Premium, your points do not retroactively convert. All prior purchases remain at 1x. Only new purchases after the upgrade date earn at 2x. If you are close to a redemption threshold—say you have 8,000 points and need 10,000 for a $35 certificate—the upgrade will delay your redemption by however many months it takes to accumulate those missing 2,000 points at the new rate. My workaround was to time my upgrade request right after I redeemed a certificate, resetting my point balance low enough that the 2x acceleration immediately put me back on track within a single shopping cycle.
Common Pitfalls That Cost Me Money
First pitfall: using the card at third-party retailers that look like Ulta. Ulta operates some concession areas inside Walmart and Target. Purchases at those locations do not earn Ulta points. I charged $127 to my card at a Ulta concession in a Target and spent twenty minutes on hold with Comenity Bank before realizing the merchant category code classified the transaction outside the rewards network. The fix was to call Comenity and request a manual point adjustment, which they processed within five business days. You need your receipt and the exact date of purchase. Without documentation, they will deny the request. Second pitfall: the birthday gift is not automatic. You must be an enrolled Ultamate Rewards member with your birthday correctly listed in your profile. If you applied for the card using a different birthdate than what is on file in your loyalty account, the birthday gift will never trigger. I discovered this when my sister used her phone to place an order and the system pulled her account data, which had an incorrect year on her birthday field. We corrected it through the app settings and received a $10 rewards certificate as a makeup gesture the following week. The resolution took four days.
Download and Application Process
You apply directly through Ulta.com or the Ulta Beauty app. The app walks you through the Comenity Bank application, which pulls a soft credit inquiry. Approval decisions are instant for most applicants. If you receive a conditional approval, you have ten days to provide additional documentation—usually a photo of a government-issued ID and proof of income—to complete the activation. The card arrives by mail in approximately seven to ten business days. Some applicants report receiving it sooner if they have an existing relationship with Comenity Bank, likely because the bank already has your on file. If you shop at Ulta less than twice a year, the card offers minimal value. The points evaporate if you go inactive, and the 20% monthly benefit goes unused. A cashback card like the Citi Double Cash or the Wells Fargo Active Cash would return 2% on the same purchases without any enrollment hoops or expiration risk. The Ulta card only makes sense if your annual Ulta spending exceeds $600 and you actively plan to use the monthly 20% benefit on regular-price items. Anything below that threshold is leaving money on the table compared to a straightforward cashback alternative. The card also does not provide travel insurance, purchase protection, or extended warranty benefits. Comenity Bank cards are generally minimalist in their perks. If you are looking for a card that replaces other protections you currently carry, this is not it. I learned that the hard way when a hair dryer I bought with the card shorted out three weeks after the manufacturer's warranty expired, and I had no purchase protection to fall back on.