Getting the Walmart Credit Card Without Wasting Your Afternoon
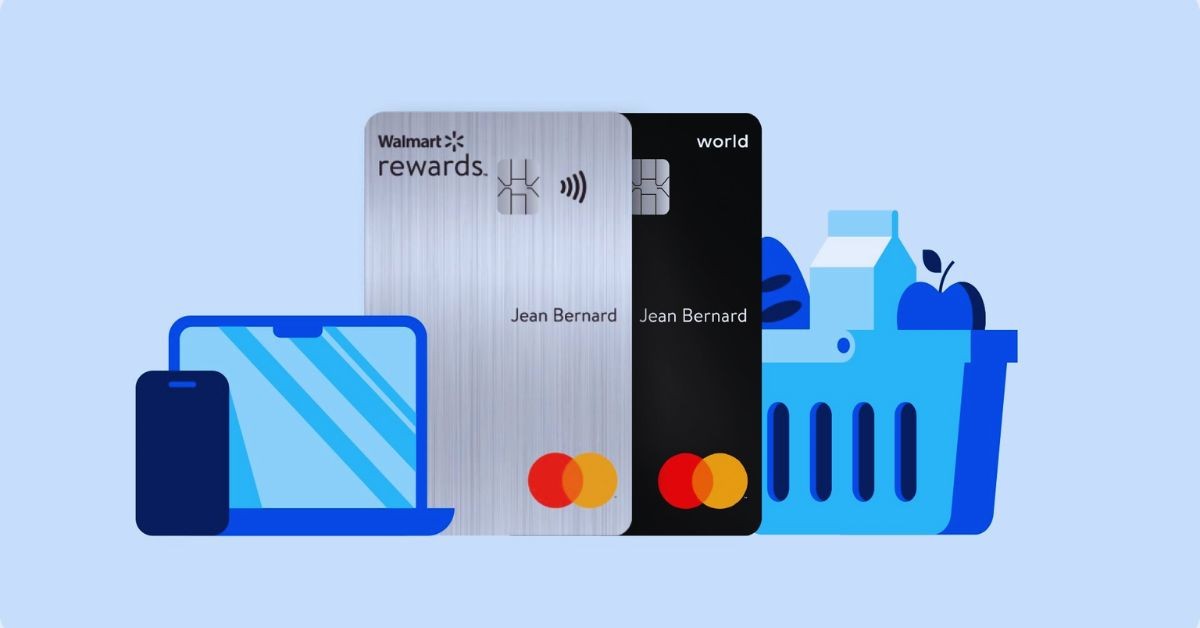
The Walmart credit card comes in two flavors from Citi: the store card and the Walmart Rewards Mastercard. The store card only works at Walmart and Sam's Club, but it gives you 5% back on everything you buy there when you use it at checkout. The Mastercard version gives you 1% back everywhere and 5% at Walmart. Most people asking about this just want the store card because the 5% return is actually competitive if you shop at Walmart regularly. I've opened this card about three times over the years for people in my family, and I know where the process trips people up. You start on the Walmart website and look for the credit card section, or you do it at the register. The in-store application is actually faster for most people because the associate can pull up your purchase history and run it immediately. Online takes longer because you sit through a Citi verification flow that asks for your Social Security number, annual income, and employment details. Either way, the soft pull to check your odds doesn't hurt your credit score. The hard inquiry happens only after you formally approve and accept the card terms. The application itself takes about five to eight minutes if you have your information ready. Fill in your personal details, choose whether you want the store card or the Rewards Mastercard, and select your preferred card design. If you're applying in person at Walmart, bring a government-issued ID and your last pay stub or tax document showing your income. The associate won't ask for these unless the automated system flags something about your income level.
Decisions are typically instant. Most applicants know within sixty seconds whether they're approved, denied, or sent for manual review. If you get the instant approval, your card number is activated immediately and you can use the digital card in the Walmart app right away while you wait for the physical card to arrive in seven to ten business days. The digital card works at the register the same day. One thing people consistently miss is the promotional financing offers. Walmart sometimes runs 6-month or 12-month special financing on purchases over a certain threshold, usually $299 or more. This isn't automatic. You have to make sure the promo financing option is selected at checkout or when you apply during a promotional window. If you don't, you're just on the standard variable APR which currently sits somewhere in the high 20s percentage range. I learned this the hard way a couple years ago when my sister bought a television and didn't realize the 12-month promo was expiring that same day. We ended up paying the full amount before the promo window closed, which would have saved her about $40 in interest. The workaround was setting a phone reminder the moment you decide to apply for financing and actually confirming the promo terms on your confirmation screen before you hit submit. Here is where the card gets complicated and where beginners usually make mistakes. The 5% back reward is not the same as cashback on a regular credit card. It comes as a Walmart reward certificate that gets loaded onto your account, not as a statement credit. You use it the next time you shop at Walmart or Sam's Club. It expires after one year from the date it is issued. If you are not a regular Walmart shopper, this reward structure basically becomes worthless to you because you cannot spend it anywhere else.
Another detail that nobody mentions upfront is the delayed interest option. When you apply, Citi sometimes offers a delayed interest promotion on qualifying purchases. If you pay off the full balance by the end of the promo period, you pay zero interest. If you miss that deadline by even one day, interest is charged retroactively to the original purchase date. This is not a small penalty. The retroactive interest can add up quickly on a large purchase. I once watched someone get hit with $60 in retroactive interest on a $400 purchase because they paid $399.50 instead of the full $400 by the due date. A $0.50 mistake cost them sixty dollars. The workaround is setting up automatic payments for at least the full statement balance every single month. Approval odds are generally easier than most retail cards. Citi tends to approve people with credit scores in the 600 to 670 range, though this varies. Being employed and having a steady income reported helps. If you have too many recent hard inquiries, your chances drop significantly. Applying when your credit utilization is already high over 50 percent on other cards is another way to get denied. The card is designed to be accessible, but Citi still runs the same underwriting checks as any other issuer. If you get denied, you can reapply after thirty days. The denial reason will be listed on the screen or in the mail notice. Common reasons include insufficient income, too much existing debt relative to your income, or a hard inquiry taken within the last two weeks from another Citi card application. You do not need to wait for a long period if the denial reason is something temporary like a recent hard inquiry. Wait thirty days, let that inquiry age, and reapply. If the denial is based on low credit score, you should focus on improving your score first rather than spamming applications.
Get the Full Details

The annual fee is zero. That is straightforward. The APR range is roughly 19.99 to 29.99 percent variable depending on your creditworthiness. There is a foreign transaction fee of 2.7 percent of each transaction. No balance transfer fee is listed on the standard terms, but the card does not offer a balance transfer option at all. You cannot move debt from another card onto this one. The biggest practical downside is the narrow acceptance. The store card only works at Walmart and Sam's Club. If your primary shopping is elsewhere, the 5% back is irrelevant. In that case, you should look at a general cashback card instead. Something like a no-annual-fee card with 2 percent back on groceries and dining would serve you better over time. The Walmart card is a niche product for a niche shopping habit. Another hidden friction point is that reward certificates do not combine with certain promotions. If Walmart is running a buy-one-get-one deal or a bundle discount, using your reward certificate at checkout may void the additional savings. Always check whether applying your certificate reduces your total discount. Sometimes paying full price and skipping the certificate leaves you better off, especially on electronics and appliances where the margins are already thin.
To apply, go to the Walmart credit card page online or ask at any Walmart customer service desk. The in-store option is faster if you are already shopping. Have your ID, proof of income, and Social Security number ready. Choose between the store card and the Rewards Mastercard. Confirm whether a promotional financing offer is available for your intended purchase and lock it in before you finish. Set up autopay to avoid the retroactive interest trap. Keep track of when your reward certificates expire so you actually use them before they go stale. The card works if you shop at Walmart frequently and you can pay your balance in full every month. It fails as a general-purpose credit tool. Treat it like what it is, a single-retailer financing option with a decent reward rate for that specific retailer, and it will save you money without creating problems.