How the TSC Credit Card Actually Works
The Tractor Supply Co. credit card is a store-issued Visa distributed in partnership with Barclays. It exists primarily to keep you buying at their locations rather than going to Home Depot or Lowe's. I've used mine for three years straight, mostly on feed, fencing supplies, and the occasional holiday decoration run. You'll find two variants when you apply: the standard TSC Store Card and the TSC Visa. The Store Card only works at Tractor Supply and their affiliated online portal. The Visa version carries the Mastercard logo and works anywhere Visa is accepted, though the promo financing deals typically only apply to purchases made in-store or on their website.
Unlock Exclusive Benefits The Ultimate Guide To The Tsc Tractor Supply Credit Card
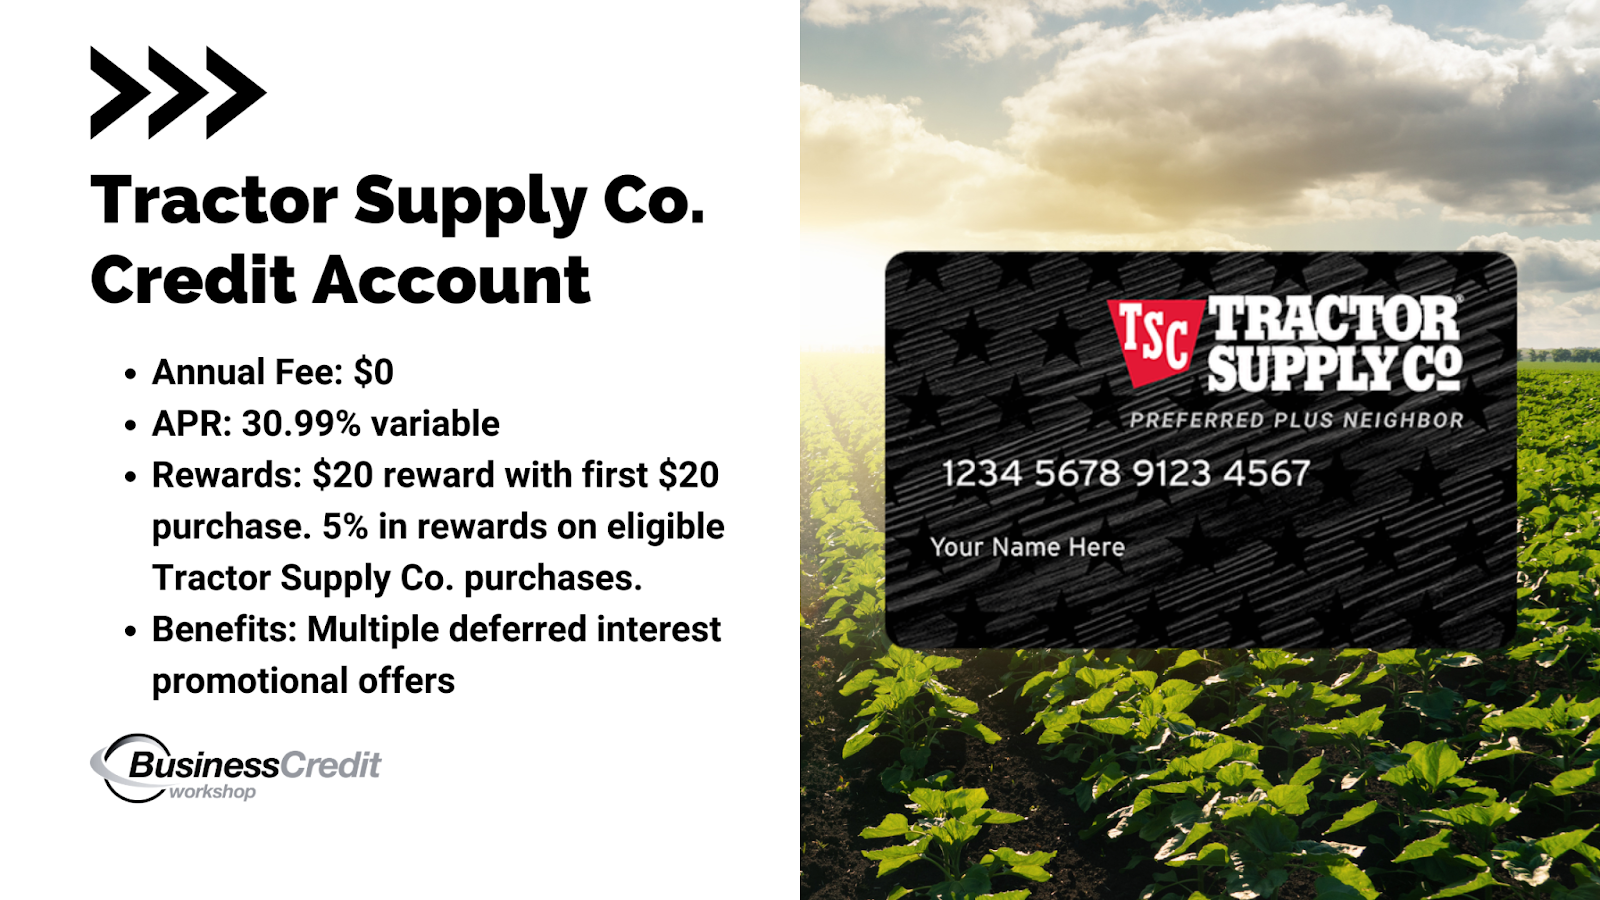
Here's what you actually get. New cardholders routinely qualify for a one-time discount on their first purchase, which varies by region and promotion but has been sitting around twenty percent for the past couple of years. There's also a birthday discount that drops into your account automatically if you've provided your birth date during application. That one's usually ten percent off a single transaction. The recurring benefit most people talk about is the weekly deal. TSC runs rotating sales on specific product categories every week, and cardholders get access to those discounts before non-cardholders. On a recent run, I saved roughly forty dollars on tractor tires during a cardholder-only promotion that didn't stack with any other coupon. That's the realistic value proposition right there. Financing is where this card gets interesting and also where it gets dangerous. They occasionally advertise deferred interest promotions, usually twenty-four months on purchases over a certain threshold. I saw a post-sale event that offered eighteen months same-as-cash on orders above three hundred dollars. The terms are straightforward: pay the full balance within the promo window and you pay zero interest. Miss by even one dollar and they back-charge interest on the entire original purchase amount at the card's standard rate, which runs around twenty-four percent APR.
I hit that exact scenario last spring. I put a riding mower and a trailer on the card with the eighteen-month deferred interest offer. Life happened. I paid down most of it but came up short by about sixty dollars in month seventeen when a different medical expense ate into my budget. The deferred interest clause triggered retroactively. I owed approximately one hundred and eighty dollars in back-interest on top of the remaining principal. Barclays sent me the statement, I called customer service, and after about twenty minutes on hold they reduced the back-charge by half as a one-time courtesy. Don't count on that happening again. Here's something most guides won't tell you: the credit limit on these cards tends to start low. I was approved for five hundred dollars on my first application with no prior relationship to the bank. That limit increased to twelve hundred after about eight months of on-time payments. If you're planning to make a large purchase right away, you'll likely need to request a limit increase before checking out, and those requests aren't instant. I submitted one through the Barclays portal and it took three business days to process. Another thing that catches people off guard is the rewards structure. This isn't a cash-back card in the traditional sense. You earn membership rewards points, but they're tied to the TSC loyalty program, not a universal reward system. Points expire if you don't make a qualifying purchase within eighteen months. I had about three hundred points sit unused while I was between projects, and they vanished entirely. Set a reminder on your phone if you're accumulating points.
Get the Full Details
Application Process and What to Expect
You apply through the Barclays website. Soft pull initially, hard pull upon approval. The decision is usually instant. I got approved in under two minutes. Your physical card arrives in about seven to ten business days, but you can use a virtual card immediately through the Barclays mobile app to start shopping online right after approval. Minimum credit score expectations hover around six hundred, though I know people with scores in the high five hundreds who've been approved. Having an existing checking relationship with Barclays seems to help slightly. I mentioned my Barclays checking account during the application and it may have nudged the approval decision. Not guaranteed anything, just an observation. The annual fee is zero. That part is honest. No secret charges, no surprise fees beyond the standard late payment and returned payment penalties that come with any credit product. Missing a payment triggers a fee around forty dollars and your APR jumps to the penalty rate, which is roughly thirty percent. Paying more than your minimum doesn't count toward the deferred interest clock unless the full statement balance is cleared by the due date.
When This Card Makes Sense and When It Doesn't
This card works well if you're a regular Tractor Supply customer who already buys feed, tools, or seasonal items on a quarterly basis. The weekly cardholder deals alone can offset the opportunity cost of having another account open. If you shop there once a year for Christmas lights, the math doesn't favor you. You'll carry the psychological weight of another billing cycle for minimal return. The deferred interest financing is a legitimate tool if you're making a planned, large equipment purchase and you're confident you can clear the balance within the promotional window. I'd recommend setting up autopay for at least the minimum payment, then manually paying down the principal each month to track your progress. Relying solely on autopay leaves you vulnerable to the back-charge trap if your automatic payment doesn't cover the full remaining balance when the promo period expires. If your credit is fragile right now, applying here will show up on your report as a new inquiry and a new account. Both factors dip your score temporarily. If you're shopping around for multiple credit cards within a short window, the inquiries compound. Space your applications out by six months if possible. The TSC card isn't exactly a premium rewards product, so don't expect it to elevate your credit profile significantly beyond what responsible payment history already does on its own.
Customer service operates on standard banking hours with moderate hold times. I'd estimate average wait times of twelve to fifteen minutes during weekdays. The mobile app handles most routine tasks, but calling is necessary for limit increases, dispute resolution, and anything involving the deferred interest terms. Keep your promo qualification emails and the exact terms sheet from your application. When the back-charge controversy hit me, having the original promotional document saved made the conversation with Barclays significantly faster and more productive.