Setting Up Apple Pay on Your iPhone
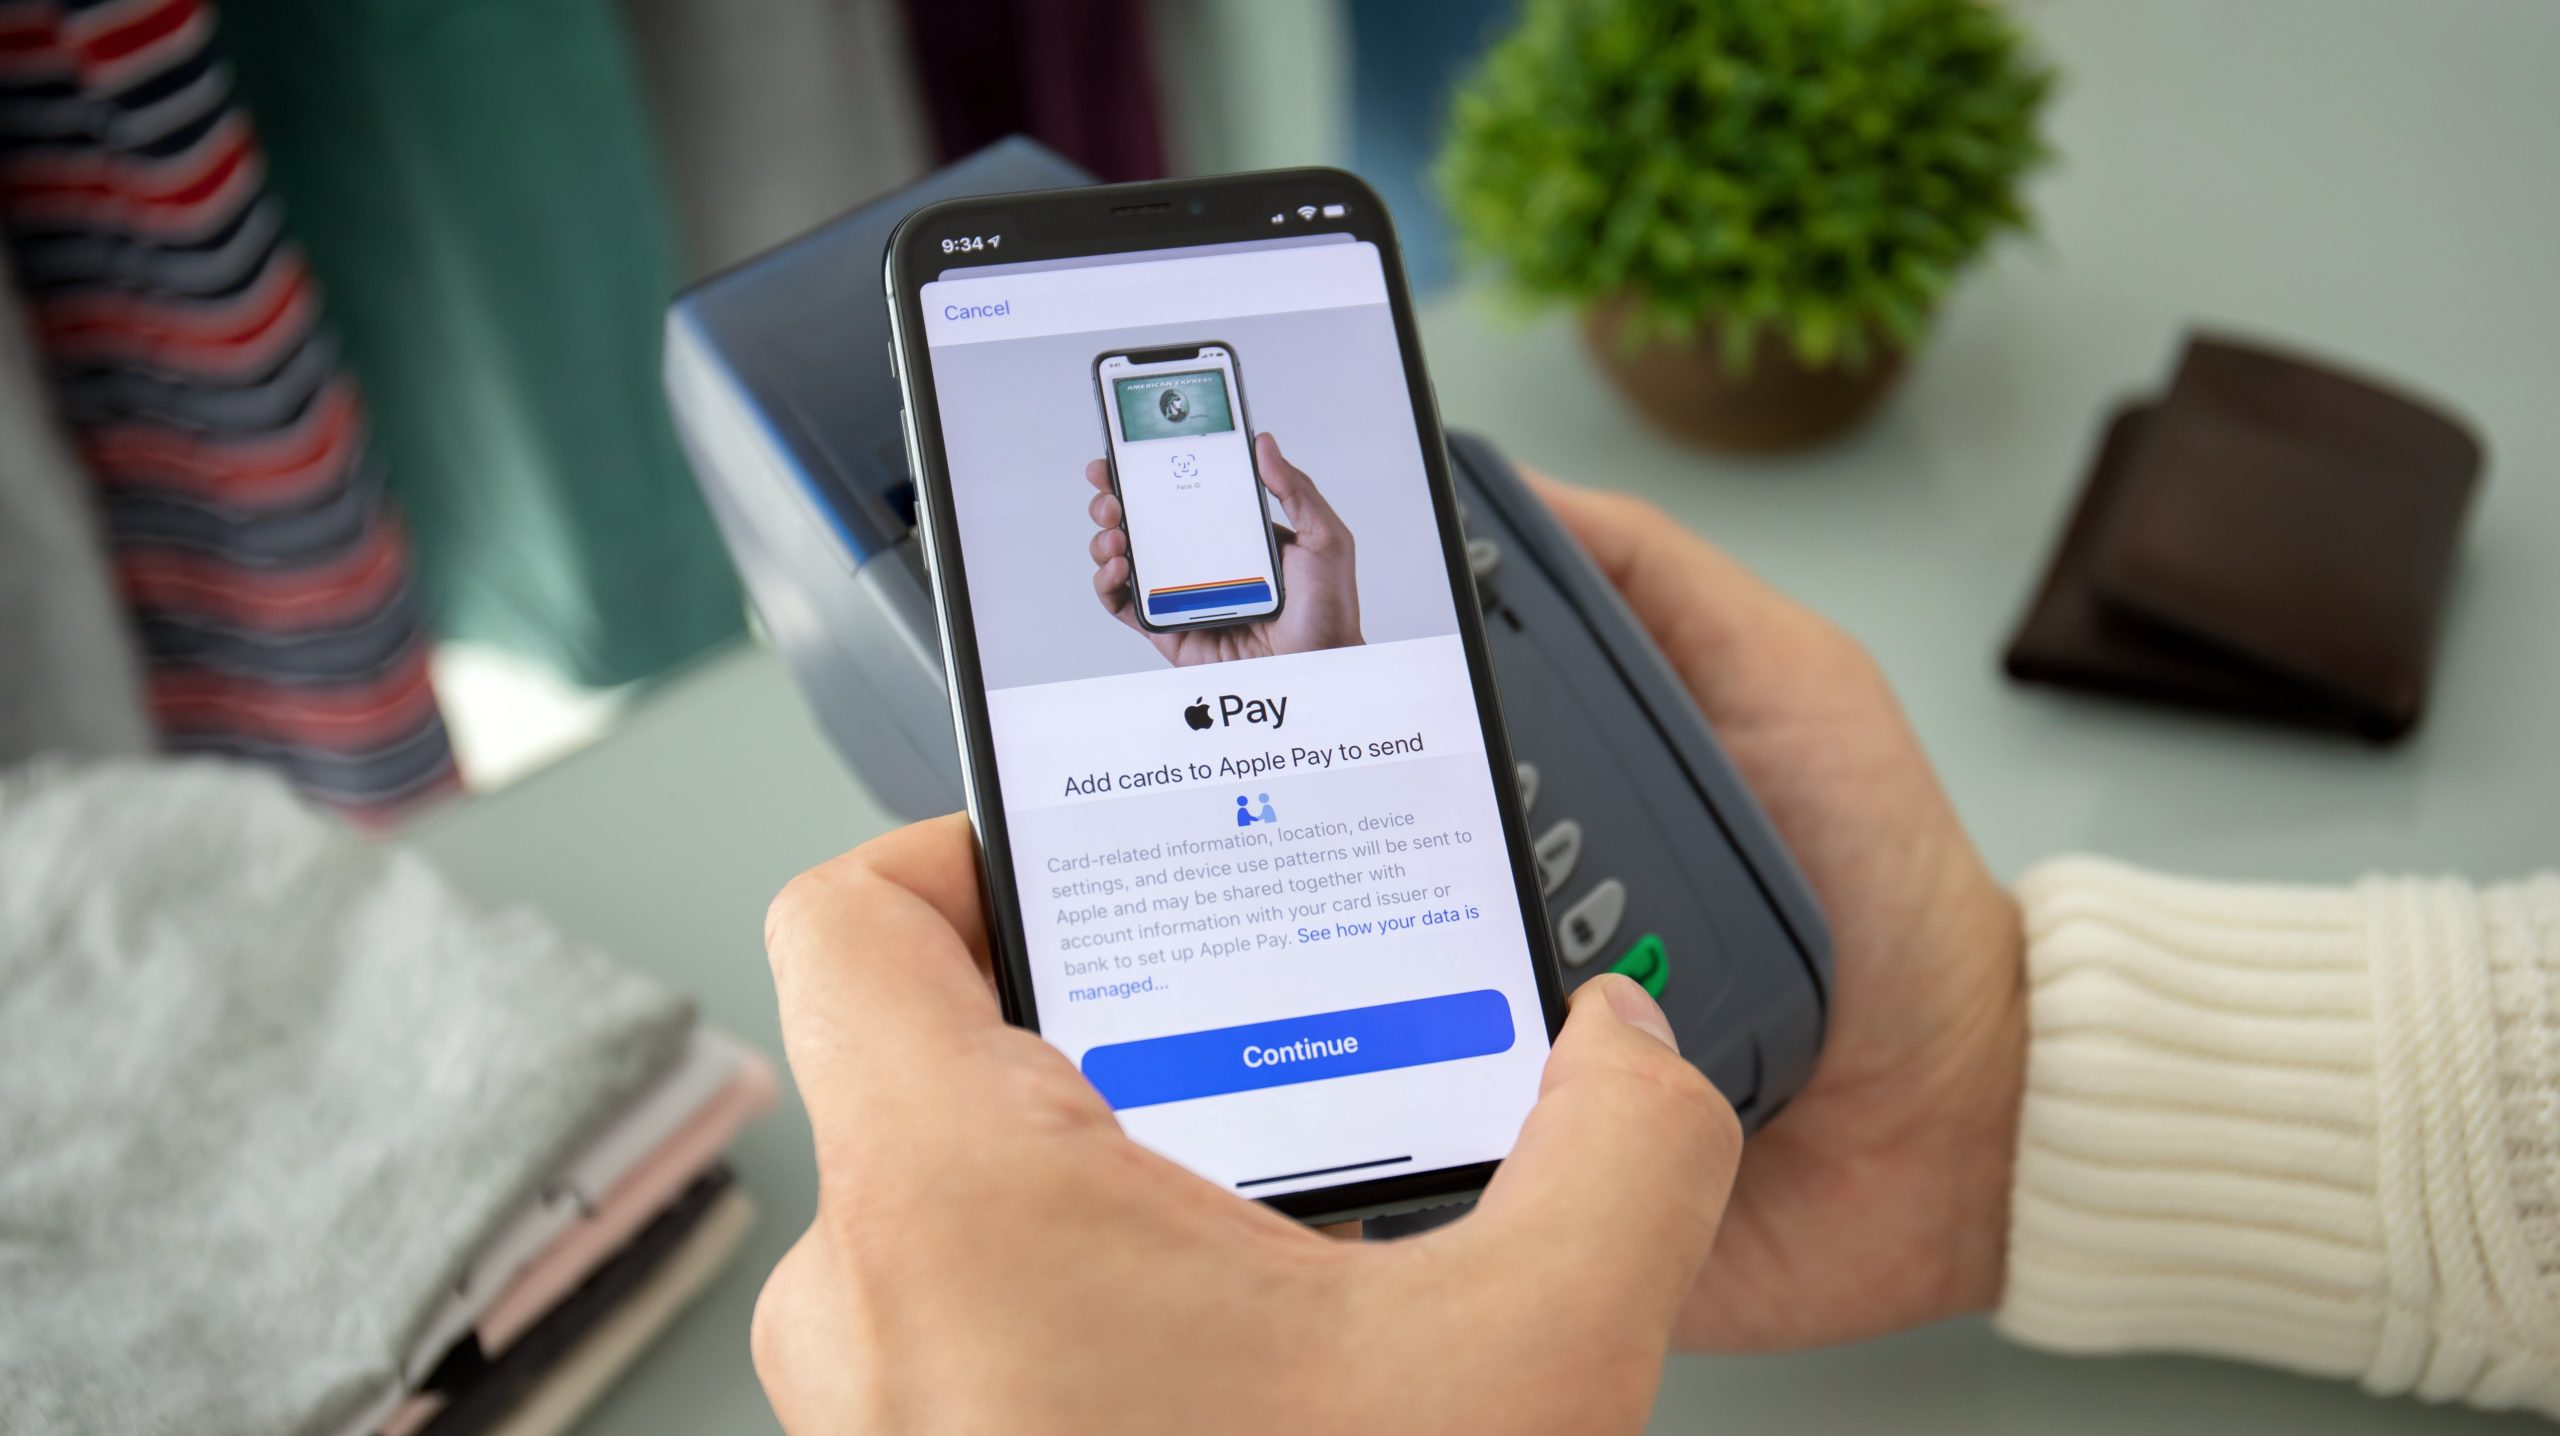
I've been using Apple Pay since it came out on the iPhone 6 back in 2014, which feels like forever ago. Most people find the setup straightforward, but there are a few things that trip people up. I'm going to walk through what actually matters instead of repeating the standard marketing copy. The first thing you need is a supported card. Not every bank participates, and some issuers restrict certain card types. I ran into this exact problem when trying to add a prepaid debit card to my wallet — Apple Pay simply rejected it without any explanation beyond "Your card cannot be added." After calling the card issuer, I learned they don't support tokenization for their prepaid product. The workaround was switching to my primary checking account's debit card instead, which worked immediately. Open the Wallet app on your device. Tap the plus button in the upper right corner. You can add a card manually or use your camera to scan it. The camera method is faster but occasionally misreads the expiry date or CVV. If that happens, switch to manual entry — it's only a few extra seconds.
After you submit the card details, your bank will verify ownership. This usually takes under a minute for major banks. Some smaller credit unions might email you a code instead of doing instant verification. I once waited 47 minutes for a verification email that ended up in my spam folder. Check spam before you assume something is broken. Once verified, the card is ready. There's no activation step like you'd do with a physical card — Apple Pay handles tokenization automatically. Your actual card number never touches the merchant's system. Instead, a device-specific account number gets generated and stored in a secure element on the chip.
Using Apple Pay at Point of Sale
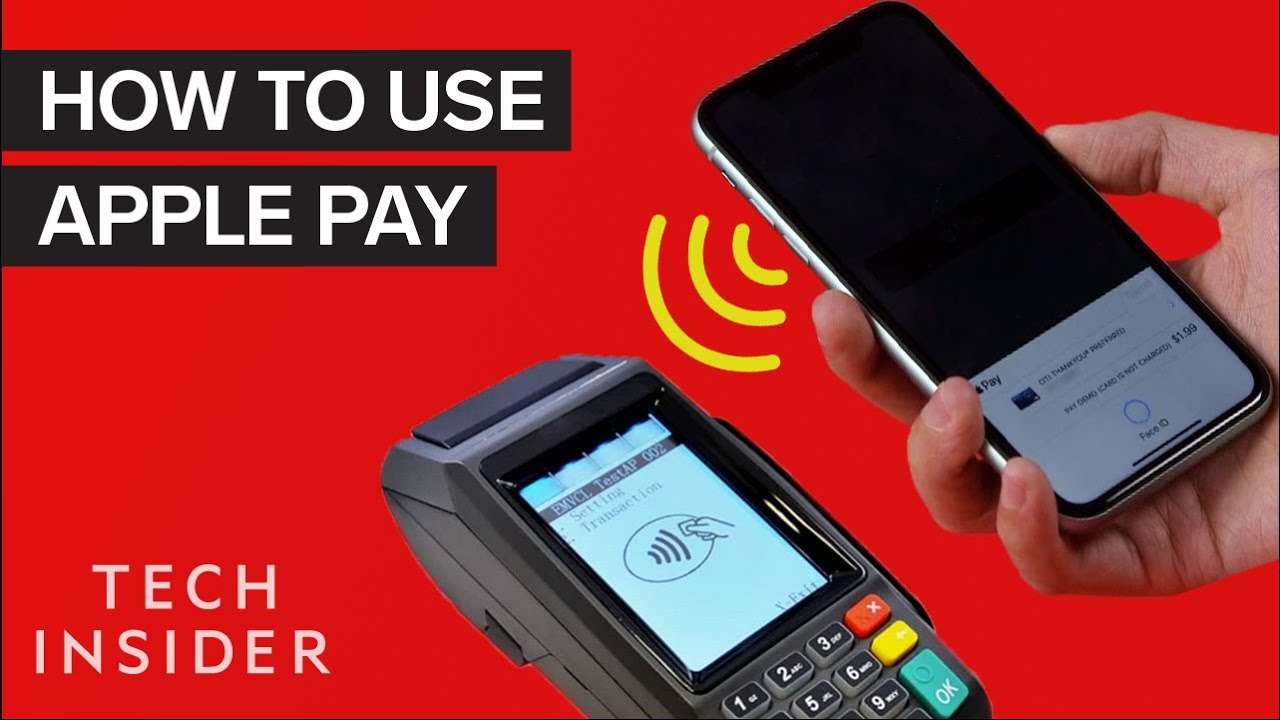
Hold your iPhone or Apple Watch near the contactless reader. Double-click the side button on newer iPhones to bring up default card, then authenticate with Face ID, Touch ID, or your passcode. The transaction completes when you feel the haptic feedback and see the checkmark. Most purchases under $100 don't even require authentication depending on your region and card issuer settings. I found that some older terminals have quirks. A couple of years ago, a specific grocery chain in my area had terminal firmware that would reject Apple Pay if the customer had more than three cards in their wallet. The reader would time out and show error code 0x8010. The fix was removing all cards except the one I wanted to use before tapping. It's a weird edge case, but it happened repeatedly enough that I learned to clear my wallet first at that store. The speed advantage is real but depends on your habits. If you normally pull out your phone anyway to check something before buying, Apple Pay doesn't save much time. But if you keep your card in a wallet pocket, you skip the entire fumbling step. In practice I save roughly 15 to 30 seconds per transaction compared to digging for physical cards.
Get the Full Details

Online and In-App Purchases
Apple Pay works differently online than in stores. When you're checking out on a website or in an app that supports it, you'll see the Apple Pay button during payment selection. Tap it, authenticate, and the card details fill automatically. No typing your number, expiry, or billing address. One thing most guides don't mention: Apple Pay autofill works with your Safari AutoFill settings. If you've turned off AutoFill for credit cards in your iPhone settings, Apple Pay won't prefill shipping and billing info even if the merchant accepts it. Toggle Settings Safari AutoFill Credit Cards back on if you want the full convenience. I also discovered that some merchants treat Apple Pay transactions differently at the merchant category level. A particular subscription service I use charged me a slightly higher fee when I paid through Apple Pay versus entering my card manually. The difference was maybe two dollars per month. I switched back to manual entry after noticing the pattern over three billing cycles. Apple Pay isn't always the cheaper option depending on how a merchant processes payments.
Security Considerations
People worry about losing their phone and someone using Apple Pay. The secure element isolates your card tokens from the rest of the operating system. Even if your phone is compromised, extracting those tokens is extremely difficult. More importantly, you can remotely disable Apple Pay through iCloud if your device is lost or stolen. Find My iPhone handles this automatically — the moment you mark a device as lost, its payment cards get suspended. There's a tradeoff though. If you enable Contactless on your Apple Watch and then lose the watch, someone can make small purchases without authentication until you lock your iPhone. I recommend enabling Lock Screen immediately if you misplace your watch. The cardinality of your contactless limits means most transactions under $50 won't ask for a PIN on the terminal, so the window of vulnerability is brief but real. Another thing beginners miss: Apple Pay transaction notifications come through silently by default. You won't hear a sound or see a popup for every purchase unless you specifically enable notifications in the Wallet app settings. If you want to track spending in real time, go to Settings Wallet & Apple Pay and turn on Transaction Notifications. Otherwise you'll only see activity in the Wallet app itself, which means you might not notice an unauthorized charge for hours.
Limitations and When Apple Pay Falls Short
Apple Pay doesn't work everywhere. International merchants outside North America and Europe have spotty support. I tried using it at a hostel in rural Thailand and the POS terminal didn't recognize contactless payments at all — had to fall back to cash. Some regional banks in developing markets also haven't onboarded with Apple's payment tokenization network, so even if the terminal supports NFC, your card simply won't appear in Wallet. The refund process through Apple Pay is another friction point. When a merchant issues a refund, it goes back to the original payment method, which is correct, but the timing varies wildly. Card network refunds typically take three to five business days, but I've seen cases where Apple Pay refunds showed up in under an hour and others that dragged on for ten days. There's nothing you can do to speed this up — it depends entirely on the merchant's acquiring bank and the card network routing. Apple Pay also doesn't support every payment flow. Peer-to-peer transfers through iMessage use a different system (Apple Cash) that requires an iPhone and U.S. card setup. If you're sending money internationally, Apple Pay isn't the tool. For recurring subscriptions, some services still require you to re-enter card details even after you've used Apple Pay once, which defeats part of the convenience.
Finally, if you're using an Android phone, this entire ecosystem doesn't apply to you. Google Wallet fills a similar role but has a different partner bank list and fewer merchant integrations in my experience. The technology is comparable, but the practical availability diverges significantly by region and issuer.